AI needs power and computing capacity: Three Griffin holdings with up to 400% upside
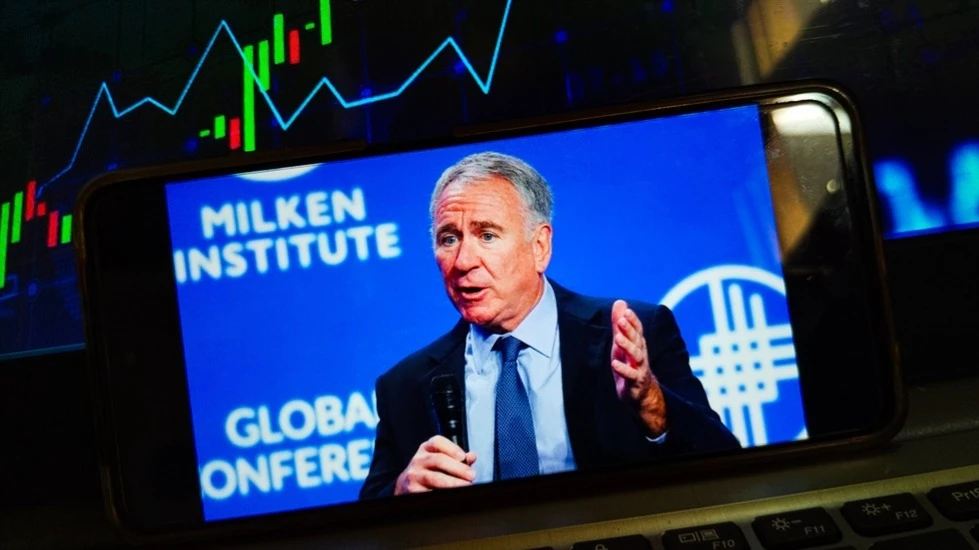
Ken Griffin’s Citadel manages $77 billion, according to company data as of October 1 / Photo: Erlin Diah / Shutterstock.com
In just a few years, AI has evolved from an academic pursuit into a multitrillion-dollar industry: it generates text and video, accelerates scientific discovery, makes robots smarter, drives taxis, and detects cyber threats. The technology’s rapid development and potential have made AI central to corporate strategies, economic policy, and geopolitics, notes the International Energy Agency in a report.
Yet there is no AI without energy. AI models are trained and deployed in power-hungry data centers. A typical AI-focused data center consumes as much electricity as 100,000 households, while the largest facilities under construction will require 20 times as much.
People are often curious about how much energy a ChatGPT query uses; the average query uses about 0.34 watt-hours, about what an oven would use in a little over one second, or a high-efficiency lightbulb would use in a couple of minutes.
The U.S. is the largest data center market. By the end of the decade, the country’s data centers are set to consume more electricity than the production of aluminum, steel, cement, chemicals, and all other energy-intensive goods combined, the IEA estimates.
Electricity is the main resource AI companies are competing for, but it is not the only one. The second is infrastructure. The largest companies tend to build their own data centers, while smaller players may prefer to rent computing capacity from cloud providers, S&P Global writes in a report. The latter approach offers another advantage: it allows companies to avoid numerous challenges, including potential supply disruptions and the need to meet sustainability requirements.
Three AI infrastructure plays
Below are three small companies benefiting from the buildout of AI infrastructure that were held by Ken Griffin's Citadel Advisors as of June 30, according to its second-quarter Form 13F filing.
SharonAI
Australia’s SharonAI, which has a market capitalization of $1 billion on the Nasdaq, provides computing infrastructure powered by high-performance Nvidia graphics processing units through a GPU-as-a-Service model. It operates data centers in Sydney and Melbourne.
For the second quarter, it reported revenue growth of 412% year over year to $1.9 million. The net loss ballooned to 165 times its year-earlier level, reaching $430.4 million. Of that amount, $423.8 million reflected noncash items, including a $400.4 million fair-value loss on convertible notes resulting from the rise in its stock price, the company explained. As of August 6, it had contracts worth $8.8 billion.
SharonAI completed an IPO only in February, offering almost 4.17 million shares at $30 apiece. The stock has since fallen 6.7%. It has eight analyst ratings, all “buy,” according to MarketWatch data. The average target price of $112.44 per share implies around 300% upside from Wednesday’s close.
Boost Run
Boost Run, with a market capitalization of $704 million, is a provider of scalable cloud infrastructure for enterprise AI and high-performance computing. It rents GPU and CPU computing capacity and data storage to clients, while also providing managed Kubernetes services. The company lists Nvidia and Dell Technologies among its clients.
Boost Run operates six data centers in the U.S. and plans to bring three more online soon, it stated in its second-quarter 2026 earnings release. It reported revenue growth of 270% year over year to $31.1 million.
This small cap is also a market newcomer, having gone public in May through a merger with special purpose acquisition company Willow Lane. The stock closed its first trading session, on May 11, at $21 per share and has since fallen almost 60%. Wall Street nevertheless remains upbeat. The name has five analyst ratings, all “buy,” according to MarketWatch data. The average target price of $42.20 per share implies 402% upside from the last close.
ProPetro Holding
ProPetro, with a market capitalization of just over $939 million, provides services to oil and gas companies ranging from hydraulic fracturing to power supply. In late 2024, it established ProPWR, a division that provides mobile natural gas-fired power generation for data centers, oil and gas companies, and industrial customers without a grid connection.
Second-quarter revenue fell 6.2% year over year to $305.8 million. The net loss widened 13.4% to $8.1 million, while the loss per share was unchanged at $0.07.
ProPetro stock has gained almost 21% in the last 12 months but is down almost 20% year to date. Seven Wall Street analysts recommend buying shares, while another five rate it “hold.” The average target price is $15.30 per share, twice Wednesday’s closing price.
This text is for informational purposes only and does not constitute personalized investment advice.