Tesla and Meta Earnings Reports, PMI Data in the U.S. and Europe: What Investors Can Expect This Week
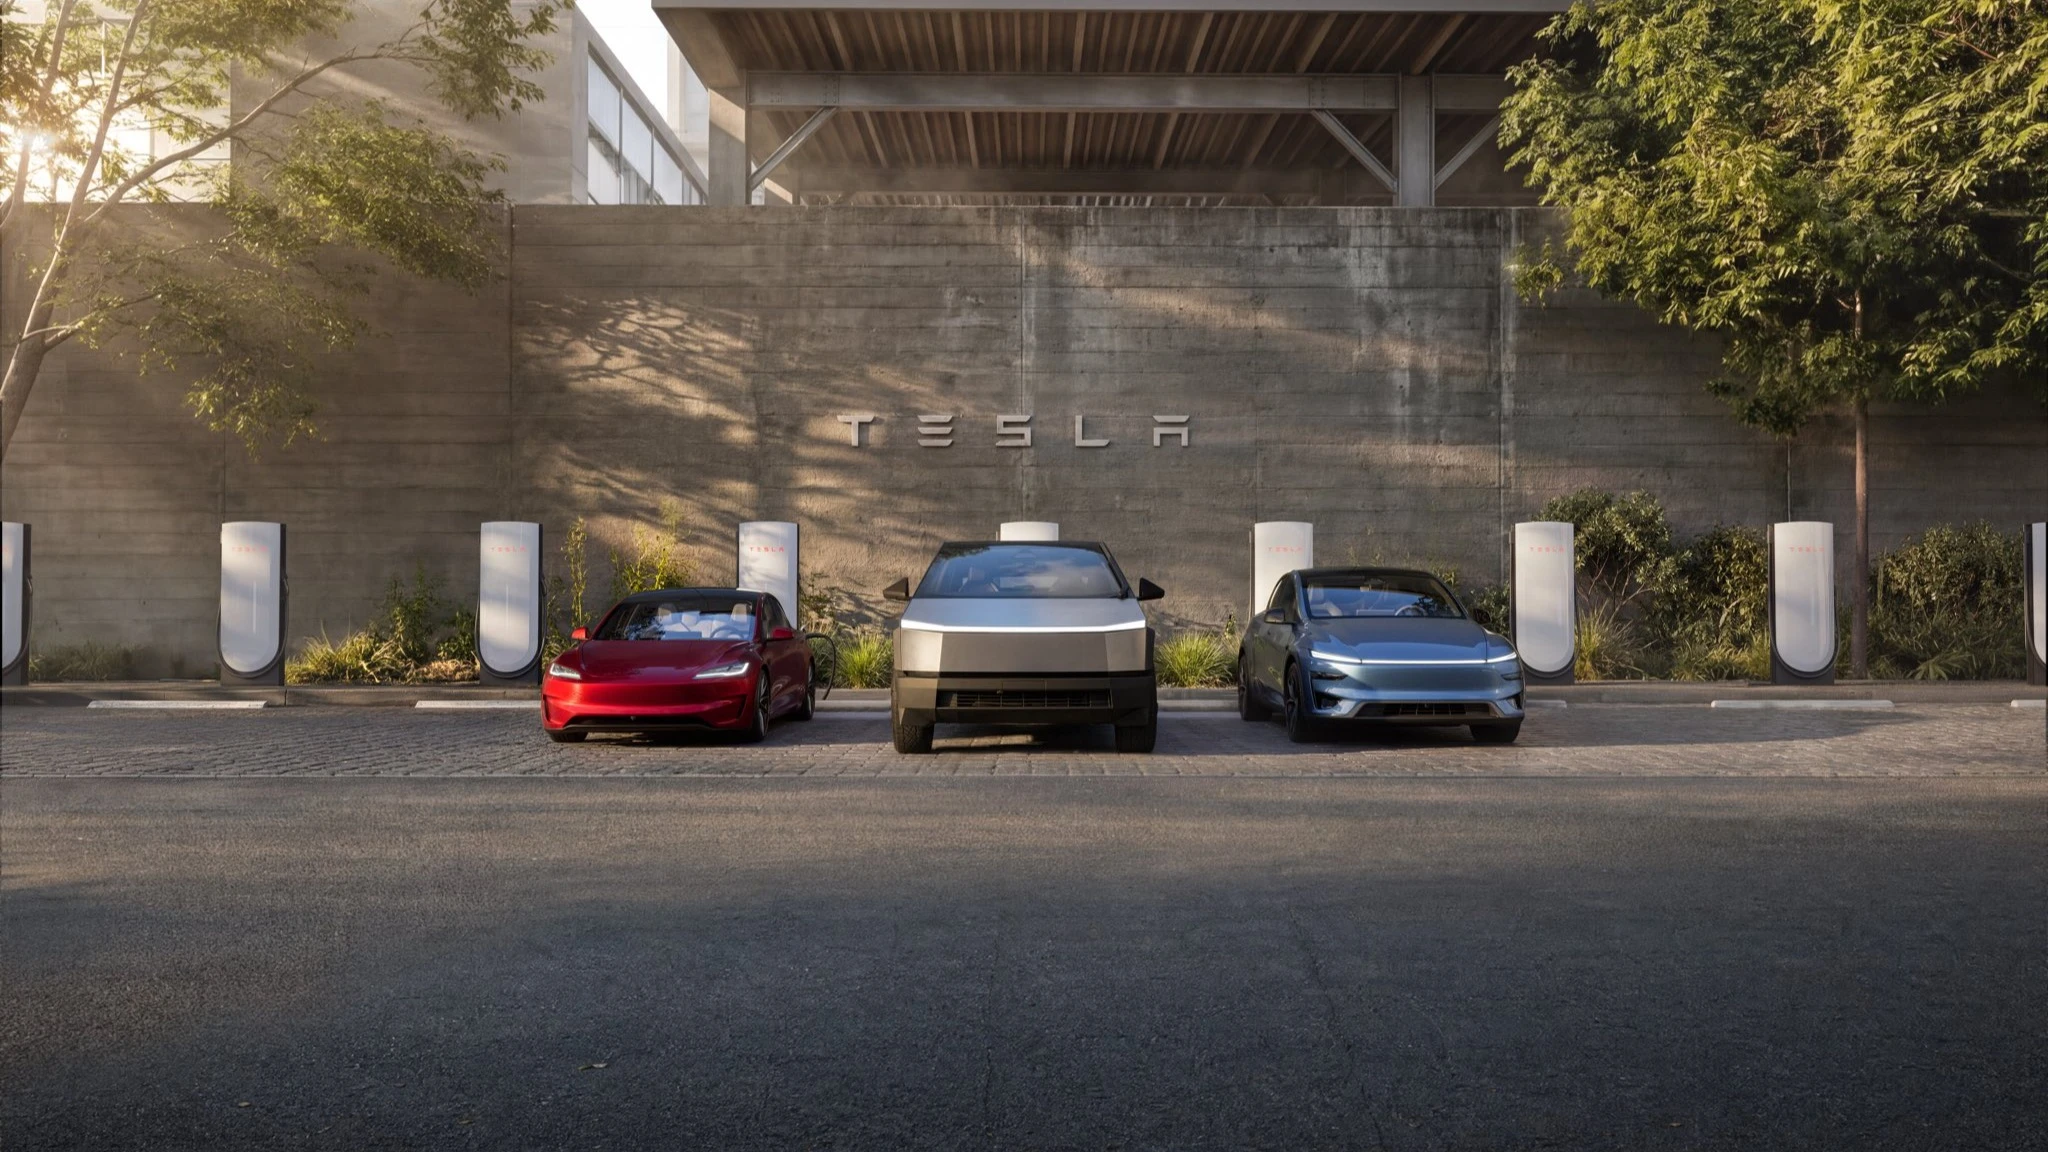
Tesla will release its quarterly report on October 21 / Photo: X/Tesla
The main focus of the week on the U.S. stock market will be earnings reports from technology companies amid volatile trading in AI stocks, according to Reuters. Meta, Tesla, and semiconductor companies Lam Research and Texas Instruments will report their quarterly results. The reports from the latter two may provide insight into the state of demand in the chip market.
Meta is of particular interest, as it is spending enormous sums on building data centers for artificial intelligence. “One of the key takeaways from this earnings season will be whether the profitability of the largest cloud companies can grow faster than their capital expenditures,” said Kevin Shi, a senior analyst at BNY Wealth. Other major companies reporting this week include Netflix, GE Aerospace, and Procter & Gamble.
On the macroeconomic front, key developments will include data on business activity in the U.S. and Europe, according to The Wall Street Journal. The October PMI indices will reflect the state of the manufacturing and services sectors and provide investors with new guidance regarding central banks’ future interest rate decisions. In Asia, key events will include data on China’s economic growth and the announcement of China’s benchmark lending rate.
ING interest rate strategist Padraic Garvey expects bond yields to rise further. “Market participants are taking into account that jobless claims were low again, retail sales were strong, and producer price inflation was unwelcome high. The market will likely use this as a basis for a further rise in yields in the coming weeks,” he said.
On Monday, October 19, the National Bureau of Statistics of the People’s Republic of China released the country’s third-quarter GDP figures. The world’s second-largest economy grew by 4.5% year-over-year, following 4.3% growth in the second quarter, when growth rates were at their lowest in three years. The result exceeded market expectations (4.4%). Growth was supported by recent economic policy easing and steady exports, primarily of AI components, high-tech products, and electric vehicles, according to Trading Economics.
In September, growth in industrial production and retail sales in China accelerated to a six-month high, partly due to the “Golden Week” holiday period. In the first nine months, the economy grew by 4.6% compared with the same period last year. This is in line with the lower end of the government’s target growth range for 2026—4.5–5%.
On Tuesday, October 20, the U.S. Census Bureau will release data on new housing starts for September, and the National Association of Realtors will release statistics on pending home sales in the United States for the same month, according to Barron’s.
The People's Bank of China will announce its one-year benchmark lending rate. Economists at DBS expect it to remain unchanged: according to their forecast, the authorities will support economic growth primarily through targeted fiscal measures rather than further rate cuts, the WSJ reports.
SpaceX, GE Aerospace, General Motors, Netflix, Northrop Grumman, RTX, and United Airlines Holdings will report their quarterly results.
On Wednesday, October 21, Tesla and Meta Platforms will report their earnings. Meta’s results will allow investors to assess how the company’s massive spending on AI infrastructure aligns with its financial performance. On the same day, Lam Research and Texas Instruments will also report earnings; according to Reuters, their results may provide a broader picture of demand in the semiconductor industry.
AT&T, IBM, Philip Morris International, SAP, and Southwest Airlines will also report their quarterly results.
On Thursday, October 22, the U.S. will release its weekly data on the number of unemployment insurance claims.
The Central Bank of Turkey will announce its decision on the interest rate. Annual inflation in the country slowed from 31.5% in August to 29.7% in September, which increases the likelihood of a rate cut as early as October, the WSJ notes.
Deckers Outdoor, Honeywell International, Lockheed Martin, Nasdaq, Newmont, Procter & Gamble, Spotify Technology, and Western Digital will report their quarterly results.
On Friday, October 23, S&P Global will release preliminary business activity indices for the U.S. manufacturing and services sectors for October. These figures will indicate how resilient the U.S. economy remains following recent data showing higher-than-expected inflation. On the same day, the final reading of the October consumer sentiment index for the world’s largest economy will be released.
Preliminary October PMI indices for manufacturing and services in France, Germany, and the eurozone will be released in Europe. LBBW analysts expect a slight deterioration in the figures following several months of improving business sentiment. “Given the rise in optimism over the past few months, we expect a slight decline in the [eurozone PMI]. This, in and of itself, could provide a little more support for the recent bond-friendly trend,” they say.
American Express and SLB will report their quarterly results.
This article was AI-translated and verified by a human editor