Freedom initiates on Jennifer Garner's Once Upon a Farm at TP offering 50% upside
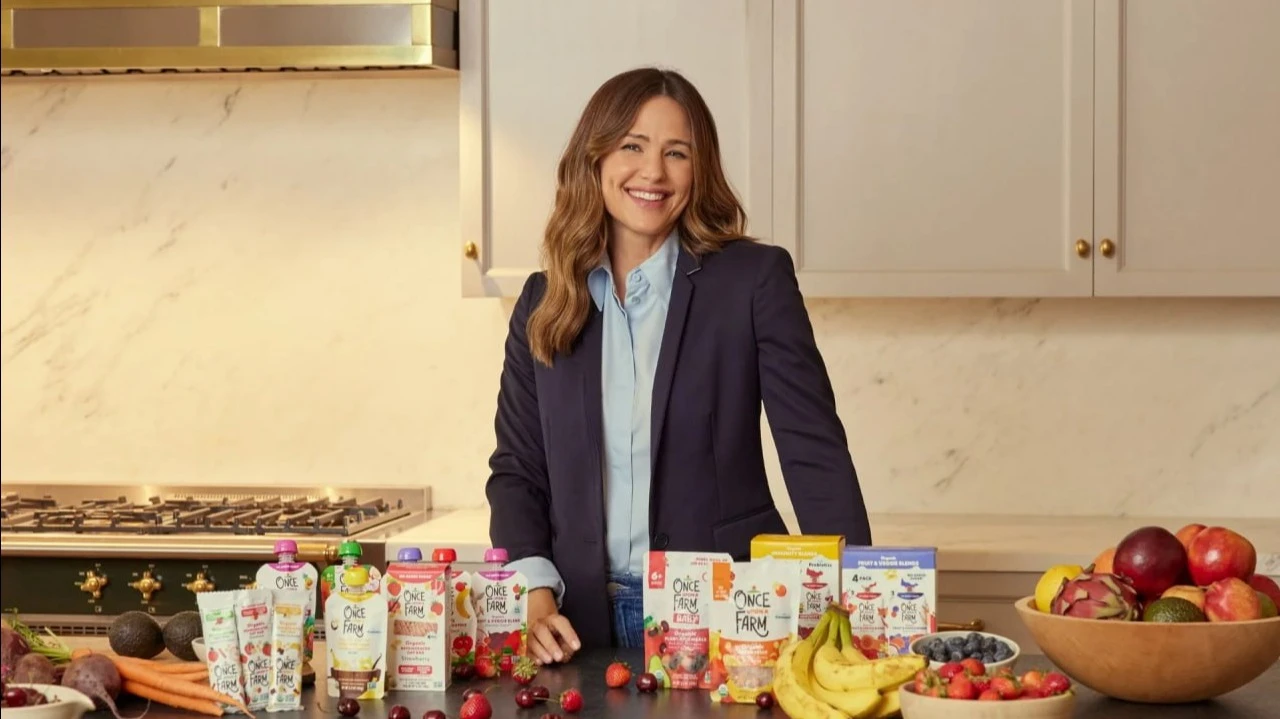
Freedom has started its coverage with a "buy" rating / Photo: Once Upon a Farm
Once Upon a Farm, a small-cap maker of organic baby food and snacks for children cofounded by actress Jennifer Garner, is worth 50% more than its current stock price, Freedom Broker argues in a coverage initiation report. The house believes that wider distribution and an expanded product lineup should drive sales growth, leading to better margins.
Details
Freedom Broker has initiated coverage on Once Upon a Farm. In a report seen by Oninvest, it assigned the stock a “buy” rating at a target price of $25.50 per share, implying 50.5% upside from the Friday close. Freedom reckons that the current stock price does not reflect Once Upon a Farm’s sales growth potential or its expected margin expansion after 2026.
Freedom's rationale
Wider distribution is one of Once Upon a Farm’s main growth drivers, according to the initiation report. At the end of the second quarter, the company had around 4,100 branded coolers in retail stores.
The company began experimenting with cooler installations in the late 2010s but encountered several challenges and failed to achieve the desired results, chief marketing officer Katie Marston said. Some products were stocked in the dairy aisle, while others sat among numerous baby food brands, which made them harder to spot on shelves. The company’s site states that its products can be found in six different sections, depending on the store.
Once Upon a Farm’s coolers are now located in baby food aisles, “getting the customer into our brand” earlier, executives said on the company’s second-quarter earnings call. For that quarter, the company reported net sales growth of 42.3% year over year to $85.4 million. The company is also said to have found the right product assortment for its coolers this year, meaning “we're seeing the productivity growth in the coolers themselves,” executives said.
Once Upon a Farm plans to increase the number of installed coolers to 5,000 by the end of this year and 8,000 in 2027. Freedom believes the total could reach around 14,600 by the 2030s.
Another growth driver cited by Freedom is an increasing share of baby products in the company’s net sales. This means more families will start buying Once Upon a Farm products earlier, from infancy, allowing the company to retain them as customers until their children finish school. Freedom also expects earnings growth to outpace sales growth after 2026 as costs decline and a club-store sales promotion ends, as that weighed on the gross margin in the second quarter.
Among the risks to the business, Freedom cites lower sales per cooler, failures to meet food safety requirements, and operating efficiency falling short of its expectations.
What other analysts say
Once Upon a Farm completed an IPO on the New York Stock Exchange in February. Its stock is off 19% since then. However, Wall Street remains generally upbeat on the name: according to MarketWatch data, it has six “buy” calls versus four “hold” ratings. The average target price of $25.20 per share implies 49% upside from the last close.