Morning in New York: A Relatively Moderate Rate Hike by the Fed — A Positive Outcome
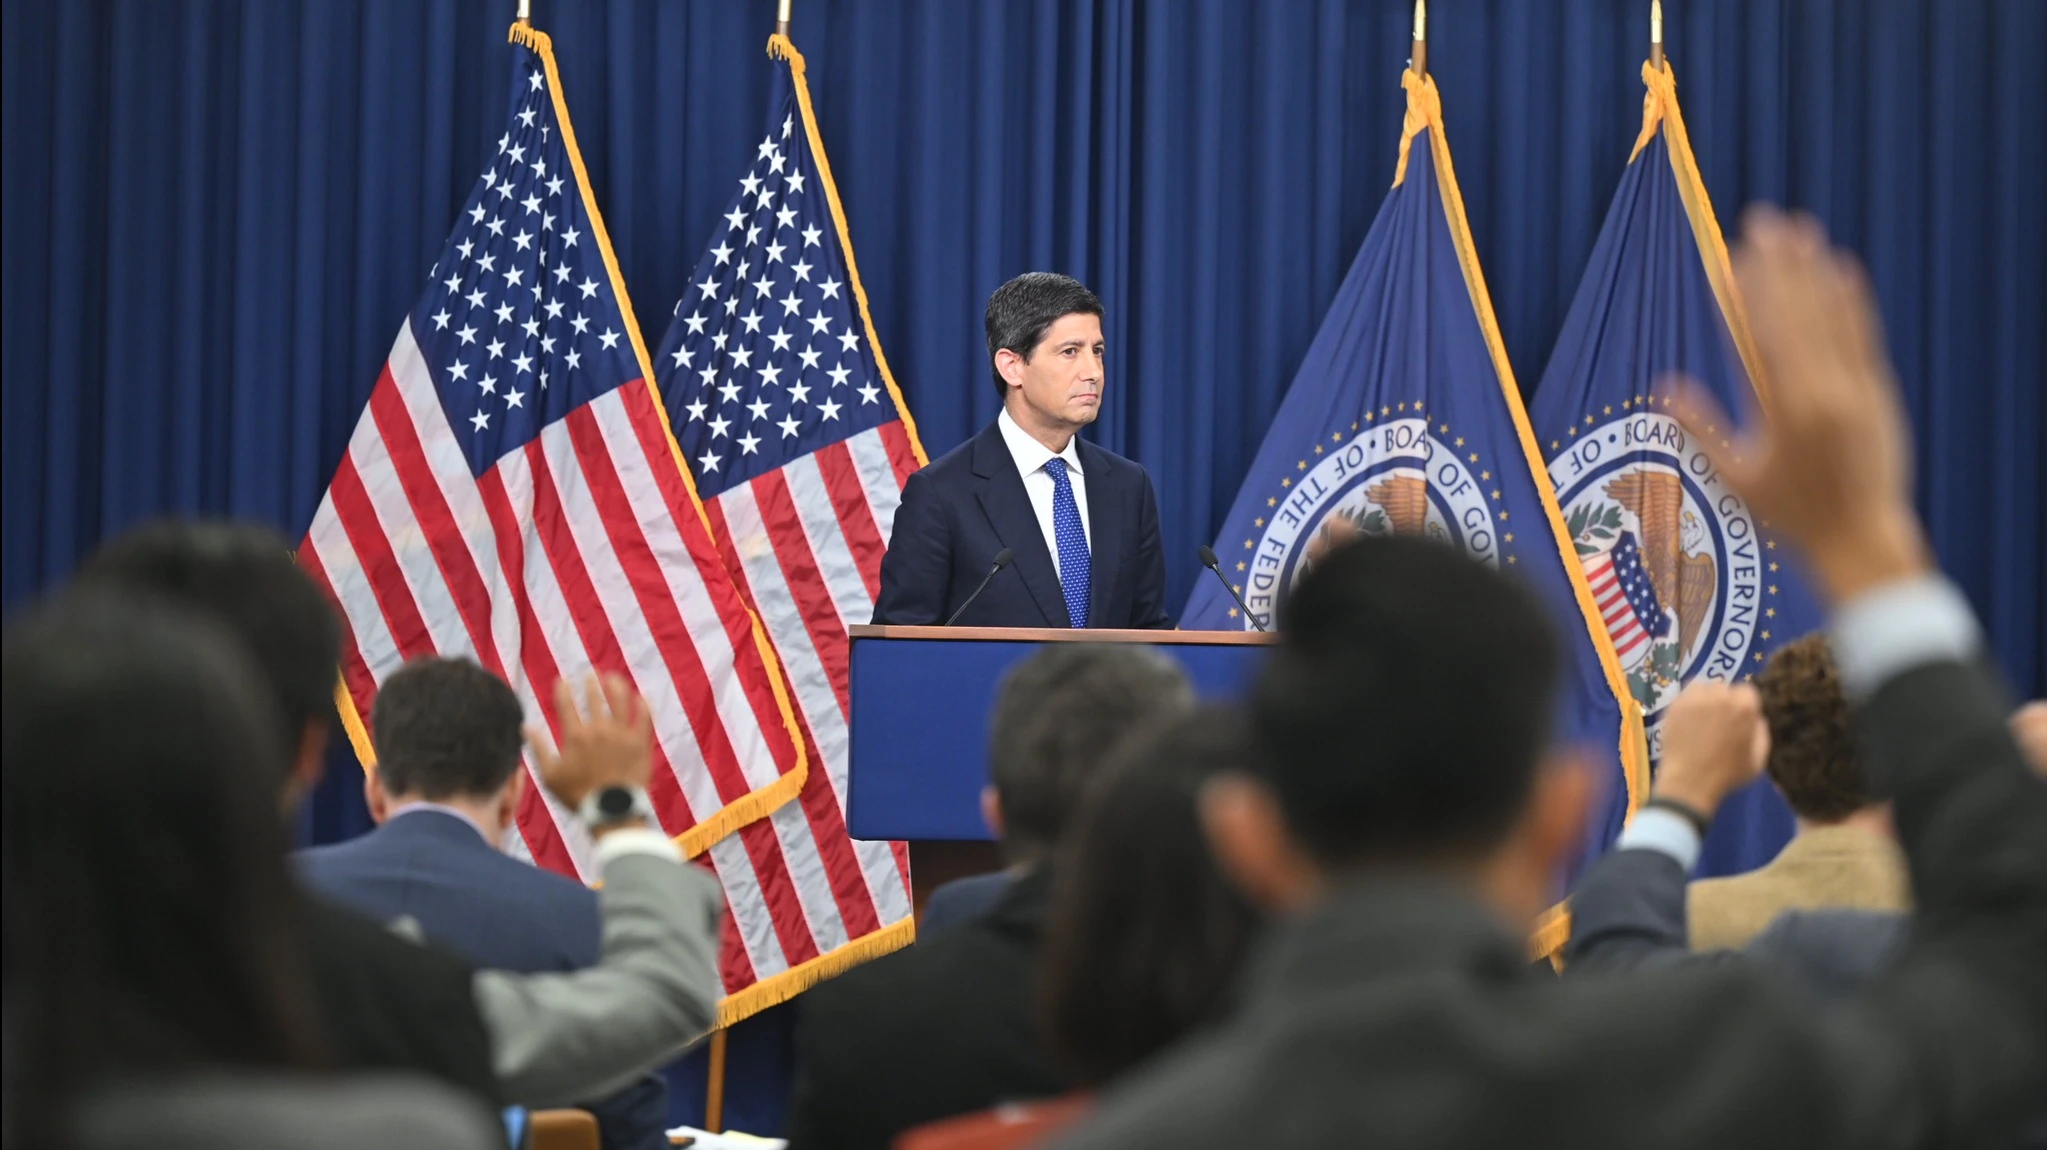
The Federal Reserve, under Kevin Warsh's leadership for the first time, raised interest rates / Photo: Flickr/Federalreserve
A daily overview and forecast of events in the U.S. stock market by Mikhail Denislamov, Deputy Director of Capital Markets Research at Freedom Broker.
We expect
The Fed raised rates by 25 basis points yesterday, but given current market expectations, the decision can be considered moderately dovish. The median dot plot suggests only one more hike through the end of 2026, followed by rates remaining unchanged in 2027, whereas the futures curve currently prices in a significantly tighter scenario: another hike is almost fully priced in by December, a second one is largely priced in by January, and by mid-2027, the market expects the rate to be in the 4.50–4.75% range, roughly 50 basis points above the Fed’s trajectory. In other words, the regulator confirmed the need for tightening but has not yet endorsed expectations of a full-fledged cycle involving multiple hikes. At the same time, the long end of the yield curve did not send any new warning signals: yields on 30-year Treasuries barely reacted, while those on 10-year Treasuries stabilized around 5%, despite the rise in short-term rates.
This setup sets the stage for a stock market rebound on Thursday, September 17, provided that long-term yields remain stable. After several sessions of rate-driven pressure and a sell-off in the AI sector, investors may once again shift their focus to corporate earnings growth and the continued strong demand for computing infrastructure. The most favorable scenario for the S&P 500 and Nasdaq is for the 10-year yield to remain around 5% or decline: in this case, the market will be able to interpret the rate hike as a stress test that has already been passed and begin to reduce the premium for further tightening.
The political tension surrounding the Fed has eased: Donald Trump, who had previously called for rate cuts on multiple occasions, stated after the Fed’s decision that he retains confidence in Kevin Warsh and wants him to act independently, noting that the Fed chair “can do whatever he thinks is necessary”.
At 8:30 a.m. Eastern Time (ET), initial jobless claims will be released, data on new home starts for August and the Philadelphia Fed’s September manufacturing activity index, and at 10:00 a.m. ET—pending home sales figures.
The outlook in the commodities market has improved slightly: WTI crude fell below $102 per barrel today following yesterday’s 3% drop on reports of a gradual restoration of capacity at Saudi Arabia’s East-West pipeline, and talks between Trump and Gulf leaders are scheduled for next week. The stabilization of the oil market is allowing investors to once again increase their risk appetite in the stock market.
S&P 500 futures are trading higher. We assess the risk balance for the upcoming session as positive, with elevated volatility. Strong retail sales confirm the resilience of consumer spending and corporate earnings, while the unanimous decision and Warsh’s hawkish stance on inflation bolster confidence in the regulator. The behavior of yields at the long end of the curve will be a key factor in the revaluation of multiples.
What to Watch for in the Pre-Market
— Generac (GNRC) shares soared by more than 30% following the signing of a major agreement with Amazon (AMZN) to supply backup generators. The first shipments in 2027–2028 are estimated at $2.4 billion, and Amazon’s total payments could potentially reach $8 billion; Amazon also received warrants to purchase up to 1.69 million Generac shares at $200.93 per share. The deal significantly improves Generac’s revenue outlook.
— Lennar (LEN) fell by about 2–3% following earnings that fell short of expectations: adjusted earnings came in at $1.23 per share versus the consensus estimate of $1.29, revenue was $8.05 billion versus $8.37 billion, and new orders fell 9% year-over-year. The company lowered its full-year home delivery forecast to 80,000–81,000 from 82,000–83,000, citing a further deterioration in market conditions. The results confirm that mortgage rates of around 7% continue to limit housing affordability.
— Fluence Energy (FLNC) shares plummeted 17% following a downward revision of its revenue forecast for fiscal year 2026, announced concurrently with the appointment of a new chief operating officer. Market participants viewed the coincidence of the guidance revision and the personnel change as a sign of deep-seated operational problems, rather than a one-time disruption in the delivery schedule for energy storage units.
— Nebius (NBIS) is up more than 6% following its decision to raise prices for renting computing power based on Nvidia accelerators starting October 1: H100 prices will increase by 17%, H200 by 20%, B200 by 19%, and B300 by 21%. Against this backdrop, CoreWeave (CRWV) rose by approximately 3–4%. The rate hike—even for previous-generation accelerators—points to a persistent shortage of computing power and reinforces expectations of improved business fundamentals for cloud-based AI infrastructure providers. This news is particularly significant following the sector’s recent sell-off due to concerns about a potential slowdown in the development of cutting-edge AI models: actual price trends so far indicate that demand for computing power remains high.
— Vicor (VICR) shares jumped 11% on news that the company had licensed its proprietary Vertical Power Delivery (VPD) technology to one of the leading manufacturers of AI equipment. The deal confirms the demand for the company’s innovations in the accelerator power supply segment, where power density has become a bottleneck for data centers, and, in our view, opens up a royalty-based monetization model for the company.
The Market on the Eve of...
Trading on September 16 on U.S. stock exchanges ended with losses. The S&P 500 lost 0.44%, the Nasdaq 100 closed virtually unchanged (−0.01%), the Dow Jones fell 1.21%, and the Russell 2000 dropped 0.40%.
The trend was driven by the Federal Open Market Committee (FOMC) meeting: the rate was raised unanimously. The yield on 10-year Treasury bonds, which had fallen to 4.94% in the morning, rose to 5.02% following Warsh’s press conference, 2-year notes hit their highest level since mid-2024, and the dollar index gained 0.6%. Defensive and technology sectors appeared more resilient than others: the IT sector (XLK) gained 0.10%, health care (XLV) rose 0.04%, utilities (XLU) rose 0.01%, and industrials (XLI) posted only nominal losses (−0.12%). The energy sector (XLE: −2.97%) lagged behind amid a 3.2% drop in WTI, as did the financial sector (XLF: −1.62%), where regional banks and mortgage companies saw the heaviest selling. Materials (XLB: −0.73%) and real estate (XLRE: −0.67%) also underperformed the market amid rising interest rates.
The pressure on the broad market index was concentrated among the heavyweights. Microsoft (MSFT: −1.37%) made the largest negative contribution, dragging the S&P 500 down by about 8 basis points. Oil majors ExxonMobil (XOM: −3.54%) and Chevron (CVX: −2.86%) together cost the index 6 basis points, confirming that the sell-off in the energy sector was widespread. Amazon (AMZN: −0.99%) contributed another 4 basis points to the decline.
Goldman Sachs exacerbated the negative sentiment in the banking sector (GS: −4%), which highlighted weakness in its fixed-income, currencies, and commodities (FICC) segment and rising non-compensation expenses during a conference call. In the transportation sector, J.B. Hunt (JBHT: −13.3%) warned of a decline in earnings per share (EPS) due to a surge in expenses related to drivers, fuel, and insurance claims.
Semiconductors and AI infrastructure provided support for the index. Nvidia (NVDA: +0.82%) contributed about 6 basis points to the S&P 500, Intel (INTC: +4.03%) contributed 3 basis points following a Reuters report on a possible memory chip shipment to SK Hynix, while AMD (+1.65%), Apple (AAPL: +0.32%), and GE Vernova (GEV: +4.79%), which expects to exceed its 20 GW target for gas contracts.
Macroeconomic data reinforced the regulator’s confidence. Retail sales in August rose 1.2% month-over-month, beating the consensus estimate of 0.8% and following a 0.5% decline in July, while the control group gained 1.4% against expectations of 0.4%. In contrast, the NAHB Housing Market Index lost three points and fell to a one-year low.
The session’s results lead to three conclusions. First, the market absorbed the first rate hike in three years without panic (the VIX closed below 18 points), although stock indices fell to their lowest levels since July: the impact was concentrated among financial companies sensitive to funding costs. Second, the AI sector has proven resilient to policy tightening: amid a broad market decline, chipmakers and power equipment manufacturers remained in demand, while the IT sector posted the strongest performance among all sectors. Third, the combination of strong consumer spending and a hawkish Fed shifts the risks toward further yield increases, leaving real estate and homebuilders the most vulnerable.
This article was AI-translated and verified by a human editor