Bill Eckman called Anthropic the story of the century. Why did he decide not to buy the stock?
The head of Pershing Square considers the bet on Anthropic to be more speculative than the one on Visa
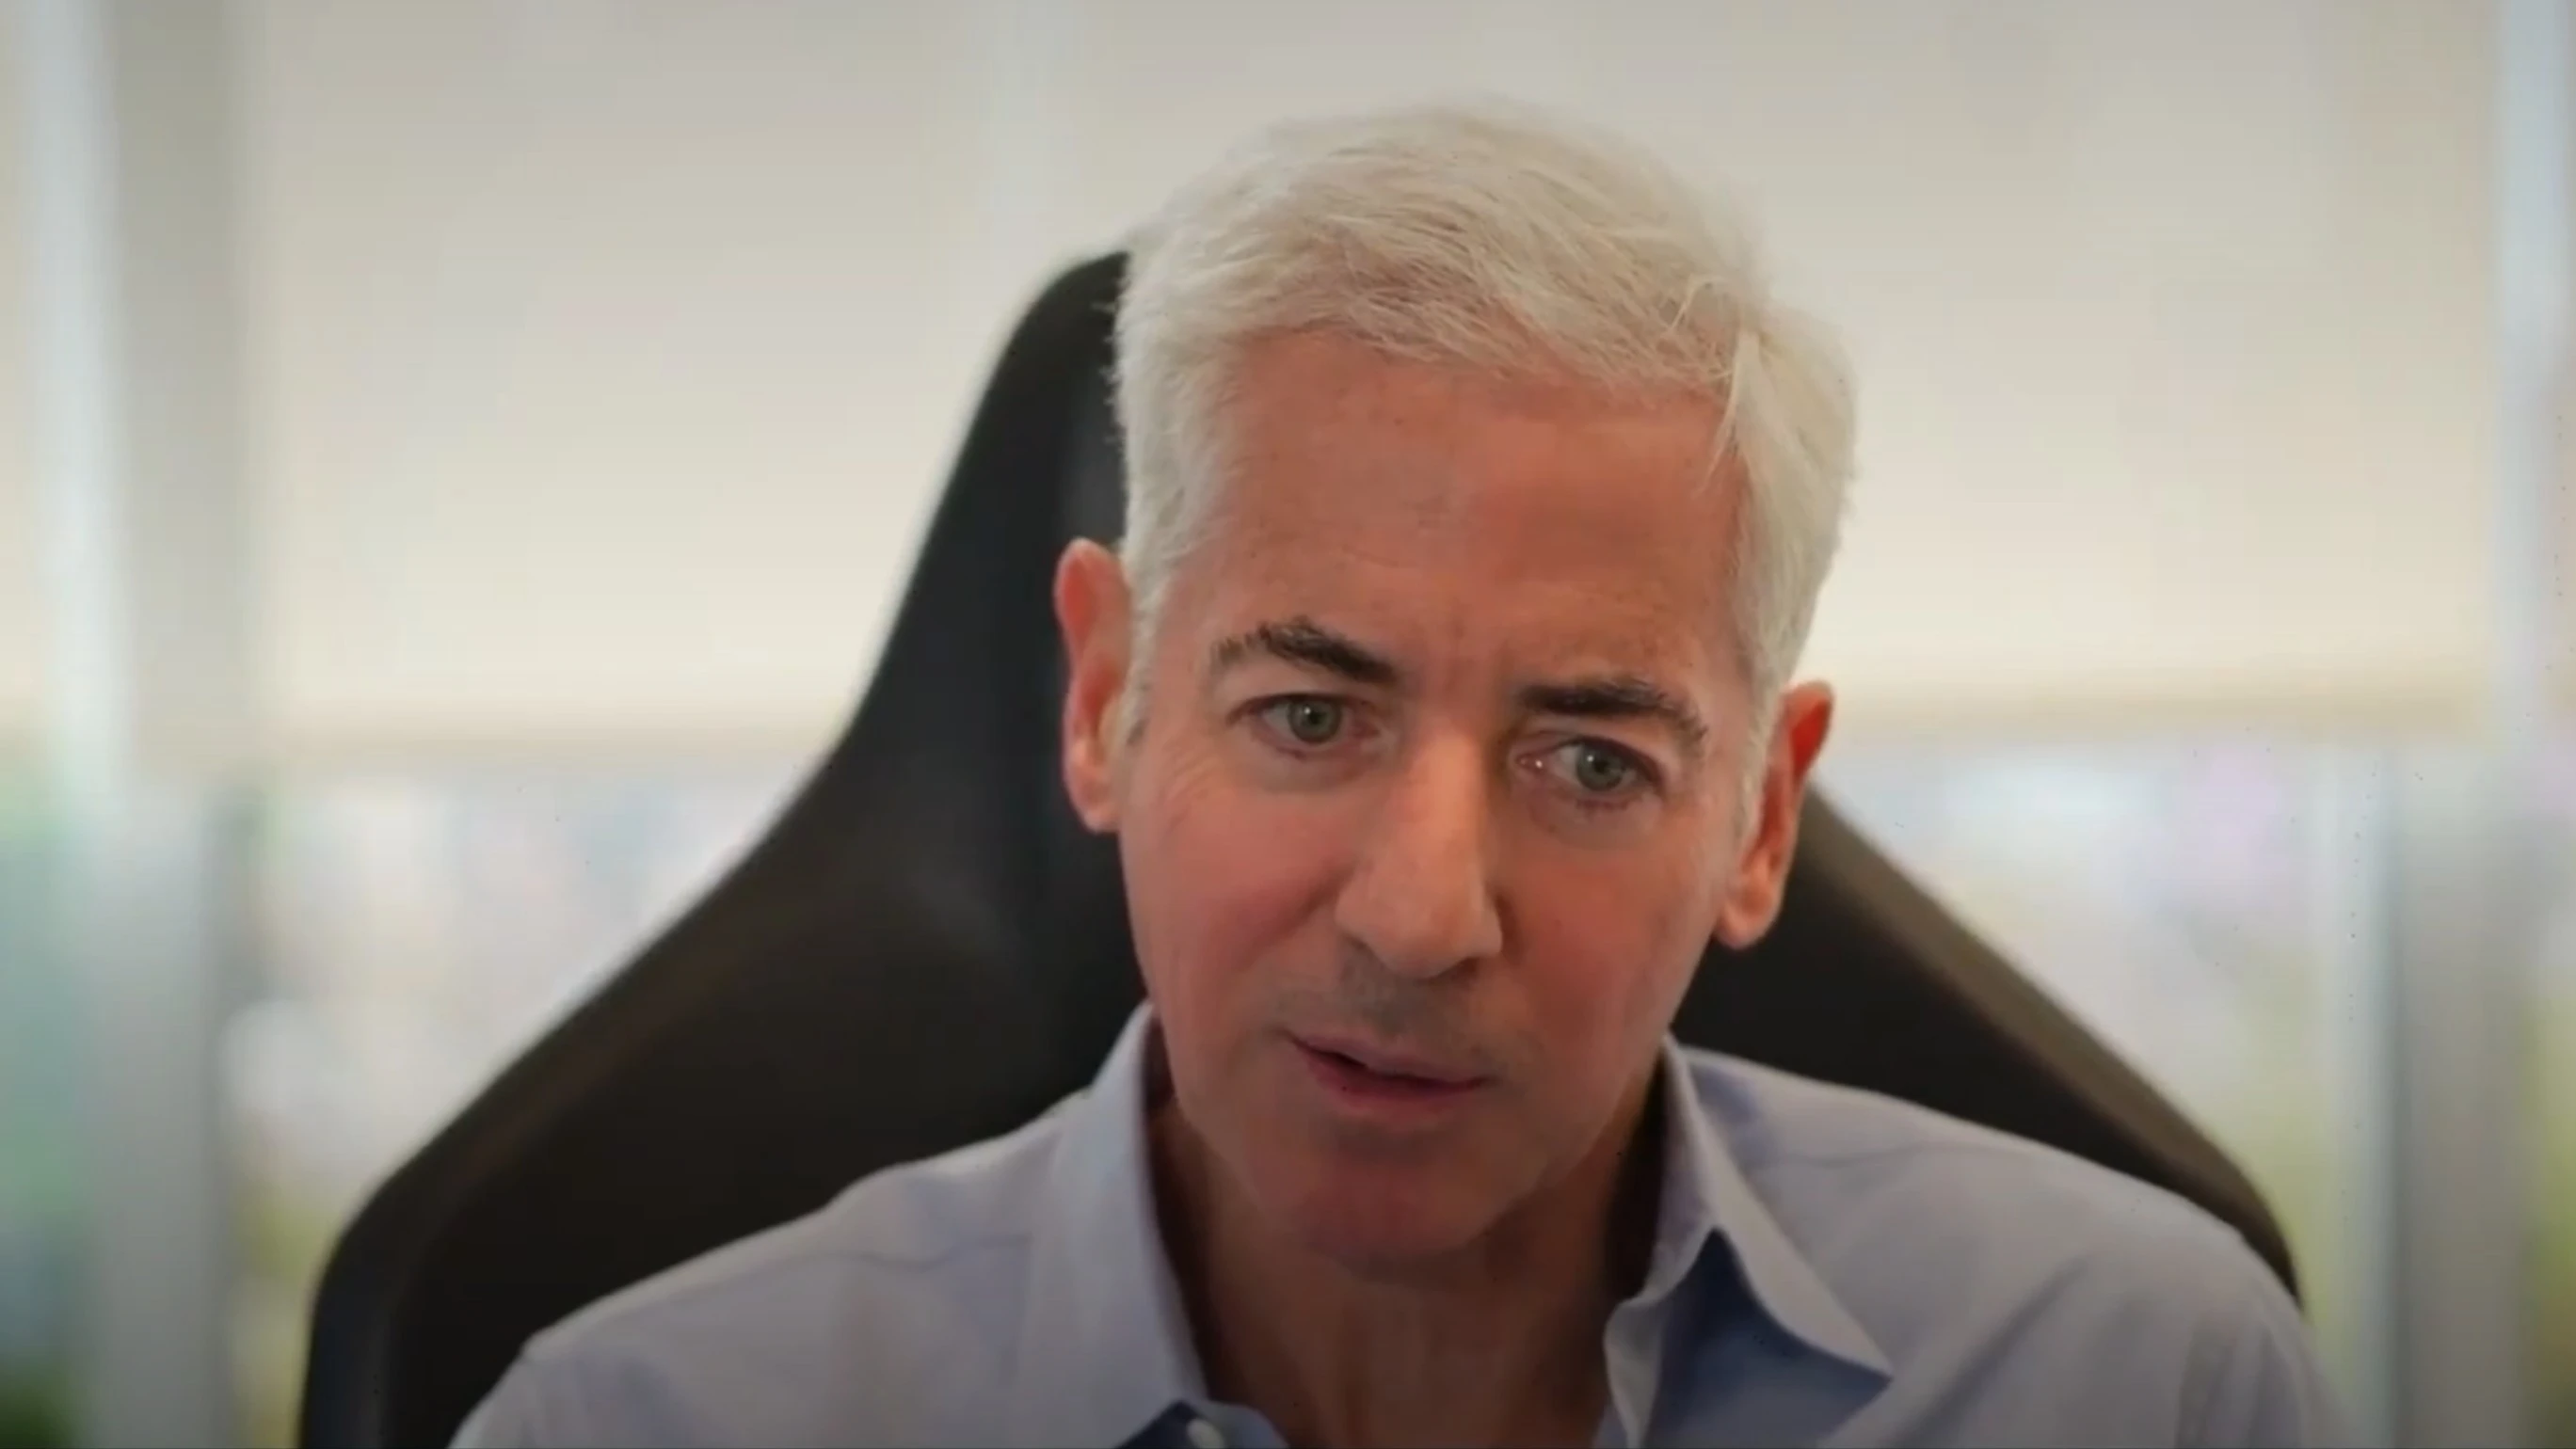
Billionaire investor Bill Eckman believes that forecasting Anthropic's cash flows is much more difficult than forecasting those of traditional companies / Photo: Screenshot from Bill Eckman's video interview on Yahoo Finance
Billionaire Bill Eckman, who heads the asset management firm Pershing Square Capital, called Anthropic, the creator of the Claude chatbot, “perhaps the most remarkable business story of this century.” However, he does not plan to buy Anthropic shares immediately after the company goes public, according to Yahoo Finance, which interviewed the billionaire.
Pershing Square considers itself “very low-risk investors” and wants to invest in businesses whose growth can be predicted “with a very high degree of certainty,” Ekman said. Anthropic, he said, “could be worth much more or much less depending on several variables that are difficult to predict.” “That’s why it doesn’t fit into our portfolio,” Ekman concluded.
Ekman considers the investment in Anthropic to be “more speculative” than, for example, the holdings in Visa securities that his company owns. He cited shares of the mortgage agencies Fannie Mae and Freddie Mac—which investors have “completely written off” this year—as his favorite position in terms of risk-return ratio. Pershing Square has held these securities for 13 years and expects to profit when the agencies eventually emerge from conservatorship and return to private ownership.
The Mystery of Cash Flows
A Yahoo Finance reporter pointed out that Anthropic is losing billions of dollars, has negative free cash flow (it spends more than it earns), and may be forced to raise more money. He asked how one should even value such a business. Ekman replied that Anthropic is actually close to “true operational profitability” or may have already achieved it. According to the prospectus, the company’s net loss for the nine months ending September 30 did indeed amount to $104 billion. But CNBC noted that this was primarily made up of paper losses from the revaluation of the fair value of convertible bonds and derivative liabilities.
The problem, according to Ekman, lies elsewhere: if Anthropic fails to maintain its leadership position, “real questions” will arise about the company’s business model. Therefore, he says, it has no choice but to make capital expenditures in order to retain its lead. Like any company, Anthropic can be valued using a future cash flow model, but building such a model is “much more complicated” than for a hypothetical manufacturer whose sales grow steadily by 5% each year, noted the head of Pershing Square. The range of possible development scenarios for Anthropic is much broader than that of such a manufacturer, he added.
An IPO valued at $1.4 trillion
Anthropic is set to set its offering price on November 18, and its shares will begin trading on the Nasdaq under the ticker symbol ANT on November 19. With a price range of $70–78 per share, the company’s market capitalization, on a fully diluted basis, is estimated at $1.4 trillion. Pre-market trading in Anthropic shares for Freedom clients began on November 12.
Due to overwhelming investor demand, the lead underwriters plan to price the offering above the upper end of the range, the Financial Times reported this week. Morningstar analysts estimate Anthropic’s fair value at $1.7 trillion, while traders on over-the-counter markets are entering into futures contracts at $98 per share.
This article was AI-translated and verified by a human editor