Morning in New York: The rally will face a test from inflation
Core inflation at or below the forecast level could reduce expectations of tighter monetary policy by the end of the year, which would support growth stocks / Photo: StockMediaSeller / Shutterstock.com
A daily review and forecast of events in the U.S. stock market by Mikhail Denislamov, Deputy Director of Capital Markets Research at Freedom Broker.
We expect
The main event of the day will be the release of the Consumer Price Index (CPI) data for October (consensus estimates: 0.2% MoM for the core index and 0.3% for the overall index; September: 0.3% and 0.6%, respectively). The market estimates the probability of a Fed rate hike in December at approximately 80%, forecasting a 43-basis-point increase by the end of 2027. Core inflation at 0.2% or lower could reduce the probability of monetary tightening through the end of 2026, which would support growth stocks. If, however, core CPI comes in at 0.3% or higher, this could lead to higher Treasury yields and renewed pressure on stocks. The Bureau of Labor Statistics is unlikely to release year-over-year inflation data (September: 3.7%) due to the omission of the October 2025 release.
The U.S. Treasury will issue $42 billion in 10-year notes. Market participants are closely monitoring trends in demand for long-term Treasury bonds.
Remarks will be delivered by Federal Reserve Board member Christopher Waller, Vice Chair for Supervision Michelle Bowman, and the presidents of the Federal Reserve Banks of Dallas, Kansas City, and Philadelphia—Laurie Logan, Jeff Schmid, and Anna Paulson. At 6:00 a.m. Eastern Time (ET), the NFIB Small Business Index for October will be released (consensus: 97.7 points; September: 97.9). This release will be of secondary importance.
According to unconfirmed reports from Al Arabiya, the U.S. has allowed Iran to enrich uranium up to 3.67%, and Tehran has agreed to this proposal. Donald Trump did not disclose the results of his meeting with the Prime Minister of Qatar, but confirmed his readiness to resume strikes against the Islamic Republic. Secretary of State Marco Rubio called Iran’s conditions unreasonable. According to the FT, the Saudi East-West oil pipeline caught fire following the attack. During the Asia-Pacific trading session, WTI prices fell below $86 per barrel, which is easing inflation expectations and supporting stocks. However, until a resolution to the U.S.-Iran conflict is confirmed, the risk of a reversal remains.
Starting November 10, China extended the suspension of the 24% additional tariff on U.S. goods for two months, maintaining the 10% rate. In our view, despite the brevity of this pause, it eliminates the risk of an escalation in the trade conflict through the end of the year.
The uncertainty surrounding Anthropic’s valuation is drawing increased investor attention to the cost of financing in the AI industry. The company withdrew its preliminary IPO filing, which had proposed the sale of approximately 867 million shares at $70–80 each to raise up to $69.3 billion, citing errors in the offering terms and its intention to submit updated terms.
Before the market opens, TransDigm (TDG), Honda Motor (HMC), Gilat Satellite Networks (GILT), and Aviat Networks (AVNW) will report earnings before the market opens, while CoreWeave (CRWV), Rigetti Computing (RGTI), Satellogic (SATL), and Lightwave Logic (LWLG) will report after the market closes.
S&P 500 futures are trading in neutral territory. We assess the risk balance as neutral amid heightened volatility. Buyers are supported by falling oil prices, a broad market recovery, the peak buyback season, and seasonal factors. Sentiment is being weighed down by expectations of a rate hike in December, as well as the positioning of systematic funds, which points to selling. Key factors will include the core CPI and the reaction of Treasury yields to it.
What to Watch for in the Pre-Market
• Sanmina (SANM) shares jumped 20% following the release of its quarterly earnings report. The company’s revenue rose 84% year-over-year to $3.86 billion, beating the consensus estimate of $3.48–3.55 billion, with adjusted EPS of $4.43. Revenue from communications networks, as well as the AI and cloud infrastructure segments, increased by 179% year-over-year to $2.37 billion. The forecast for the current quarter calls for revenue in the range of $3.8–4.1 billion, with EPS in the range of $3.50–3.85. The full-year guidance sets the revenue range at $17.5–19.5 billion. The earnings release confirms demand for AI infrastructure.
• Take-Two Interactive (TTWO) shares rose 4% following the release of its second-quarter financial results. Net bookings for the quarter fell 18% year-over-year to $1.6 billion, compared with the company’s own forecast of $1.62–1.67 billion. The guidance for pre-orders in fiscal year 2027 and the third quarter was reaffirmed at $8–8.2 billion and $3.35–3.5 billion, respectively. GTA VI is set to launch on November 19, and pre-orders for the game are significantly exceeding initial expectations. We believe the weak earnings report has taken a back seat ahead of the flagship game’s release.
• Onto Innovation (ONTO) shares rose 8% in response to its third-quarter earnings report. Revenue increased 88% year-over-year to a record $410 million, beating the consensus estimate of about $392 million, while adjusted EPS came in at $2.44, compared to average estimates of $2.30–2.31. The company raised its fourth-quarter revenue guidance to $430–450 million.
• Rocket Lab (RKLB) shares fell 6% following the release of its third-quarter results. Revenue rose 73% year-over-year to $268 million, compared with a consensus estimate of $255.7–257.2 million, while the loss per share of $0.12 significantly exceeded expectations of $0.06–0.07. The order backlog increased by 52% quarter-over-quarter to $3.57 billion. The negative reaction is attributed to the high loss and uncertainty surrounding the commercialization timeline for the Neutron rocket, whose first launch is not expected until 2027 at the earliest.
• Steel Dynamics (STLD) shares rose 8% following the expansion of its share buyback program to $3 billion (~9% of market capitalization). Under the previous program, $216 million remained as of the end of September. The quarterly dividend will be $0.53 per share.
The Market on the Eve of...
Trading on U.S. stock markets on November 9 ended in positive territory. The S&P 500 gained 2.35% (its best performance since March), the Nasdaq-100 rose 3.4%, the Dow Jones rose 2.15%, and the Russell 2000 rose 3.15%.
Yields on Treasury bonds at the short end of the curve rose by 2–4 basis points. The dollar index fell by 0.6%, gold rose by 1%, and WTI crude oil fell by 4.4%.
The number of gainers in the S&P 500 was nearly six times the number of losers. Excluding NVIDIA (NVDA), the index would have gained about 2.7%. The top performers were the industrial sector (XLI: +3.82%), the IT sector (XLK: +3.73%), and the consumer discretionary sector (XLY: +2.92%). Energy (XLE: +0.52%), staples (XLP: +0.90%), financials (XLF: +1.45%), and real estate (XLRE: +1.45%).
Apple (AAPL: +2.43%) contributed 19 basis points to the index on news that CEO John Turnus plans to strengthen the AI segment. Broadcom (AVGO: +8.78%) and Microsoft (MSFT: +2.75%) contributed 18 and 17 basis points, respectively. AMD (AMD: +13.26%) contributed 14 basis points to the benchmark’s growth following Oppenheimer’s upgrade to “outperform.” Amazon (AMZN: +2.94%) contributed 12 basis points.
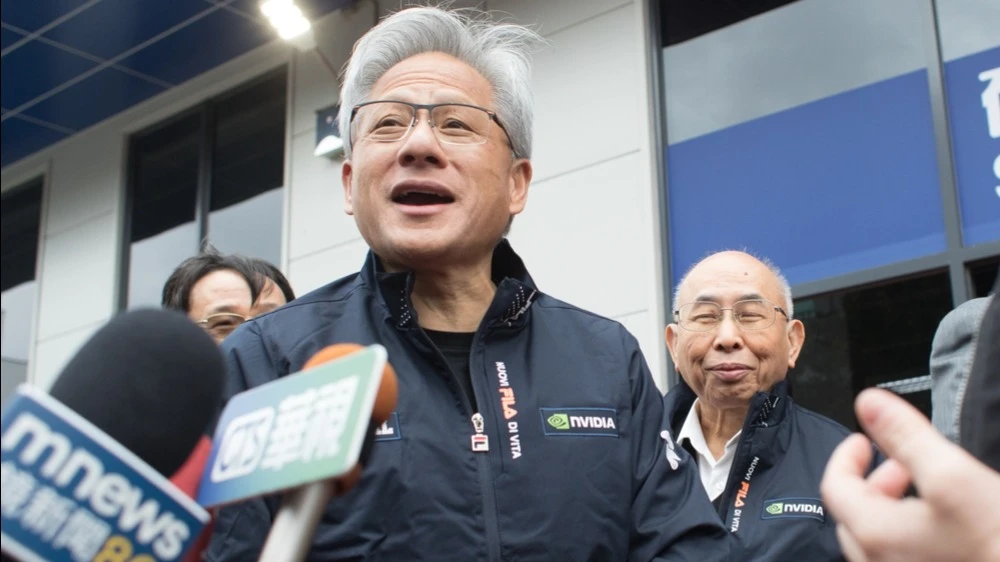
NVIDIA (NVDA: –4.27%) held back the S&P 500’s gains by 32 basis points due to an investigation into CEO Jensen Huang’s relationship with a woman whom U.S. authorities believe to be a Chinese intelligence agent. It is now unclear whether Huang will remain CEO.
Ferguson (FERG: +11.2%) reported better-than-expected results and raised its revenue growth forecast to 7%. NRG Energy (NRG: +10.4%) presented a strong earnings report and a plan to sell six LS Power gas-fired power plants for $4 billion. Surgery Partners (SGRY: +14%), according to Bloomberg, rejected UnitedHealth’s buyout offer of $28 per share. Eli Lilly (LLY: +4.3%) announced the success of Phase III trials for a drug to treat sleep apnea.
The news that AI companies and the Democratic Party were discussing ways to address concerns surrounding the construction of data centers helped fuel the rally.
According to the Federal Reserve Bank of New York, one-year inflation expectations rose by about 0.1 percentage points to 3.9%, while three- and five-year expectations remained unchanged. Osthan Goolsbee, president of the Federal Reserve Bank of Chicago, noted an acceleration in inflation in the services sector. Thomas Barkin, president of the Federal Reserve Bank of Richmond, described the interest rate as neutral or slightly below neutral.
This article was AI-translated and verified by a human editor