A New Direction: Why Bank of America Lowered Its Rating on Kazatomprom Shares
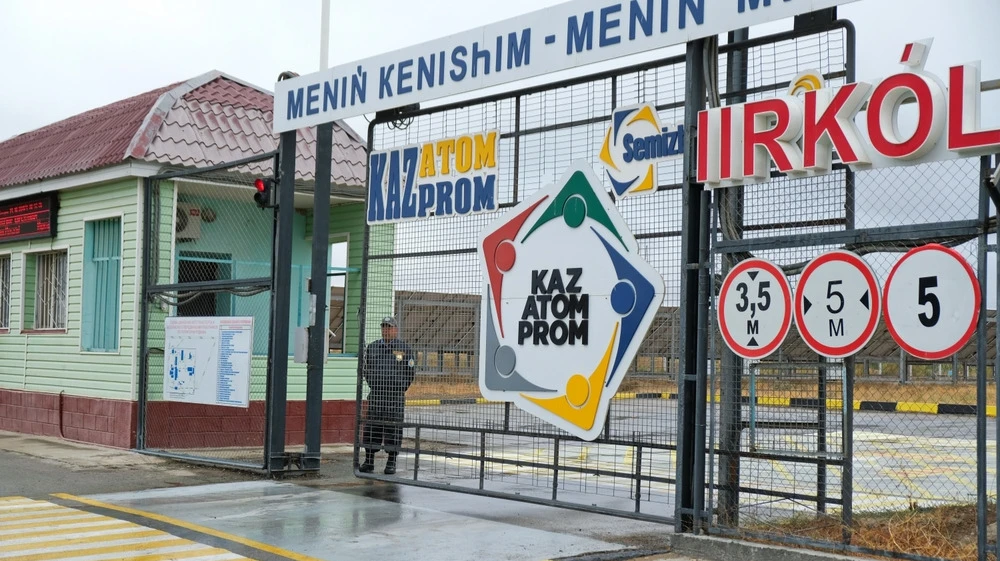
Bank of America expects uranium prices to rise by nearly 1.5 times in 2027. Photo: Vladimir Tretyakov/Shutterstock.com
Following the release of Kazatomprom’s operating results for the first nine months of 2026, Bank of America (BofA) lowered its price target for Kazatomprom’s depositary receipts from $94 to $93. The bank maintained its “buy” rating.
In line with expectations
Bank of America states in a research note that the third-quarter results were “in line with expectations,” and that the revision is primarily due to adjustments to the financial model and an update to the tenge exchange rate forecast. Previously, the investment bank had based its valuation of the stock at $94 on an exchange rate of 45,120 tenge—that is, an estimated dollar exchange rate of 480 tenge. It now expects the stock to reach a price of only 42,873 tenge—which, however, at the new estimated exchange rate of 461 tenge per dollar, amounts to $93. In addition, the bank lowered its EBITDA estimate for Kazatomprom for 2026 by 2%, to 1.09 trillion tenge ($2.43 billion at the National Bank’s exchange rate as of November 10, 2026), and for 2027—also by 2%—to 1.71 trillion tenge ($3.81 billion) due to a change in the currency model.
From the beginning of 2026 through the date of this report’s publication on November 4, the dollar exchange rate on the Forex market had fallen by 11%, from 507.4 to 451.81 tenge.
Production and Risks
The investment bank kept its production volume forecast unchanged at 28,998 metric tons, which is practically the upper limit of the company’s range. To achieve this result, fourth-quarter production must total 8,490 metric tons—17.7% more than in the third quarter.
At the same time, BofA acknowledges that Kazatomprom faces production constraints and risks—primarily related to the supply of sulfuric acid, a shortage of which previously forced the company to revise its production plans. In particular, analysts note that the launch of the Taiqonyr Qyshqyl Zauyty (TQZ) with a capacity of 800,000 metric tons per year—in which Kazatomprom will hold a 40% stake—has been postponed by 6–12 months from the first quarter of 2027.
The investment bank expects that an increase in acid supply from other producers will alleviate the problem. In particular, BofA points to the expected ramp-up to full capacity of EuroChem’s plant in Kazakhstan, which has an annual production capacity of 840,000 metric tons.
Nuclear Optimism
Bank of America maintains its forecast that the spot price of uranium will rise to $129.8 per pound in 2027, believing that Kazatomprom’s average selling price will consequently reach $102.88. As a result, BofA expects adjusted earnings per share to grow by 63.8% in 2027, although it forecasts a decline of 8.9% in 2026. Analysts note that they are reaffirming their bullish outlook on the uranium market following their participation in the World Nuclear Association’s annual symposium. “The nuclear skepticism of the 2010s has given way to ambitious deployment plans, which are supported by decarbonization and national security goals,” they note.
The group’s average sales price rose in the third quarter to $81.5 per pound of uranium concentrate, compared with $70.79 in the second quarter. The average spot price during the same period rose only from $85.18 to $88.56 per pound—meaning the gap between these figures narrowed by more than half. Kazatomprom explains that some of its existing long-term contracts contain fixed price components and price caps that were agreed upon under different market conditions. Therefore, the rise in market prices is only gradually reflected in the cost of shipments.
BofA forecasts Kazatomprom’s revenue at 2.37 trillion tenge ($5.28 billion). This is even higher than the company’s own forecast; in August, it lowered its revenue forecast for 2026 from 2.2–2.3 trillion tenge ($4.9–5.12 billion) to 2.1–2.2 trillion tenge ($4.68–4.9 billion). At the same time, analysts estimate the cash cost of uranium production at only $24.34 per pound—lower than the official forecast (the company estimates it at $25.5–27 per pound). The reasons for this discrepancy are not explained in the report.
Limits to Growth
According to BofA’s calculations, Kazatomprom’s shares are currently trading at a ratio of 4.7, compared to a historical average of 5.3, while its competitor, Cameco, has a similar ratio of approximately 14. When calculating the target price, the investment bank applies a multiple of 6.5 to the projected 2027 EBITDA, while valuing joint ventures and associates separately at ten times their earnings.
However, BofA’s optimism is limited: following an estimated average spot price of $129.8 per pound of uranium in 2027, the bank forecasts a decline to $111.67 for the following year. Accordingly, Kazatomprom’s 63.8% growth in adjusted earnings in 2027 is expected to give way to near-complete stabilization, and in 2028, BofA expects earnings to rise by only 0.4%.
At the close of trading on 10.11.26, Kazatomprom’s shares on the LSE fell 1.9% from the previous close, from $63.3 to $62.1. On the KASE, as of 1:15 p.m. Almaty time on November 11, 26, the company’s shares fell 0.88% to 28,051 tenge ($62.68).
This article was AI-translated and verified by a human editor