A Single-Product Company: Lessons from Oura’s Postponed IPO
The smart ring manufacturer was unable to convince investors that it is a technology platform

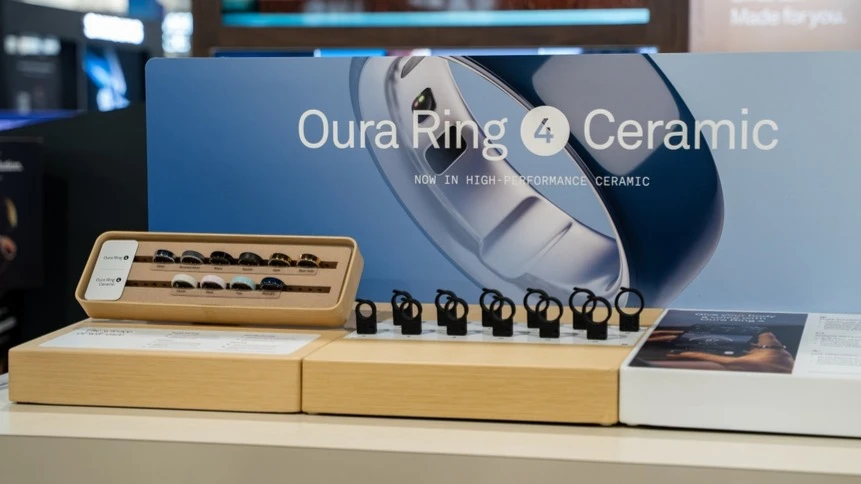
Oura positions itself as a platform for analyzing health data, while many investors see it merely as a seller of trendy gadgets / Photo: Erman Gunes / Shutterstock.com
Oura, a manufacturer of smart rings, postponed its IPO on the Nasdaq in late September, citing “market uncertainty.” Rising Treasury yields would indeed have complicated the offering, but a more significant problem was the disconnect between how Oura sees itself and how potential investors perceive it, according to The Wall Street Journal.
What's the problem?
In its prospectus, Oura positioned itself as a technology platform for analyzing health data, while many investors saw the company as nothing more than a seller of a trendy gadget, according to the WSJ. This distinction is fundamental: platforms can scale quickly and at low cost, while device manufacturers must repeatedly convince consumers to buy a new model.
Investors have already been burned by similar stories, the WSJ notes: companies like Peloton (smart exercise equipment), Fitbit (fitness trackers), Casper Sleep (sleep products), and GoPro (action cameras) have built recognizable brands but have all run into the same problem—the need to constantly sell new products to drive revenue growth.
Jay Ritter, a professor at the University of Florida, analyzed 13 companies that produce a single type of consumer good and went public between 2005 and 2024. According to his calculations, five years after their IPOs, their stocks lost an average of about 32% of their value, while the market as a whole grew by 49% over the same period. The only exception was Roku, which managed to outperform the market. The company, which started out manufacturing video players, has transformed into a media platform. In June, Fox Corp. agreed to acquire it for $22 billion.
What's next?
The story of Roku is a lesson for companies with a single consumer product, according to the WSJ. The publication identifies three possible paths for such businesses if they want to remain in the market for the long term.
One option is to follow Roku’s example and transform into a platform or a service with a recurring subscription. But that’s not the case with Oura: simply calling yourself a platform doesn’t mean you actually are one, the WSJ points out. About 80% of the company’s revenue comes from ring sales, and only 20% from subscriptions.
“Businesses built around hardware are naturally valued at a lower revenue multiple,” says Robin Boldt, chief investment officer at Rock2 Capital, a hedge fund specializing in the healthcare sector. While preparing for its IPO, Oura sought a valuation of approximately 10 times its revenue over the past 12 months. By comparison, fitness tracker maker Fitbit was sold to Google for less than two years’ worth of revenue.
Bloomberg previously reported, citing sources, that some investors had decided not to participate in Oura's IPO, considering the company's stated valuation of $15 billion to be too high.
Another possible path is to stop being a company that specializes in a single product, as Garmin did. The company was best known for its GPS car navigation systems, but smartphones destroyed that business. Now Garmin derives most of its profits from fitness watches, outdoor gear, and aviation and marine electronics.
The most promising path for Oura and other wellness startups would be to shift the cost from consumers to a third party—such as employers or insurers, according to the WSJ. Through insurance, consumers receive ResMed sleep apnea devices and Dexcom glucose monitors, while employers pay for the Hinge Health physical therapy app. Oura has partnership agreements—in particular, with the Natural Cycles fertility app, to which body temperature data is transmitted. Employers are willing to spend significant amounts on reproductive health programs for employees, but Oura has yet to prove that wearing its ring actually improves health, rather than simply measuring it, the newspaper notes.
The simplest solution, at least for investors, might be a takeover. Theoretically, Oura could be acquired by a technology company, but a major player in the healthcare sector would seem like a more natural buyer. Prior to its IPO, the American giant Eli Lilly invested in the company. It could be valuable for the pharmaceutical manufacturer to know whether patients taking its drugs Zepbound and Mounjaro are sleeping better and moving more, the publication notes.
“Oura doesn’t necessarily have to become the next Apple or even the next Garmin. It needs to prove that the data it collects is valuable to someone other than the consumer—and that its business isn’t just about selling expensive rings,” the WSJ notes.
This article was AI-translated and verified by a human editor