China, TikTok, and Gen Z: CNBC analyst sees opportunity in Crocs
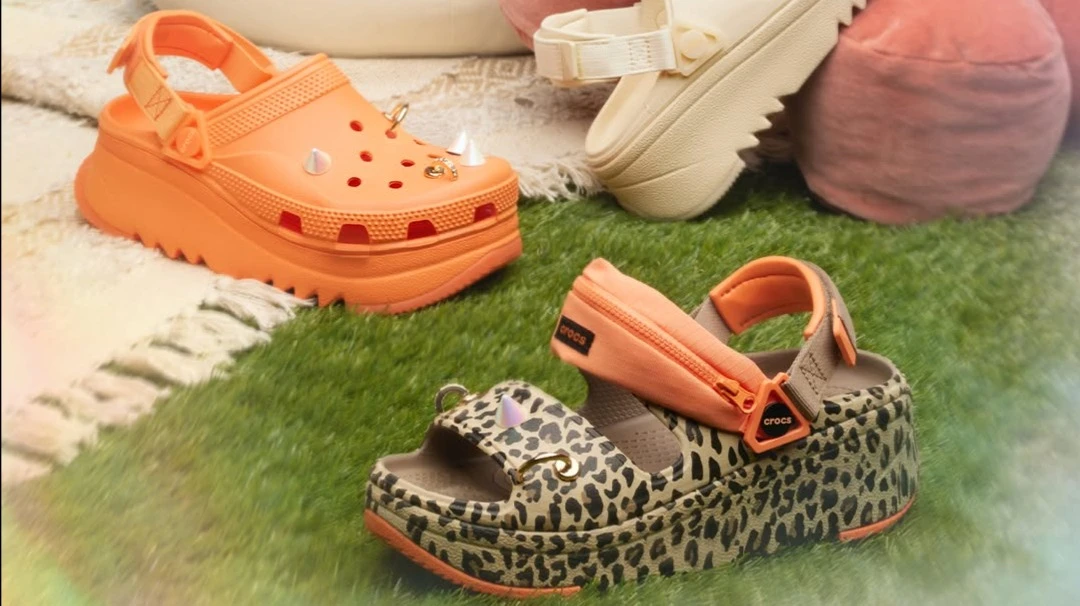
Crocs shares have gained more than 37% year to date, but Wall Street sees almost 17% further upside / Photo: Facebook / CrocsPL
Now is a good time to buy shares of small-cap footwear maker Crocs, CNBC analyst Justin Zacks argues in an post. Celebrity partnerships, TikTok Shop integration, and new styles are fueling demand for its products among Gen Z consumers, especially in China. Meanwhile, the stock trades at a steep discount to peers such as Nike, he notes.
Details
Crocs shares have gained more than 37% year to date to $117.50 apiece, leading some investors to think they have missed their chance to buy. Zacks disagrees. The stock still trades below levels seen five years ago, at just eight times forward earnings for the next 12 months. That represents a steep discount to peers such as Nike, even though Crocs has more growth drivers, he reckons. He highlights the following growth drivers.
New footwear styles
The 2026 launch of the Saturday Sandal, a customizable sandal with two straps, drew an “exceptional response from our consumers and retailers globally,” Crocs CEO Andrew Rees said on the second-quarter earnings call. The company reported revenue growth of 2% year over year on a constant currency basis to $1.18 billion, allowing the management to raise its full-year guidance.
Rees noted that momentum in the sandal category had strengthened Crocs’ North American business, helping it return to sales growth in the region. He expects the category to become an even more meaningful growth driver globally in 2027 and beyond. Rees also highlighted strong consumer interest in lifestyle footwear, which is particularly popular in Asia.
“We are encouraged by... the fact that growth is becoming increasingly diversified,” BofA analyst Kendall Toscano wrote after the quarterly results, according to Zacks.
Marketing and celebrity partnerships
Crocs aims to turn its footwear into the “ultimate badge of individuality, authenticity and high-fashion cool,” Zacks writes. The brand has released collections with musicians Justin Bieber, Post Malone, and Bad Bunny, actresses Drew Barrymore and Millie Bobby Brown, and luxury designers Balenciaga and Christopher Kane.
In June, Crocs launched Déjà Shoe on TikTok, the first shoppable series from a footwear brand, allowing viewers to buy featured styles while watching. The initiative amplified demand for ballet flats and sandals and drove traffic to Crocs’ site, Rees said on the earnings call.
He also said the company is “testing several innovations” beyond its traditional Jibbitz charms, which attach to the ventilation holes in its shoes to let wearers customize them. Rees described personalization as “a powerful driver of consumer engagement and a key competitive advantage for our brand.”
Growth in China
The Crocs brand’s international revenue rose 7.8% to $542 million in the second quarter. Its high-priority markets, including China, delivered “double-digit growth,” Rees highlighted.
Zacks believes there is more room to grow. “China is our second largest international market, but it accounts for just 4% of our global sales. So, there’s a lot of people in China. There’s a lot of feet,” he quotes Crocs CFO Patraic Reagan as saying.
Crocs won over Chinese Gen Z consumers by downplaying its U.S. origins, Zacks continues. Among other moves, it renamed its global “Come As You Are” campaign “Born to Be Free.” “Importantly, we leveraged our read-and-react abilities to quickly bring China for China products to market, including unique iterations of our Ballet Flat,” Rees said.
Zacks also likes Crocs’ strong free cash flow. The company uses that cash to repurchase shares: in July, it increased its buyback authorization by $1.5 billion to $2.0 billion. The CNBC analyst notes that this could significantly boost earnings per share. Second-quarter EPS came in at $4.13 versus a loss of $8.82 per share a year earlier. Last year’s loss reflected $737 million in noncash impairment charges related to the HeyDude brand, the company noted.
Challenges
Recent changes in revenue recognition are making it harder for investors to fairly value Crocs stock, Zacks argues. Under a new business model with a major partner, some revenue will shift from the direct-to-consumer channel to the wholesale channel beginning in the third quarter, Reagan said on the earnings call. The company expects this to reduce reported revenue but benefit operating profit.
Wall Street, however, found the explanation insufficient. “Not only wouldn’t CROX management say what business was shifting from DTC to wholesale, they also would not say the amount of the change,” Williams Trading analyst Sam Poser wrote, according to the CNBC post.
Zacks sees weak performance at the HeyDude division as another reason for the stock’s discounted valuation. Its revenue had been falling at double-digit rates for an extended period, but in the second quarter, the decline narrowed to just 5.7%, bringing revenue to $179 million.
Wall Street analysts are split on Crocs: it has nine “hold” ratings, eight “buy” calls, and one “sell” recommendation. The average target price is $137.00 per share, implying almost 17% upside.