Intel risks $140 bln wipeout as stock heads for worst day on record
"Houston, we have a problem," a Cantor Fitzgerald analyst wrote after the chipmaker's 3Q26 earnings
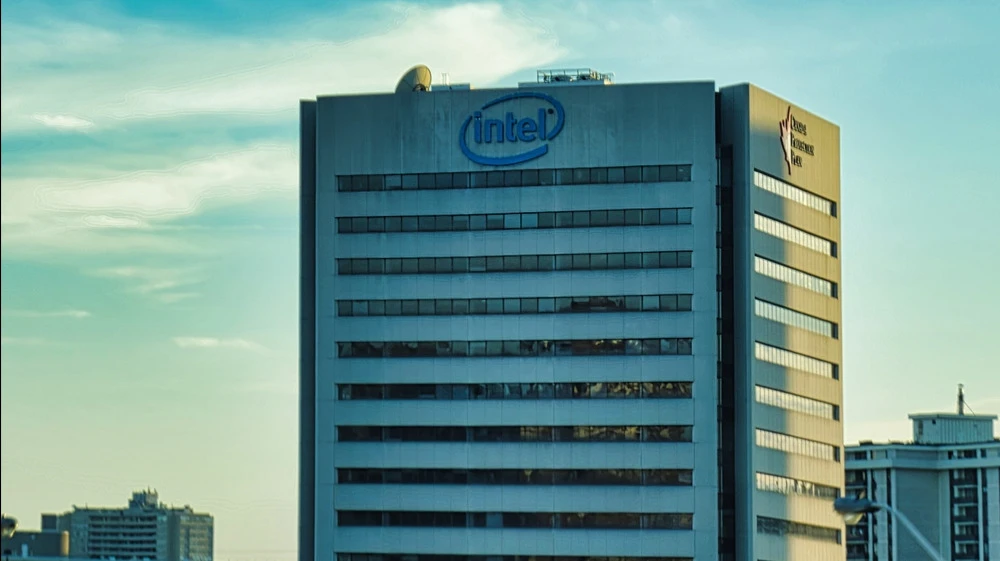
Intel could lose $140 billion in market value in a day / Photo: KimVermaat / Shutterstock.com
Intel shares plunged 27% to $67.20 apiece in trading on Friday after the chipmaker released its third-quarter earnings a day earlier. If the decline holds through the close, it would mark the stock’s worst day on record, Bloomberg reports. The selloff could wipe out around $140 billion in market value, on MarketWatch’s numbers.
Shares of Intel partners and rivals also fell: Advanced Micro Devices lost 9.4%, Nvidia dropped 3.4%, and Dell Technologies slid 8.3%. The Philadelphia Semiconductor Index declined 5.7%. Taken together, the latest corporate earnings threaten to erase all of the Nasdaq 100’s gains from the start of the week, Bloomberg notes.
Analysts have already begun revising their views on Intel stock. Despite a strong quarter, the management issued top-line guidance that fell short of market expectations, citing weak demand for PC processors and supply-chain problems affecting chipmaking components. BofA has dropped its “buy” recommendation following the financials, while other analysts have cut their target prices.
Wall Street reaction
BofA: BofA analyst Vivek Arya downgraded Intel from “buy” to “neutral” and cut his target price from $145 to $100 per share, CNBC reports. The new TP implies 9% upside from Thursday’s close. “The stock has not communicated enough traction with external foundry customers, while its data center strength is offset by a surprisingly sharp drop in PC shipments (down 25-30% [quarter over quarter] in the 4Q, further inventory correction expected in 1H27),” Arya wrote in a Friday note cited by CNBC.
He highlighted the strength of Intel’s server processor business amid growing demand from agentic AI, while pointing to supply constraints affecting key components. “Data center CPU is doing well in a rising agentic tide, but faces a tight supply (substrate) environment, and products are not yet technically competitive against… rivals that are growing 2-4 times faster,” Arya added.
UBS: Analyst Timothy Arcuri lowered his target price on Intel from $100 to $80 per share, implying 13% downside from Thursday’s close. “INTC guided well below even the most bearish investor expectations owing to a much worse than expected PC segment, though this is broadly consistent with MSFT’s commentary from its earnings call last night,” he wrote.
Arcuri sees a challenging recovery ahead for the PC market, with no relief in sight for memory-chip prices or supply, particularly as demand for servers running agentic AI applications continues to grow.
Bernstein: Analyst Stacy Rasgon cut his target price on Intel from $110 to $75 per share, CNBC reports. The new TP is around 19% below Thursday’s close. “Intel has benefited from a very strong server market and a supportive narrative around their potential foundry prospects,” Rasgon wrote. “However, this had led investors to gloss over an increasingly negative PC outlook; unfortunately this is the quarter when they hit the wall in that regard.”
More disappointing, he argues, is that the management once again “clearly did not see it coming” and “is still struggling to get their manufacturing footprint aligned with the market.” Intel still has too much capacity for PC processors and too little for server chips, he noted, “the latter a year into the current cycle.”
Jefferies: Analysts led by Blayne Curtis see a positive in the fact that Intel’s revenue guidance was lowered because of weaker PC demand rather than a deterioration in the outlook for its data center and AI group, MarketWatch reports. However, they expect Intel to keep losing market share throughout next year, “making it tough to underwrite the longer-term story even with Foundry/packaging customer announcements.”
Morgan Stanley: Analysts led by Joseph Moore do not find Intel stock compelling even after the selloff, MarketWatch reports. They expect the company to keep losing market share to fabless rivals, which have lower capex requirements.
Cantor Fitzgerald: Analyst CJ Muse needed just five words to describe the company’s outlook: “Houston, we have a problem,” as Benzinga reports. Muse maintained his “neutral” rating but cut his target price from $125 to $90 per share. He noted that shortages of chipmaking components are forcing a substantial reset to Intel’s financial forecasts. He also lowered his 2027 earnings estimate from $2.15 to $1.65 per share, versus the Wall Street consensus of $2.13 per share, and flagged Intel’s clear loss of server processor market share to AMD.