Is the small-cap rally ending? Four rules for picking stocks as the Fed raises rates
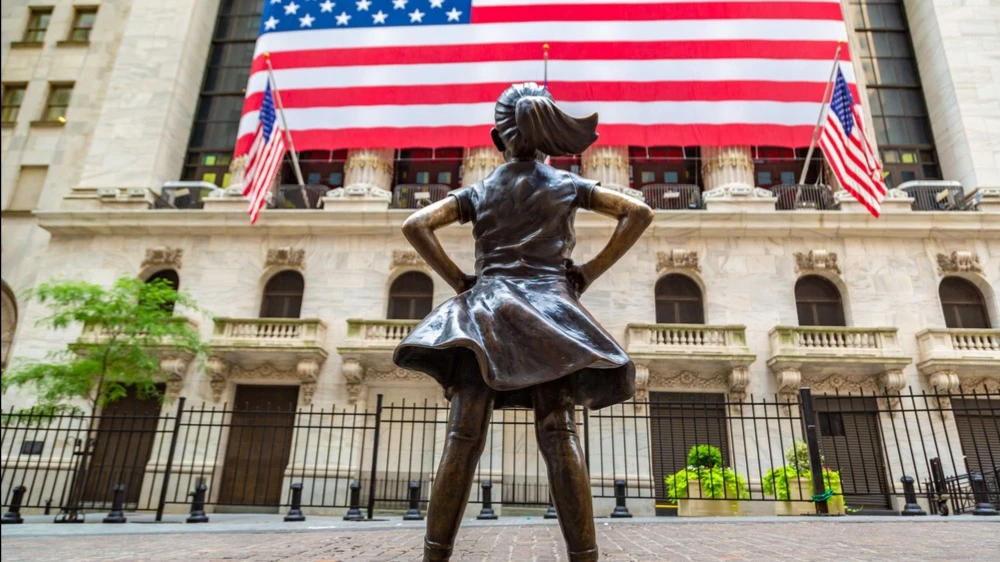
In the second quarter, small caps posted their fastest earnings growth since 2022, data compiled by Jefferies and cited by Bloomberg shows / Photo: Sergii Figurnyi / Shutterstock.com
For most of this year, investors have flocked into small caps to diversify their portfolios and reduce their reliance on a narrow group of AI-related stocks. The first half marked the Russell 2000’s strongest since 1991: the index gained 21%, outperforming the major U.S. bourses. However, the prospect of further Fed rate hikes now threatens the small-cap rally, Bloomberg notes. Smaller businesses depend more heavily on borrowed capital and are more sensitive to rising financing costs.
At the request of Oninvest, Vadim Merkulov, head of research at Freedom Finance Global, discusses how investors should approach picking small-cap stocks as rates rise.
Details
The Russell 2000’s year-to-date lead over the S&P 500 has narrowed from 11 percentage points in June to just 2 percentage points, Bloomberg writes. The index has fallen below its 50- and 100-day moving averages, while large-cap indexes continue to trade above those levels.
The Russell 2000’s reconstitution created an additional problem, as four companies – Bloom Energy, Credo Technology, Sterling Infrastructure, and TTM Technologies – accounted for two thirds of the index’s gains through June 29 before they moved to the Russell 1000. Other beneficiaries of the AI boom also left the index. As a result, the average Russell 2000 constituent became smaller and more sensitive to rate hikes.
Still, it is too early to write off small caps altogether: in the second quarter, their earnings grew at the fastest quarterly pace since 2022, Bloomberg points out, citing Jefferies data. However, strategists at BofA, Barclays, JPMorgan, and 22V Research quoted by Bloomberg expect the segment's performance to become less uniform. Instead of buying the entire index, investors will need to focus more on profitable companies with resilient businesses and moderate debt loads.
Four rules
Avoid heavily indebted companies
Rate hikes have little effect on large companies, while small caps are vulnerable because of the structure of their businesses and debt. Interest expense for Russell 2000 companies equals around 31% of EBITDA, versus 6.7% for S&P 500 companies, Merkulov of Freedom Finance Global notes. In addition, around 30% of their debt is floating rate, versus around 7% for large-cap companies. Almost 40% of Russell 2000 constituents remain unprofitable.
Merkulov recommends avoiding heavily indebted property developers, companies whose demand depends on the availability of consumer credit, and unprofitable biotechs that will soon require fresh financing. More resilient opportunities can be found among energy companies, profitable medical-device manufacturers, consumer staples producers, and insurers.
Put a premium on quality
The Russell 2000 rally is probably already over, Merkulov reckons. Individual profitable companies with resilient business models, such as those with a high share of recurring revenue, may continue to perform well.
The S&P SmallCap 600, which includes companies of higher financial quality, looks more promising. Merkulov believes it has better prospects for further gains. However, the S&P 500 appears even more attractive: corporate earnings growth this year is strong enough to more than offset higher rates. The picture is more complicated in the small-cap segment.
Check debt and maturity schedules
When initially screening nonfinancial companies, Merkulov recommends looking for a net debt/EBITDA ratio below 2-3 and EBIT/interest expense ratio above 4.
Another key metric is the amount of debt that must be repaid or refinanced over the next 6-24 months. New financing will be more expensive. At the same time, Merkulov stresses that he does not expect a repeat of the rate-hike cycle seen in 2022: this time, it will probably be milder.
After compiling a shortlist of companies, investors should review Item 7A of their annual reports on Form 10-K. Many issuers use this section to estimate how much their interest expense will increase if rates rise 1 percentage point. This can help investors assess the potential risks.
Do not exit small caps completely, but reduce risk
Merkulov does not recommend tossing small caps out of portfolios altogether. Instead, he advises focusing on higher-quality exposure, such as companies in the S&P SmallCap 600 or individual resilient sectors.
Experienced investors can complement long positions in high-quality companies with a bet against the Russell 2000 through put options expiring at year-end. However, this is a speculative strategy and is not suitable for everyone, Merkulov cautions.
A shift in expectations for the path of interest rates, along with an actual decline in government bond yields and a narrowing of credit spreads, could signal that it is time to return more broadly to small caps.
This text is for informational purposes only and does not constitute personalized investment advice.