"The 'Back-Seat Bank': How Kazakhstan Is Preparing to Integrate AI into Everyday Transactions"
AI agents will be able to independently compare offers and make payments on behalf of clients. Photo: Shutterstock
In 2027, the National Bank of Kazakhstan will begin testing “agent payments”—a system in which AI assistants will be able to select goods, deposits, or loans on their own and pay for them on behalf of the customer. In a column for Oninvest, Vadim Novikov, an advisor to the president of Almaty Management University, explains how the transition to an “agent economy” works, what risks banks face, and how users’ lives might change.
Kazakhstan has set a goal to increase competition in the banking sector and expand the range of financial services available to customers. In 2026, a new banking law authorized the use of AI for risk assessment and management while maintaining banks’ responsibility for such decisions. Related amendments formalized the operation of the open banking system, which Kazakhstan began testing in 2023. In his October State of the Nation Address, President Kassym-Jomart Tokayev identified expanding opportunities for citizens as the goal of the next phase of digitalization.
The National Bank plans to test agency payments in 2027. With this type of payment, an AI assistant pays for a purchase or service on behalf of the customer. Binur Zhalenov, Deputy Chairman of the National Bank, cited open banking and instant payments as the foundation for such transactions. He provided examples for both individual customers and businesses: purchasing a ticket within a set budget, buying supplies, and renewing a subscription. In his view, this format will be particularly useful for companies that already have expense approval policies in place.
The customer can still pay with their bank card, even if the assistant selects a merchant on a different platform. If the assistant is asked to find a savings account or loan, the choice may fall on a different bank.
The “three horizons” model helps distinguish changes in the banking industry based on their depth. In the first horizon, the bank performs its existing tasks in a new way. In the second, customers gain access to new services, such as viewing accounts from multiple banks in a single app. In the third stage, the customer sets the conditions, and the assistant independently selects which offer to accept. These changes occur in parallel and at different speeds. The same bank may automate payment verification, integrate external services, and test agency purchases.
The First Horizon—Automation
In September 2026, the financial regulator ARRF estimated that approximately 75% of Kazakhstan’s banks were using AI. The agency had provided a similar estimate as early as November 2025 and noted that the extent of adoption varies from bank to bank.
Paragraph 8 of Article 52 of the Law “On Banks” permits a bank to use AI for risk assessment and management, but the bank remains responsible for decisions made with the help of AI. The bank decides whether to grant a loan and bears the risk associated with it.
Let’s imagine that someone is buying a laptop. They browse the catalog, compare models, and choose a payment method. When the buyer pays for the laptop with a card, the bank verifies the payment. This is where AI can help detect signs of fraud. The bank can also use AI when processing loan applications and in customer support to reduce manual work, serve customers faster, and make fewer mistakes.
For an investor, the outcome of the first horizon is reflected in service costs, transaction processing times, and losses resulting from errors or fraud.
The Second Horizon: Open Banking
A laptop buyer may have accounts at several banks. With the buyer’s consent, a third-party app will display the balances of the linked accounts on a single screen. When a user selects an account and decides who to pay and how much, a service authorized to access the system can send a payment order to the bank.
Through the major British banks of the CMA9 group (a group of nine UK banks that the British regulator required to implement uniform open banking standards, such as Barclays, HSBC, etc. — Oninvest), more than a billion payments have been initiated since the launch of open banking. This milestone was reached in June 2026.
The British app Snoop uses open banking to collect account data from various banks. It analyzes spending and suggests ways to save money. You can also set up automatic transfers to a savings account within the app. Another British app, Plum, calculates how much a customer can set aside based on their transactions and automatically sets that amount aside based on a pre-authorized permission.
The U.S.-based company Plaid and the U.K.-based company TrueLayer provide other companies with tools to access banking data and process payments. With a single integration, an app can work with accounts at multiple banks. The set of available features depends on the country and the bank, and the customer must authorize access to the account.
Kazakhstani law allows customers to access electronic banking services through third-party payment service providers. The bank maintaining the account provides the authorized provider with account information within the limits of the customer’s consent and in accordance with the National Bank’s regulations. The data is transmitted via standard open banking system APIs.
The National Payment Corporation reports that interfaces for exchanging data on accounts, balances, and transactions are available for second-tier banks (all commercial banks—Oninvest) to connect to. To operate through the system, a third-party provider must undergo authorization and be listed in the registry. However, we were unable to find any examples in open sources of independent services that are already serving customers in Kazakhstan through this system.
The customer confirms to whom, for which account, and for which service they are granting access. Consent in the open banking system is valid for no longer than 30 calendar days and may be revoked earlier. The bank executes the payment as instructed by the customer. The third-party provider is liable for the consequences of unauthorized payments and fraudulent activities related to transactions initiated through its system.
The Third Horizon — Know Your Agent
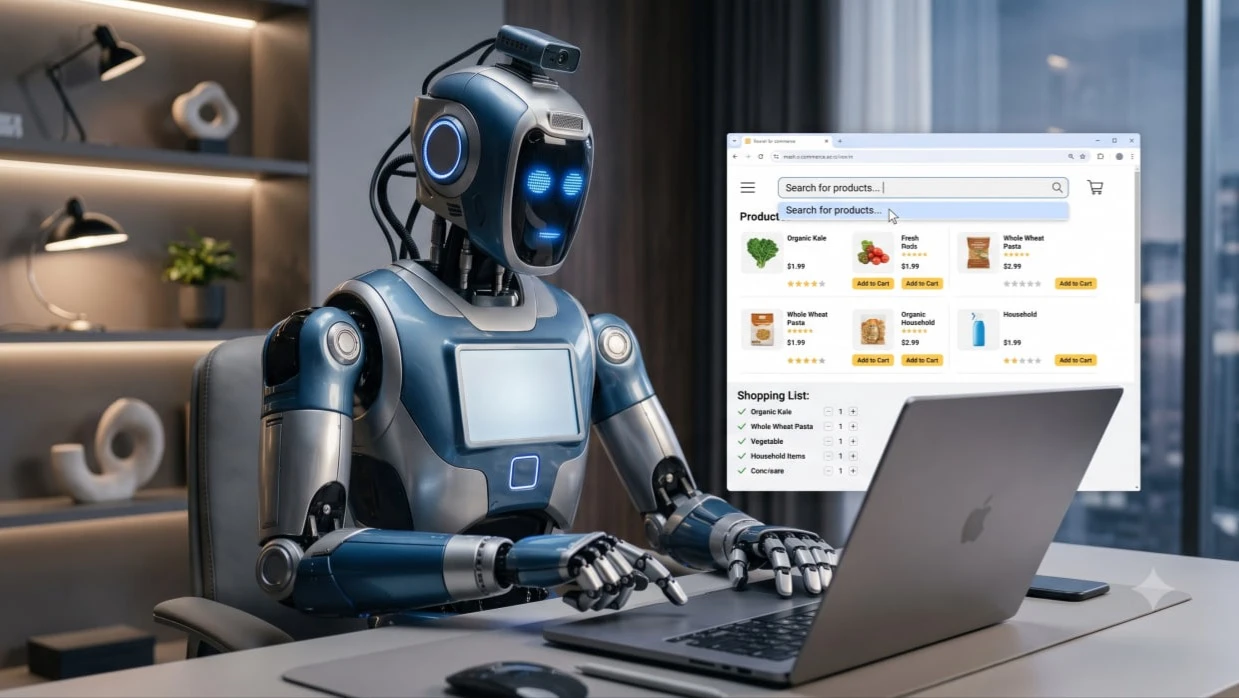
“Find a laptop for work for up to 400,000 tenge with delivery by Friday, and pay for it if the terms are right,” the customer instructs. He sets the terms, and the assistant selects both the model and the seller who will receive the order.
In order for an assistant to pay for a laptop, the buyer grants the assistant permission in advance and sets conditions, such as a maximum amount and a time limit. The AP2 protocol, proposed by Google, allows a specific purchase and payment to be linked to these conditions. If the price exceeds the limit, the assistant will need new authorization from the buyer.
In Kazakhstan, the National Bank is preparing proposals regarding “Know Your Agent” standards and infrastructure so that it is possible to determine which program is in effect and what its mandate is. Customers also need the ability to revoke an order, see who paid for what, and understand whom to file a claim with.
An unfavorable but permissible choice of an assistant and an unauthorized payment are different grounds for a dispute. Revoking access does not cancel a purchase that has already been made. When it comes to a loan or a deposit, these differences are even more significant.
In order to select deposit and loan products from various banks on behalf of a client under a long-term power of attorney, the assistant will need comparable personalized offers and the authority to perform specific actions. Separate procedures will be required for entering into contracts and resolving disputes.
If this becomes a regular practice, the bank may end up being just one of the providers from which the assistant chooses. In its report “Digitalization of Finance” (2024), the Basel Committee on Banking Supervision examines the “back-office bank” scenario, in which the bank provides services while an intermediary manages the relationship with the customer.
What's Changing for Banks
Banks can also create their own virtual assistants. For example, the AI assistant Kasper helps shoppers select products on the Kaspi.kz marketplace. In a report dated November 9, the company announced that 1.4 million customers in Kazakhstan have used it since its launch in July. The company expects that, over time, it will be possible to assign other everyday tasks to it as well.
The Kaspi.kz group generates revenue from payment processing and marketplace operations, including advertising and delivery. If an assistant finds a laptop on another platform and the buyer pays with a Kaspi card, the bank will still process the payment through its card, but the order will go to a competitor.
The bank itself may face pressure on its loan income and rising costs of attracting deposits. If it becomes easier for customers to transfer their savings to institutions offering higher interest rates, a bank that is accustomed to attracting funds cheaply may have to pay more for them. And a loan comparison tool could steer a borrower to another bank.
If a bank pays an intermediary for referring customers, a portion of the revenue from new transactions will go toward that commission. To evaluate the results, you need to know the volume of transactions, the revenue from each transaction after deducting variable costs and expected losses, as well as the costs of general infrastructure and oversight.
Having your own personal assistant is one way to protect your relationship with customers. A bank can also partner with an external service, acquire it, or attract customers with favorable terms and reliable service. For example, Snoop is part of the Vanquis Banking Group but also works with accounts from other banks.
The new intermediary isn't necessarily impartial either. If suppliers pay the assistant to bring in customers, he has an incentive to recommend whoever pays more. It’s important to understand what offers the assistant sees, how they make their choices, and who pays for their work. Competition over convenience could give rise to yet another influential intermediary.
For the reform, the key question is whether the client will receive more offers from different providers. For the investor, the key questions are who secures the deals and how much revenue they generate after expenses. Based on completed transactions, it will be possible to determine who referred the client, who executed the order, and who received the revenue.
This article was AI-translated and verified by a human editor