"The Market Has Begun to Punish France": Why the Bond Sell-Off Has Hit France Harder
The growing budget deficit and political deadlock have exacerbated the impact of the global sell-off on the debt market of the European Union's second-largest economy
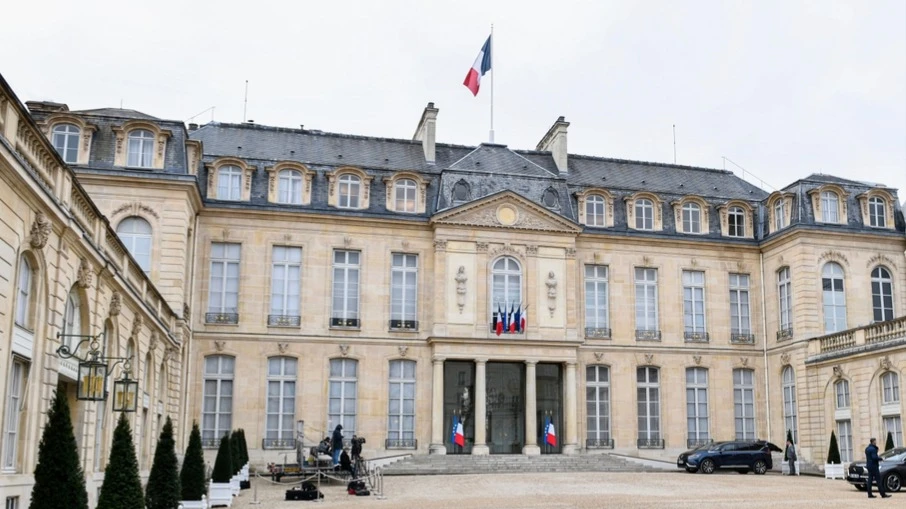
In May 2027, the Élysée Palace will have a new occupant for the first time in 10 years / Photo: Victor Velter/Shutterstock.com
The global bond sell-off hit France harder and faster than market participants had expected. Investors are demanding an ever-higher premium for holding its debt, doubting that Paris will be able to reduce its budget deficit amid political instability.
The market has stopped forgiving debts
The yield on 10-year French government bonds has risen by more than 1 percentage point since June and is now approaching 5%. According to Bloomberg, the third quarter was the worst for these bonds since the introduction of the euro in 1999, while Reuters notes that it was the worst since 1987.
Investors had expected that the government's fall disputes with parliament over the budget would cause tension in the bond market. However, instead of the promised reduction, the government's budget deficit is growing, and this has heightened their concerns.
The public debt-to-GDP ratio has approached 120%—nearly twice that of Germany. “The market is beginning to punish France for its debt level, although that wasn’t always the case,” said Marie Jacot, head of the French division of Edmond de Rothschild Asset Management, on Bloomberg TV.
The budget comes down to Parliament
The draft budget presented on October 1 calls for an unusually large cut in spending, Bloomberg notes. The French Cabinet expects to reduce the deficit from 5.4% of GDP this year to 5% next year. However, the budget oversight body has already called the economic forecasts on which the draft budget is based “optimistic,” according to Trading Economics.
The government does not have a majority in parliament, so it will be difficult to get lawmakers to agree to unpopular austerity measures, Reuters reports. Lawmakers have already forced prime ministers to resign on several occasions, causing concern among investors, Bloomberg notes.
The elections offer no way out
The 2027 presidential election adds to the uncertainty: far-right candidate Marine Le Pen and far-left candidate Jean-Luc Mélenchon could advance to the second round.
If Paris fails to resolve its budget problems, the consequences could extend beyond the country’s borders: Bloomberg warns of the risk that tensions could spread to other European bond markets and that fiscal discipline in the EU could weaken. However, market participants do not yet expect the ECB to have to come to France’s aid, according to Reuters.
Five Pain Points
Reuters has identified five key issues in the French market that investors concerned about government debt are monitoring:
Spread against Bunds. The risk premium on French debt has reached its highest level since the 2012 eurozone crisis: the spread between the yields on 10-year French government bonds (OATs) and German Bunds, the eurozone’s benchmark bonds, exceeded 110 basis points (bp). The market was surprised by the speed of the move: in late August, Barclays had described a spread widening beyond 100 bps this year as an unlikely and extremely negative scenario for France. John Thornton, head of the fixed-income division at Keyridge Asset Management, has already suggested that the spread could widen to 200 bps.
OAT futures ( French government bonds). Some investors are bracing for renewed market stress specifically in France and are betting on a decline in OAT futures, said Théophile Legrand, a strategist at the French bank Natixis. Analysts surveyed by Reuters cite a possible second round in the 2027 presidential election between far-right candidate Marine Le Pen and far-left candidate Jean-Luc Mélenchon as one of the risks. Another threat is further downgrades of France’s sovereign credit rating: Scope downgraded it in September, and Moody’s may follow suit in late October.
Stocks and Banks. The CAC 40, France’s blue-chip index, has fallen by about 3% since the start of the year, while the pan-European STOXX Europe 600 has risen by nearly 7%. Shares of France’s largest banks, Credit Agricole and Societe Generale, have also fallen by about 4%. Bonds issued by small French banks and insurance companies that operate primarily within the country are also underperforming the market, said Alex Temple, a portfolio manager at Allspring Global Investments.
CDS Costs. According to LSEG, the cost of insuring French government debt against default has risen to its highest level in nearly a decade. The cost of insurance on five-year credit default swaps (CDS) on French debt is about 52 basis points per year—twice as much as it was six months ago. Over the past three months, it has risen by 25 basis points; for Italian CDSs, the increase was approximately 13 basis points; and for German CDSs, it remained virtually unchanged.
A weak euro. The euro ended September at its lowest level since May 2025, even as eurozone bond yields rose. This combination typically signals investor anxiety. The weak euro is driving up the prices of imported goods and energy, which could exacerbate France’s budget problems. Traders are pricing in at least three ECB rate hikes by April, and if there are fewer than that, the euro’s decline could continue. Brock Weimer, an analyst at investment firm Edward Jones, considers these expectations somewhat aggressive: in his view, the ECB is unlikely to risk raising rates when the economy is already sluggish.
This article was AI-translated and verified by a human editor