The number of S&P 500 stocks moving opposite the index hits a record
Evercore sees these stocks as a way to reduce a portfolio’s exposure to AI, though they offered less protection in September than during previous selloffs
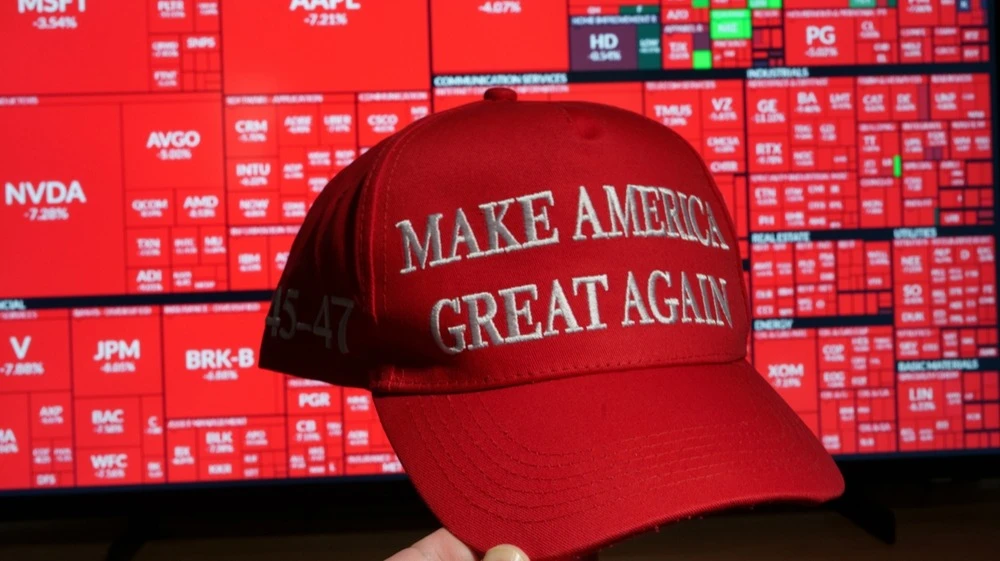
The tendency of some U.S. stocks to move against the market helped limit the S&P 500 losses during selloffs in March and July / Photo: Ascannio/Shutterstock.com
The number of S&P 500 stocks that tend to move in the opposite direction from the index has risen to 130, the highest count on record, according to investment bank Evercore ISI. A similar pattern accompanied the deflation of the dot-com bubble in the early 2000s. Evercore strategist Julian Emanuel now sees these stocks as a hedge against a potential bursting of the current AI bubble.
Divergence from the index
Such names are known in finance as negative-beta stocks: beta measures a stock’s sensitivity to market fluctuations, and negative beta means that a stock typically moves in the opposite direction from the market, MarketWatch explains. As of July 31, 121 stocks had negative beta, the highest number since 1990.
The S&P 500 can remain near record highs even while many of its constituent stocks are declining. When individual stocks make sharp moves at different times and for different reasons, those moves largely offset one another at the headline index level, WisdomTree director of investing strategy Bradley Krom pointed out to CNBC. As a result, according to Krom, high volatility in individual stocks can be concealed beneath the apparent stability of the S&P 500.
A hedge against a dip in AI stocks
Emanuel of Evercore believes that an inverse relationship with the index can help reduce a portfolio’s exposure to AI. “In a world where every other asset has become correlated to AI in ways that investors may not fully appreciate, it is harder to diversify,” MarketWatch quotes him as saying. “But there’s also this other universe of stocks that, day in and day out, provide an element of portfolio diversification because they move inversely to the index.”
Evercore’s October list of negative-beta stocks is heavily tilted toward energy, consumer staples, and utilities. Insurance stocks also feature prominently. In theory, stocks with negative beta should help offset losses when the stocks pushing the index higher stop working, MarketWatch writes. In practice, according to Emanuel, this hedge helped limit the S&P 500’s losses during the March selloff and again in July, when the AI-driven rally stumbled. The effect was less pronounced in September, but the strategist expects these stocks’ defensive properties to reemerge during future selloffs.
Why stocks are moving opposite the index
The tendency of some stocks to move opposite the S&P 500 largely reflects the heavy weight of tech giants in the index, argues LPL Financial strategist Adam Turnquist. Gains by a handful of the largest companies can lift the index even as many other stocks decline, he told CNBC. Massive investment in AI has supported chipmakers, hardware companies, and other AI infrastructure beneficiaries, while companies outside the theme have struggled to keep pace with the leaders.
For energy stocks, negative beta has a different source: their response to oil prices. “Another part of the story is energy,” Turnquist said. “That’s been pronounced this year: higher oil prices, higher energy stocks and then the rest of the market trades lower.” If market leadership broadens, the number of negative-beta stocks could decline, he points out. However, the strategist expects dispersion in stock performance to remain elevated as investors pick companies that can benefit from the AI boom.
Will there be repeat of 2000?
When Emanuel’s team first highlighted the rising number of negative-beta stocks in a June report, he said, “the people who are bearish want to look at it and see that it says that we’re about to have a bubble pop.” The strategist acknowledged that this reaction is not entirely unreasonable: the last time the number of such stocks peaked was in early 2001, as the dot-com bubble was deflating.
Another signal also echoes the dot-com era. On September 21, the S&P 500 rose 1.5%, but 30 stocks hit 52-week lows, while only seven reached new highs. According to SentimenTrader founder Jason Goepfert, the last time the S&P 500 gained at least 1% while sitting within 1% of a 52-week high and new lows outnumbered new highs was December 1999, just before the peak of the dot-com boom, CNBC reported.
Turnquist of LPL Financial, however, pushed back against a direct comparison: today’s tech leaders are mature businesses with established products that already generate revenue. Krom of WisdomTree also attributes the negative betas primarily to index concentration and expects the current extreme readings to eventually return to normal. “It is not the same market environment now versus 2000,” he emphasized, according to CNBC.