Analyst sees 120% upside in French quantum computing developer Pasqal
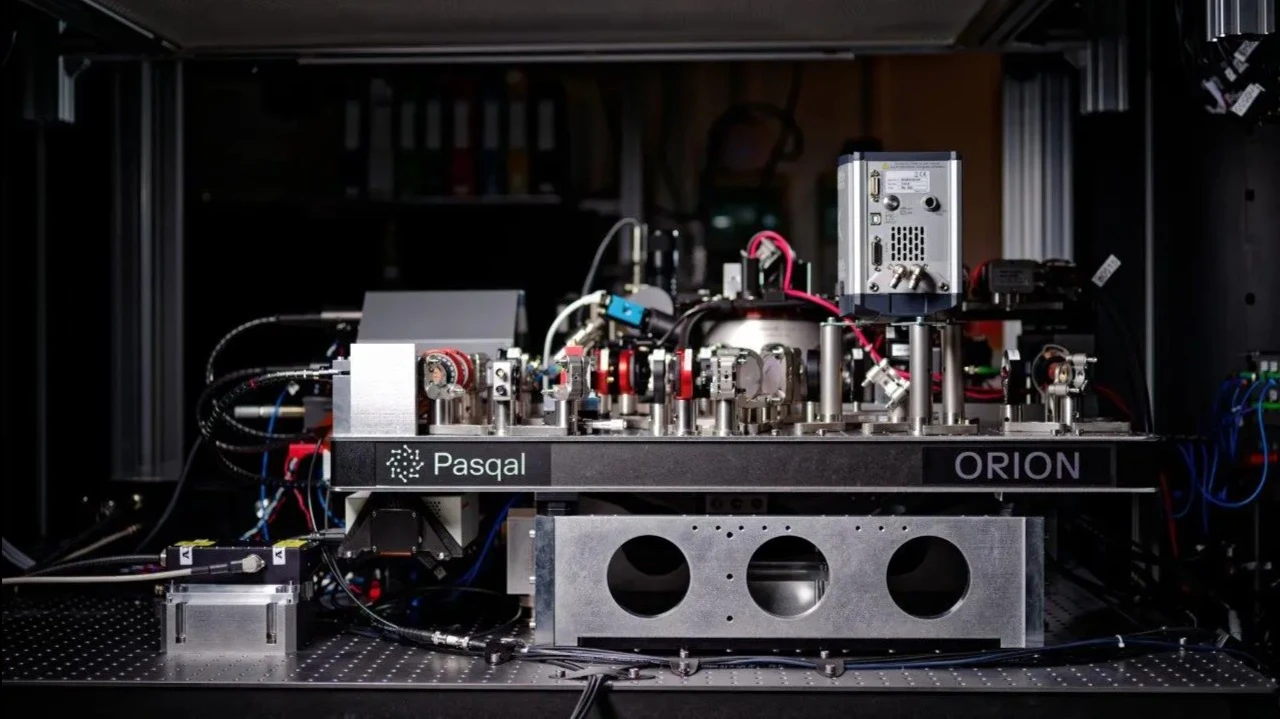
Pasqal went public on the Nasdaq in late August through a blank-check merger / Photo: www.pasqal.com
Shares of French quantum-computer developer Pasqal rose 10.5% on the Nasdaq on Tuesday to $6.84 apiece. StoneX analyst Gary Mobley initiated coverage of the company, which listed on the Nasdaq in August, with a “buy” rating at a target price of $15 per share, implying almost 120% upside from current levels.
About Pasqal
Pasqal develops quantum computers that use individual neutral rubidium atoms as qubits, the basic units of quantum computing. The atoms are trapped and manipulated using lasers. One of the company’s cofounders is Alain Aspect, who shared the 2022 Nobel Prize in Physics for experiments involving quantum entanglement.
Pasqal began trading on the Nasdaq on August 28 following a merger with a SPAC. The stock initially surged, reaching an intraday high of $24.69 per share on August 31, but had fallen to around $6 per share by early October.
What StoneX says
Mobley believes investors should focus less on the stock’s short-term performance and more on the underlying business. He calls Pasqal “one of only a handful of quantum companies generating commercial revenue from systems installed in customer data centers today,” Barron’s reports. Such systems have already been installed and commissioned at major high-performance computing centers, such as CEA’s TGCC in France and Forschungszentrum Jülich in Germany.
Mobley also sees promise in Pasqal’s approach to developing quantum hardware using individual atoms controlled by laser beams. Pasqal likewise says this approach offers advantages when scaling the technology.
Order book
Pasqal reported first-half 2026 revenue of EUR4.87 million, up 14% year over year. Meanwhile, its operating loss tripled to EUR59.2 million, though a significant portion was related to one-time items, including share-based employee compensation and listing costs. Booked and awarded business stood at around EUR70 million as of the end of June.
The strengthening of the commercial order book supports Mobley’s positive view of Pasqal. The commercial order book accounts for EUR37 million of the total, with around EUR12 million expected to be recognized as revenue by the end of 2026, CFO Stéphane Rougeot explained during Pasqal’s first-half earnings call.
What other analysts say
Three analysts initiated coverage of Pasqal in September. On September 30, Needham analyst David Williams gave the stock a “buy” rating at a target price of $16 per share, calling Pasqal “one of the most commercially advanced neutral-atom quantum platforms,” according to Barron’s. Earlier in September, Canaccord and Roth also initiated coverage with “buy” ratings at target prices of $16 and $20 per share, respectively. According to MarketWatch data, Pasqal has four analyst ratings, all of them “buy.” The average target price of $16.75 per share implies 145% upside from Tuesday’s close.