Between Barricades and Investors: Will France Become the New Epicenter of the Eurozone Crisis?
Rising bond yields and political instability are putting France in a situation reminiscent of the eurozone debt crisis

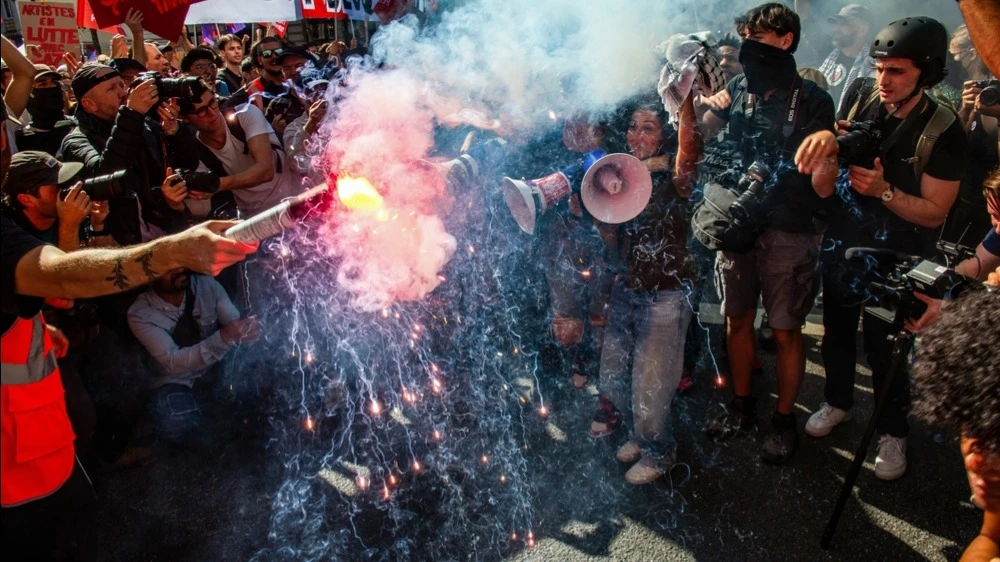
Tensions in France are mounting as the budget standoff intensifies and the presidential election approaches / Photo: Pierre Laborde / Shutterstock.com
Last week’s sell-off of French bonds pushed borrowing costs to nearly 5 percent —a high not seen in nearly a quarter-century. At the same time, France has faced a surge in public discontent that could derail the government’s plans to rein in the budget deficit. Hundreds of thousands of civil servants across France took to the streets to protest spending cuts, and demonstrations by high school students escalated into riots, resulting in the arrest of more than 5,000 people.
France finds itself caught between protesters and so-called bond vigilantes —institutional investors who are selling off government bonds en masse in protest against ineffective fiscal policy, according to the Financial Times. Tensions are mounting as the budget standoff deepens and preparations are underway for the presidential election, in which far-right and far-left forces may face off. Could France slide into a full-blown debt crisis that would shake the eurozone?
"A Slowly Smoldering Crisis"
“We are already in a slow-burning, deep, and structural crisis,” Pierre Moscovici, who served as finance minister at the height of the eurozone crisis in 2012, told the Financial Times. “France is probably too big to fail, but not too big for the market to punish it.”
In just one month, the spread between the yields on 10-year French bonds and German Bunds — a key indicator of investor confidence — has widened by nearly two-thirds, to about 1.4 percentage points, approaching levels seen during the eurozone debt crisis. Not even the release of the draft budget last week—in which the government outlined €43 billion in austerity measures, including limits on pension indexation and a partial freeze on civil servant salaries—was able to halt the sell-off of French debt.
"France seems to be heading down the path to a financial crisis with its eyes closed," says Mike Riddell, a fund manager at Fidelity International. "It looks like the broader market is starting to take notice."
Context
France’s national debt now stands at €3.5 trillion, or nearly 120% of GDP—significantly higher than the eurozone average. Debt servicing costs have become the government’s largest expenditure item, surpassing education and defense. Borrowing now costs France more than it does Italy and Greece. Moreover, according to Goldman Sachs, as of the end of September, more than a quarter of French companies with investment-grade ratings were borrowing at lower rates than the government itself.
During Emmanuel Macron’s nine years in office, France’s national debt has grown by more than one trillion euros: his business-friendly reforms quickly gave way to massive spending to mitigate the effects of a series of crises. After Macron called for early parliamentary elections in 2024, the deadlock in the fragmented parliament turned budget debates into a power struggle that cost two prime ministers their jobs. For the past three years, the budget deficit has remained above 5% of GDP.
Macron is pushing current Prime Minister Sébastien Lecornu to implement sweeping spending cuts to reassure the markets. However, this poses another risk: the harsher and more unpopular the proposed cuts are, the more vulnerable the government becomes to the threat of being ousted by parliament, writes the FT. The French government has constitutional tools at its disposal to push the budget through, but this would provoke sharp discontent from the opposition.
If the government resigns during the budget debates, which could last until the end of the year, a new wave of turbulence in the debt market will be almost inevitable, the FT reports.
The approaching elections are adding to the uncertainty. Polls suggest a possible runoff between far-right candidate Marine Le Pen and far-left candidate Jean-Luc Mélenchon. In an attempt to reassure the markets, Le Pen has promised to cut budget spending by €125 billion and proposed capping public debt at 60% of GDP. However, her campaign platform also calls for lowering the retirement age and reducing the VAT on energy and essential goods, which could increase the debt burden by tens of billions of euros.
Melenchon, for his part, stated that the bonds held by the central bank could be “thrown into the fire”—that is, written off without any consequences. The mere fact that such a radical idea has entered the public discourse has alarmed investors, the FT notes.
What's Next?
Some economists fear that France could find itself caught in a downward spiral: the cost of servicing the debt will continue to rise, widening the budget deficit, and investors will respond with further selling and higher bond yields, the publication reports.
Investors are also beginning to discuss whether the widening of yield spreads between French bonds and those of neighboring European countries will prompt the ECB to intervene. Most believe the central bank will take action if there is a serious “contagion” from France to other European debt markets, the FT reports. Asset management giant Vanguard warned last week that political parties’ “grandstanding” ahead of the election could jeopardize the budget adjustments outlined in Le Cornu’s draft. If that happens, spreads could widen across the entire eurozone.
In such a scenario, the ECB’s ability to buy up massive amounts of bonds could serve as a last line of defense, given that the central bank would not allow a major European economy to slide into a full-blown debt crisis. The ECB has a special emergency bond-purchase tool (TPI) that has never been used. However, its use requires that a country pursue “sound and sustainable” fiscal policy—a criterion that France has so far struggled to meet.
It is impossible to put public finances in order without reducing unemployment and raising the retirement age—measures to which the French are strongly opposed—says Éric Lombard, who served as finance minister last year: “France’s fundamental problem is that we don’t work hard enough”. If more people have jobs and benefits are cut, then “with a bit of luck, we’ll be able to turn things around in five years,” he believes.
Raising taxes could also entail serious risks. The tax burden in France stands at 44% of GDP and is already one of the highest in the world. By comparison, in the OECD—the so-called club of developed nations—this figure averages 34%.
Meanwhile, in Paris, officials are reluctant to overstate the risk that France might face a full-blown debt crisis, the FT reports. “France is not the Greece of the eurozone crisis,” Emmanuel Moulin, head of the Bank of France, told the newspaper. According to him, the adoption of the proposed budget, which includes spending cuts, will reassure the markets. Moulin describes the current situation in the bond market as “serious and alarming,” but believes that France is capable of getting back on track.
“Whoever is elected president will face a situation where interest rates are high, debt service is costly, the deficit must be brought back below 3 percent, and the debt must be reduced,” he said. “If we don’t take action, we really do risk being gradually strangled by rising interest rates.”
This article was AI-translated and verified by a human editor