Burry Compared the Next Crash to a Supervolcano Eruption: 5 Signs for Investors
The legendary short seller believes that the collapse of the favorites in the AI race will present an opportunity for stocks that had already fallen in price before the crisis
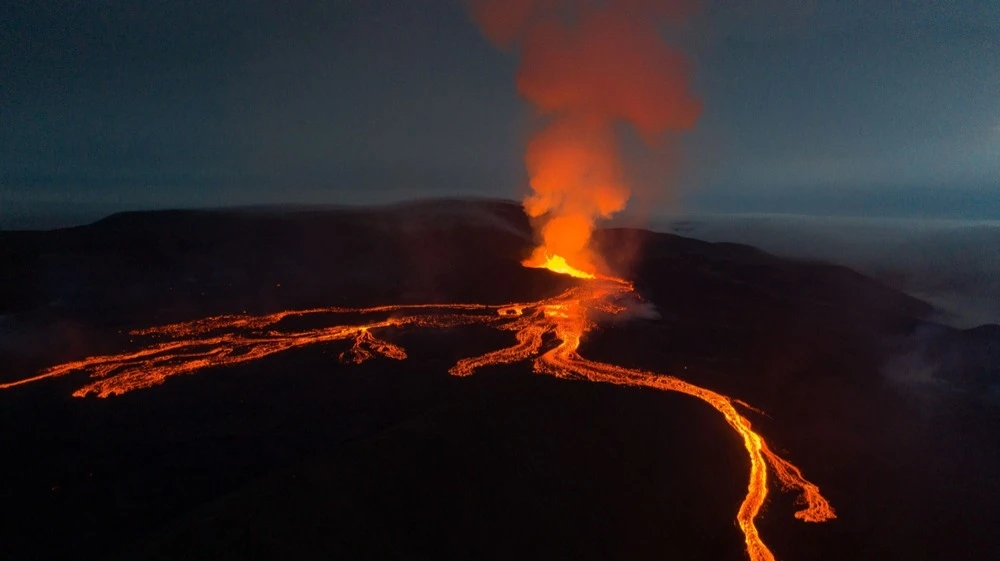
"Right now, the market resembles a maturing supervolcano," writes Burry: on the surface, the situation appears stable, but imbalances are building up beneath the surface / Photo: Shutterstock
Wall Street is threatened by a “supervolcano,” according to Michael Burry, who predicted the collapse of the U.S. mortgage market. Behind the stock market’s outward calm, the investor sees the threat of a crisis that could unfold in an unusual way: a decline in the benchmark S&P 500 index would be accompanied by a rise in stocks that have already experienced a sharp decline.
In early October, Burry had already warned of an imminent market crash and accused investors of ignoring the warning signs. Now, after analyzing ten market peaks over the past 40 years, he has refined his forecast. In his blog, Cassandra Unchained, on Substack, Burry wrote that instead of a sharp crash, the S&P 500 may decline gradually, experiencing sharp drops at times. In his view, financial problems in the AI industry will intensify the pressure on the market. The investor does not know exactly when the downturn will begin, but believes the conditions for it are already in place.
Seismic Hazard
"Right now, the market resembles a maturing supervolcano," writes Burry: on the surface, the situation appears stable, but imbalances are building up beneath the surface. On the surface, the S&P 500 has hit a new record, driven by just a few of the largest companies, while beneath the surface, hundreds of stocks have already lost 10–30% or more from their highs.
“On October 6, only 15 stocks in the S&P 500 hit new highs at the same time as the index itself. And only 97 stocks—a negligible number—were within 10% of their all-time highs. In March 2000, those figures were 15 and 87. The margin of safety here is alarmingly thin.”
Before the dot-com crash, the median stock in the S&P 500 had fallen 31% from its high; now it’s down 22%, writes Burry. However, the situation is rapidly deteriorating: since August, the share of stocks that have lost more than 20% has risen from 47% to 55%. If this trend continues, market indicators could reach—and even exceed—2000 levels in the coming months.
"The problem is that we don't know exactly where we are on the timeline. Maybe we're just at the very beginning of the journey. Maybe the process has been going on for four months already. Or maybe it's been seven months, and it could take off at any second."
What Will the Next Bear Market Be Like?
Burry illustrates just how widely the performance of current market leaders and stocks that have already fallen in price can diverge, using the year 2000 as an example. In the 12 months following the March peak of the S&P 500, the former market leaders lost a median of 33%, while stocks of companies that were already in a “bear market” rose 14%. A year and a half later, the leaders’ losses reached 50%, while stocks that had previously fallen remained 8% above their March levels.
Burry suggests that the first signs of such a leadership shift may appear even before a general market decline. In 1998, two years before the dot-com crash, stocks that had previously fallen in price rose by 7%, while market leaders rose by only 4%. Investors observed something similar in early 2025: following the release of an AI model by the Chinese startup DeepSeek, tech stocks plummeted, while some stocks that had previously lost value posted higher returns.
This time, pressure on major companies may intensify due to financial problems in the AI industry. Among the warning signs, Burry cites the quality of corporate earnings, off-balance-sheet liabilities, supply chain risks, and businesses’ dependence on external financing. He considers the possible weakening of the “mechanical flow” of money into the stocks of the largest companies—which is currently propping up the market—to be an additional risk factor.
“All of this suggests that the market will crash according to a scenario that will drive up the median ‘broken’ stock (the average stock among those that had fallen by more than 20% before the crisis began — Oninvest). This is my base-case scenario. The market may not collapse overnight in a single devastating crash, but will slide lower and lower, occasionally making sharp downward lurches as fundamental news from the world of contracting multiples and margins breaks through the prevailing narrative surrounding AI.”
Burry fears that halting a protracted decline will be more difficult than previous crashes. In his view, the support measures that help during sharp price drops may prove less effective if companies’ financial positions and market conditions continue to deteriorate gradually. Furthermore, following previous crises, the U.S. government’s ability to support the economy has been significantly reduced. If the private debt bubble bursts, it will be more difficult for the government to mitigate the consequences.
The Five Laws of a Bear Market
After studying the dynamics of ten financial crises, Burry identified five key rules for market reversals:
The index can hit new record highs even as most stocks are already falling. Gains by the largest issuers are keeping the S&P 500 at record highs, even when more than half of its constituent stocks are already trading deep in the red. Historically, this is an anomaly: According to Burry’s calculations, during typical market peaks over the past 40 years, only 20–31% of stocks fell more than 20% below their highs, whereas today that share has exceeded 50%, matching the level seen in March 2000.
2. The rising proportion of falling stocks is a warning sign. The investor cites 1995 as an example: at that time, the S&P 500 reached a new high, even though 46% of its constituent stocks were down more than 20%. However, at that time, this proportion was steadily declining, which allowed the market to continue its multi-year rally. Today, the situation is reversed: the pool of stocks down more than 20% has already exceeded 50% and continues to expand as the index rises—for Burry, this is the primary indicator of a deterioration in market structure.
A market decline does not necessarily mean that all stocks will fall. An analysis of ten market downturns over the past forty years showed that, during most crises, stocks that had already fallen in price continued to decline faster than the market, losing an average of up to 40% more. However, Burry pointed out one exception—the dot-com crash of 2000. At that time, 12 months after the market peak, the index leaders plummeted by 33%, while the median “battered” stock rose by 14%. Even a sharp decline in the S&P 500 can be accompanied by net gains in sectors that have been overlooked by the market.
Leaders in an overheated market may take years to recover. After the dot-com crash, many companies that had previously driven the growth of the S&P 500 were unable to return to their previous highs for a long time. Some of them had not recovered by the start of the 2008 financial crisis. “When truly massive bubbles burst, their leading stocks can plummet and remain at rock bottom for a very long time. Japan may have created the largest bubble of the modern era, and we all know very well how that ended: decades of stagnation for the largest corporations,” writes Burry.
The market may fail to generate returns for decades. Following major crashes, the U.S. market has sometimes taken decades to return to its previous levels, adjusted for inflation. Burry cites three such periods: 1929–1949, 1966–1982, and 2000–2011. However, reinvesting dividends significantly reduced losses and, in some cases, allowed investors to achieve positive returns even after adjusting for inflation.
This article was AI-translated and verified by a human editor