Strategist picks three small caps bucking the Russell 2000 slump
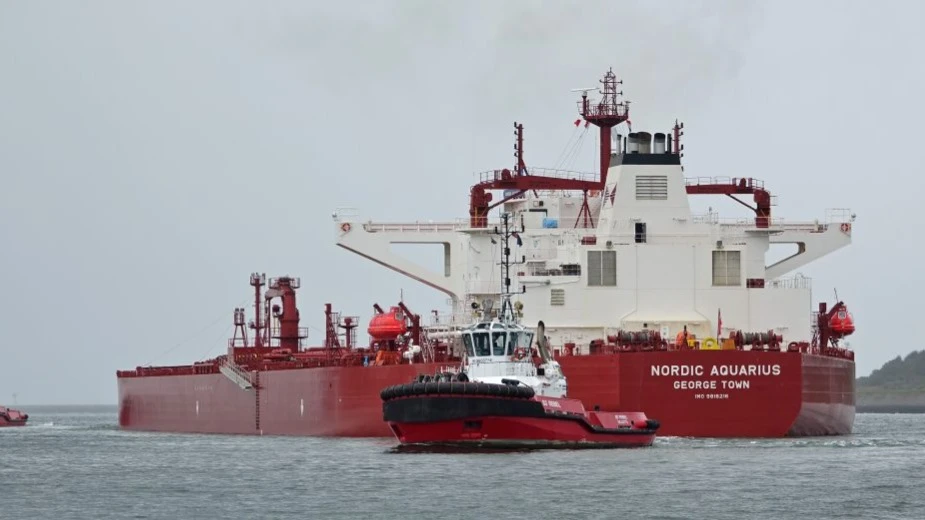
Nordic American Tankers, with a market capitalization of $1.67 billion, owns and operates a fleet of large crude oil tankers / Photo: www.nat.bm
The Russell 2000 index, which tracks smid-cap stocks, entered correction territory this week after falling 11% from its recent high. Yet three small caps with strong fundamentals have managed to outperform the market, Seeking Alpha’s head of quantitative strategies, Steven Cress, writes.
He recommends buying the names, arguing that the recent broad pullback could create opportunities for investors. He cautions, however, that despite their significant upside, small caps are not for everyone because of their higher volatility and risk. Here are Cress' picks.
Fortrea Holdings (FTRE)
Fortrea, a contract research organization with a market capitalization of $2.16 billion, conducts clinical trials for other pharmaceutical companies. Its stock has gained 15.3% over the last month, versus a 3.4% decline for the Russell 2000.
Fortrea works across 20 therapeutic areas, including oncology, immunology, rare diseases, and cardiovascular disorders. Its scale, flexibility, and specialization in early-phase research give it an edge over competitors, Cress notes.
Second-quarter revenue fell 4.5% year over year to $678.2 million. Cress, however, highlights another metric: adjusted EBITDA rose 7% to $58.7 million. Net new business increased 19% year over year in the first half, prompting the management to raise its full-year guidance, he adds. He believes improving margins and a strong long-term outlook make Fortrea a compelling "buy."
According to MarketWatch data, the stock has five “buy,” two “overweight,” five “hold,” one “underweight,” and one “sell” rating from Wall Street analysts. The average target price is $22.18 per share, slightly below the last close.
Riley Exploration Permian (REPX)
Riley, with a market capitalization of just over $1 billion, specializes in horizontal drilling in the U.S. Permian Basin. Higher oil prices and rising production have driven substantial growth in cash flow and earnings, Cress writes.
Higher oil prices helped lift Riley’s second-quarter operating cash flow 35% quarter over quarter to $63.5 million. Revenue, meanwhile, rose 94% year over year to $166 million. Citing strong output, production enhancement projects, and improving drilling efficiencies, the management raised its full-year oil production guidance by 2% and is now targeting 23,000 barrels per day, up 30% versus last year, Cress notes.
The strong financial results have been reflected in the stock price, which is up 79% year to date and around 5% over the last month. The stock has five Wall Street ratings, all of them “buy.” The average target price is $52.40 per share, implying 11.5% upside from the last close. Dividends are another plus for the name, according to the Seeking Alpha article. Riley has paid them every quarter since going public in 2021, and its forward dividend yield is 3.45%.
Nordic American Tankers (NAT)
Shipping company Nordic American Tankers, with a market capitalization of $1.66 billion, owns and operates a fleet of large crude oil tankers. Its customers include oil giants ExxonMobil, Shell, and BP. Cress believes the company is positioned to continue benefiting from record freight rates as the Middle East conflict disrupts established shipping routes and constrains vessel availability.
NAT is operating in the best market it has seen in decades, and although only half of 2026 had elapsed, the year promised to be its best since going public in 1995, the company stated in its second-quarter earnings release. Its vessels were earning $60,000-90,000 per day in the spot market, while daily operating costs were below $10,000. That was generating substantial cash, with the balance reaching $175 million. Cress singles out the company’s profitability: Its levered free cash flow margin of around 20%, versus a sector median of 6%, is particularly impressive, he writes.
The stock has surged more than 127% this year. Its performance also stands out over a longer period, the Seeking Alpha article notes: over the last five years, NAT has delivered exceptional total returns on the back of strong share-price gains and substantial dividends. The company has paid dividends for 28 consecutive years.
Over the two trading days since Tuesday, the stock tumbled 11% to $7.82 per share, potentially creating an opportunity to buy the dip, Cress notes. Wall Street broadly shares his view. The stock has three “buy” ratings versus one “sell” recommendation. The average target price of $7.50 per share is below the current market price.
Cress' methodology
Cress selected stocks that consistently received "buy" recommendations and scored highly across the five factors assessed by Seeking Alpha’s proprietary stock screener. Three of them – value, which assesses valuation using several multiples relative to peers; growth, which measures earnings growth; and profitability, which evaluates margins – help identify high-quality, undervalued companies. The other two – momentum, which assesses stock performance, and EPS revisions, which tracks changes to analyst estimates – help identify the best time to buy. Cress then focused on stocks that had outperformed the Russell 2000 since August 14, when the small-cap benchmark peaked.