Freedom sees 24% upside for coffee machine maker De’Longhi on commercial sales growth
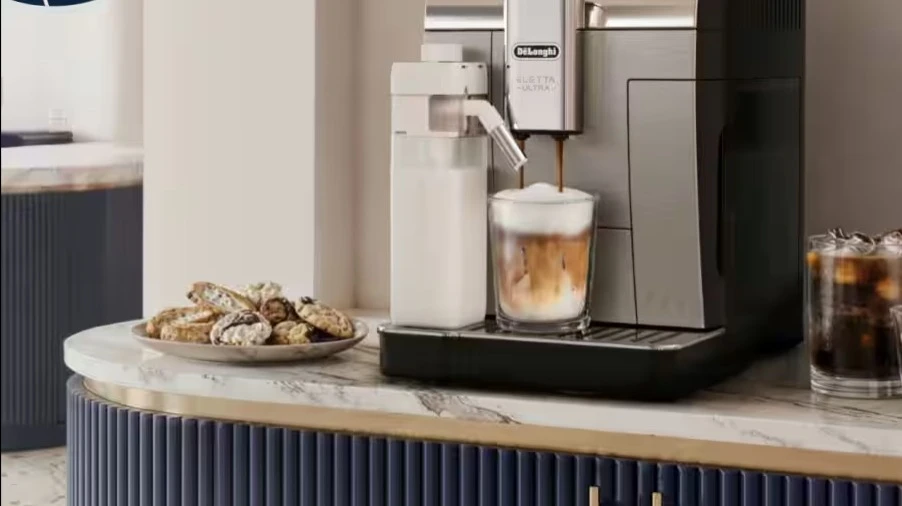
De’Longhi is up 20% year to date and almost 40% over the last 12 months / Photo: www.delonghi.com
Shares of Italian coffee machine maker De’Longhi could rise by almost a quarter in the next 12 months, Freedom Broker analyst Michael Chistyakov argues in a new investment idea. He is betting on the company’s fast-growing coffee shop equipment business and a recovery in household appliance sales.
Details
Chistyakov recommends buying De’Longhi stock, with a 12-month target price of EUR54 per share, implying almost 24.5% upside from the Friday close.
De’Longhi makes home coffee machines under its namesake brand, professional coffee equipment under the Eversys and La Marzocco brands, and kitchen and other household appliances. Its coffee business accounted for 68.6% of group revenue in 2025. Europe is the company’s largest market, generating 61.8% of sales.
Professional coffee machines are central to Chistyakov’s investment case for De’Longhi. In the first half of 2026, revenue at the Professional division rose 36.3% year over year to EUR302.8 million. Its adjusted EBITDA margin was 32%, versus 13.5% for the Household appliance division.
Faster growth in the professional business could support margins across the group, Chistyakov believes. Eversys is winning large orders from coffee shop chains, while both professional brands are expanding sales internationally. He also sees opportunities in La Marzocco’s high-end home coffee machines. De’Longhi’s management expects Professional division revenue to exceed EUR600 million in 2026.
Another factor is De’Longhi’s increased stake in the Professional division. In October, the company agreed to buy DLI Limited’s stake for EUR662.5 million, thus increasing its ownership from 61.56% to 88.02%. This will allow De’Longhi to retain a larger share of the business’ profit, while its results are already fully consolidated in the group’s financial statements, Chistyakov explains.
Household appliances
Household sales are returning to growth after a weak start to the year, when retailers were reducing inventories. The division’s revenue rose 4.5% year over year in the second quarter and 1.2% in the first half. Chistyakov sees new coffee machine models, a broader range of accessories, and brand promotion driving further growth. The group’s advertising and promotion spending rose 8.4% to EUR199.8 million in the first half.
Meanwhile, weak U.S. demand for NutriBullet blenders is weighing on kitchen appliance sales. Chistyakov also cites competition, U.S. tariffs, and currency fluctuations as risks.
For full-year 2026, De’Longhi’s management forecasts revenue growth of around 5% and adjusted EBITDA of EUR670-690 million. The higher profit guidance incorporates around EUR15 million in tariff refunds.
What other analysts say
Of the 10 analysts covering the stock, eight have the equivalent of a “buy” rating and two rate it a “hold.” The average target price is EUR48.90 per share, implying 12.7% upside from the last close.