Wall Street is split on Meta’s outlook. Should investors buy the current dip?
Meta’s market capitalization has fallen 9% in five trading days / Photo: PJ McDonnell / Shutterstock.com
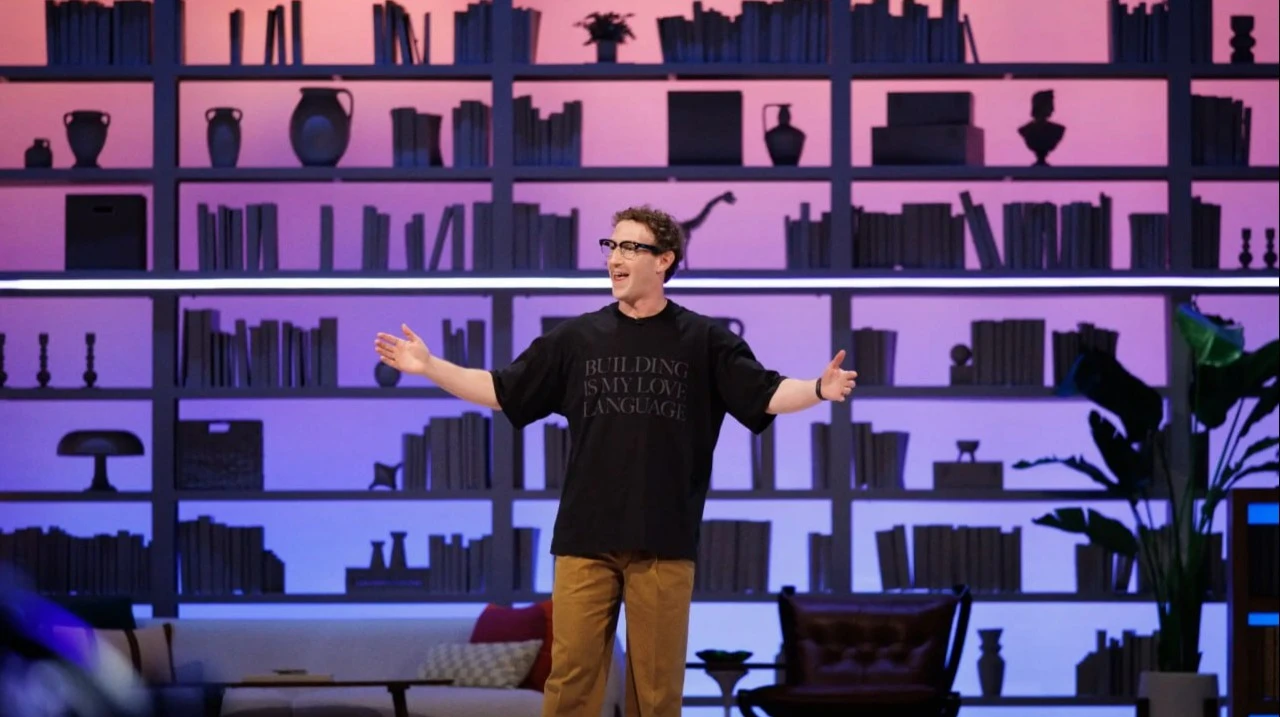
Meta Platforms, the developer of AI agent Muse and the owner of Facebook and Instagram, fell 0.6% on Friday to $644.80 per share after plunging 7% the previous day following its third-quarter earnings report. The company’s market capitalization has fallen 9% in five trading days.
Wall Street is divided on Meta’s outlook following its latest results: some analysts see the company as the clear leader in consumer AI thanks to Muse, while others remain cautious and advise investors to hold off on buying the stock, Barron’s writes.
What Wall Street says
Morgan Stanley: Thanks to Muse’s success, Meta now has the clearest winner among consumer generative AI products, argues Morgan Stanley analyst Brian Nowak. He has an “overweight” rating on the stock at a target price of $820 per share, Barron’s writes. That implies 26% upside from Thursday’s close.
More than 10 million users in the U.S. and Canada downloaded the Muse app in its first six weeks, Meta stated. Around 25% of them, or 2.5 million people, use the service daily. In addition, more than 25% of weekly active users shop through Muse, with an average purchase amount exceeding $200.
“We see this high commercial intent as encouraging for Muse’s longer-term monetization potential, particularly given META’s existing relationships with around 500 million businesses,” Nowak wrote.
BofA: Analyst Justin Post described Muse’s growth as “open ended.” He has a TP of $845 per share on Meta, Barron’s writes, implying 30% upside from Thursday’s close. In Post’s view, investors can now be more comfortable with Meta’s rising AI spending as the commercial opportunities for its new products become clearer. “While costs to provide AI services will also be increasing, we think the Street will look more favorably on investment now that product opportunities are more visible,” the analyst wrote.
UBS: The investment bank raised its TP on Meta from $884 to $892 per share, implying 38% upside from Thursday’s close. Meanwhile, it kept its “buy” rating, Investing.com reports. The bank believes Meta is entering a period when three years of heavy capex on frontier AI models is beginning to pay off, primarily through improvements in its advertising business and faster adoption of its AI products.
UBS believes optimized versions of Muse could further improve ad targeting and content recommendations, creating upside to its current revenue forecasts for Meta in 2027 and 2028. Another positive is Meta’s intention to begin monetizing Muse faster than its previous major products, which typically took around four years to develop. That means revenue growth could accelerate sooner. Following Meta’s earnings report, UBS raised its revenue forecasts for 2027 and 2028 by around 1% and 2%, respectively, while noting that further adoption of Muse could provide additional upside.
Needham: Analyst Laura Martin acknowledges Muse’s strong start but maintains a neutral stance on the stock. Her main concern is Meta’s capital structure rather than Muse itself. The company stated that it would issue nonvoting Class C shares to Class A and Class B shareholders in January, effectively amounting to a 2-for-1 stock split. “We recommend investors stay on the sidelines,” Martin advised, until the equity offering. In her view, the move could signal that Meta is preparing to raise around $100 billion through an equity offering in the first half of 2027 “as it nears its debt ceiling.” Martin also sees intensifying competition between Muse and other AI agents as a risk.
What's the consensus?
Wall Street is reassessing Meta Platforms after the management raised the lower end of its capex guidance on Wednesday and the company announced plans to create a new class of nonvoting shares, further expanding its already enormous AI investments. Currently, 62 of the 69 analysts covering the tech giant recommend "buy," six have “hold” ratings, and only one advises "sell." The average target price of $846 per share implies 30% upside from Thursday’s close.