"The Music's Still Playing": What Wall Street Recommends Doing with Meta Shares Ahead of the Earnings Report
90% of analysts recommend buying the stock, and the most optimistic forecast predicts a 50% increase in its price over the next 12 months

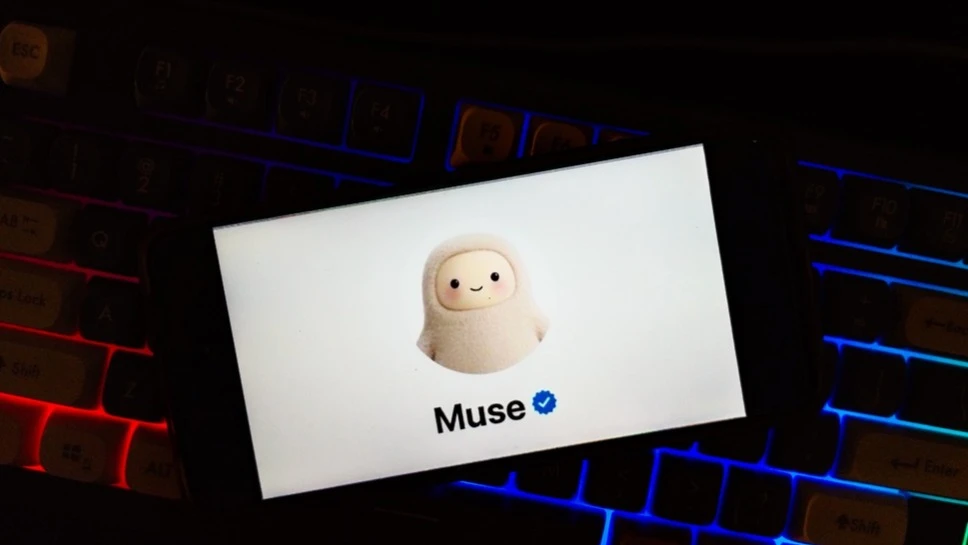
The AI assistant Muse AI reached 10 million downloads in just 40 days after its launch, surpassing ChatGPT and Claude / Photo: Erlin Diah / Shutterstock.com
Meta Platforms will be one of the first major tech companies to report its third-quarter results. The report, which will be released after the market closes on October 21, will either ease investors’ concerns about the artificial intelligence market overheating or, conversely, heighten their anxiety, according to Bloomberg. What are analysts saying ahead of the report, and what do they recommend doing with Meta shares?
— According to the Bloomberg consensus estimate, Meta is expected to report earnings of $3.56 per share on revenue of $63.3 billion in the third quarter. By comparison, during the same period last year, the company earned $1.05 per share on revenue of $51.2 billion. Meanwhile, capital expenditures are expected to more than double, reaching $41 billion.
— Over the past 12 months, Meta’s stock has fallen by more than 5%—a sign that Wall Street is waiting for greater clarity on how the company intends to monetize its massive investments, according to Yahoo Finance. However, Meta has also achieved a number of successes in recent weeks. Analytics firm Sensor Tower reported that the new AI assistant, Muse AI, reached 10 million downloads in just 40 days after its launch in the U.S. By comparison, OpenAI’s ChatGPT and Anthropic’s Claude took 123 and 673 days, respectively, to reach that milestone.
— “A strong earnings report from Meta would bolster investor confidence and could reignite interest in artificial intelligence investments, easing concerns about demand across the entire industry, — Andrew Wang, managing partner at Runnymede Capital Management, which holds Meta shares, told Bloomberg. “If, on the other hand, Meta’s earnings report raises concerns, it will cast an even darker shadow over the outlook for the entire sector.” Van believes Meta’s current valuation is justified: while he is not ready to call the company’s stock “an unqualified buy,” he believes it looks attractive if the expected financial results prove to be sustainable.
— “The AI sector is still on a roll, but investors are losing patience,” says Max Stamakun, Chief Investment Officer at Israilov Financial. “If Meta’s results disappoint the market, this could amplify existing concerns and negatively impact investor sentiment.” However, Stamakun does not expect Meta to be “the first domino to fall, triggering a chain reaction” in the market.
— The launch of the Muse Spark AI model— one of Meta’s biggest releases in recent years—has allowed the company to “go on the offensive again in the AI space,” noted Bank of America analysts Justin Post and Nitin Bansal. They recommend buying the stock with a price target of $810 (17% above the current level), noting that Muse’s success could lead to an increase in the company’s market valuation. However, according to Post and Bansal, there are certain risks for Meta: download rates and user activity could slow down, and Google could launch a competing AI assistant that would take market share away from Meta.
— Meta was once considered a laggard in the field of artificial intelligence, but today its initiatives are taken more seriously than ever before, Truist analysts noted in a recent report. “We believe that, in the long term, Meta will be among the winners in the AI race,” they write.
— A few days before the earnings report, Brian Novak of Morgan Stanley raised his price target for the stock from $775 to $820, maintaining an “Overweight” rating, which is equivalent to a “buy” recommendation. In his note, the analyst noted that he is optimistic about the prospects for the AI assistant Muse, but urges investors to assess the pace of the technology’s adoption “realistically,” according to Barron’s.
— Despite Muse’s strong download figures, its daily active user and user retention metrics still lag behind those of Instagram and Facebook, according to Morgan Stanley analysts. “We’ve already seen Meta launch products that failed to meet market expectations (Facebook Shopping, the metaverse, Meta AI, and others). Therefore, we believe the market will need convincing signals regarding Muse’s adoption rate and the development of monetizable user behavior before investors revise their valuation of the company’s stock upward,” Morgan Stanley analysts wrote in a note shortly after Muse’s launch.
— BMO Capital analyst Brian Pitz assigned Meta shares the lowest price target on Wall Street—$580—and a “Hold” rating. “While improvements to Muse and AI models have somewhat strengthened our positive view on the commercialization of AI products, we expect clear evidence of how these initiatives translate into revenue, as well as greater clarity regarding expense trends in 2027,” he said.
Overall, out of the 69 analysts covering Meta, only one recommended that investors sell the stock, according to MarketWatch data. 90% of analysts assigned a “buy” or equivalent rating to the stock. The average price target implies a 20% increase in Meta’s stock price over the next 12 months, while the most optimistic forecast calls for a 50% rise to $1,050.
This article was AI-translated and verified by a human editor