France caught between bond market and barricades as debt fears mount
Surging borrowing costs and political instability have fueled fears of a debt crisis that could shake the euro zone

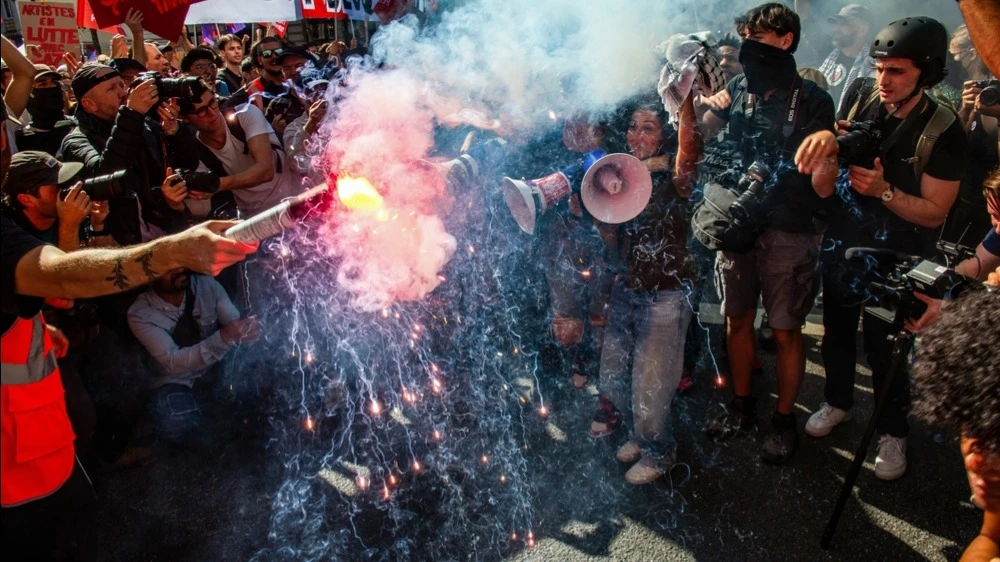
The risk perception on French debt is deteriorating as a budget standoff intensifies and the next presidential election approaches / Photo: Pierre Laborde / Shutterstock.com
A selloff in French bonds last week pushed borrowing costs close to 5%, the highest in almost a quarter of a century. At the same time, France has faced a surge in public anger that could derail the government’s plans to rein in its fiscal deficit. Hundreds of thousands of public-sector workers took to the streets across France to protest spending cuts, while demonstrations by high school students descended into unrest that led to more than 5,000 arrests.
France is caught between protesters and so-called bond vigilantes – institutional investors who dump government bonds en masse to protest against ineffective fiscal policy, the FT writes. Tensions are rising as the confrontation over the budget deepens and the country prepares for an April 2027 presidential election that could come down to the far right against the far left. Could France tip into a full-blown debt crisis that shakes the euro zone?
‘Slow-burning crisis’
“We are already in a slow-burning, deep and structural crisis,” Pierre Moscovici, who served as finance minister during the tail end of the eurozone crisis in 2012, told the FT. “France is probably too big to fail, but it is not too big for the markets to punish.”
In just one month, the yield spread between 10-year French government bonds and German bunds, a key gauge of investor confidence, has surged by almost two thirds to around 1.4 percentage points, approaching levels last seen during the eurozone debt crisis. The selloff in French debt last week continued even after the government unveiled a draft budget envisaging EUR43 billion in austerity measures, including curbs on pension increases and partial freezes on civil servant salaries.
“France has been sleepwalking down the path that leads towards a financial crisis,” says Mike Riddell, a fund manager at Fidelity International. “It feels like broader markets are starting to notice.”
Context
France’s public debt now stands at EUR3.5 trillion, or almost 120% of GDP, which is far above the eurozone average. Servicing the debt has become the government’s largest expenditure, surpassing spending on education and defense, for example. France now pays more to borrow than Italy and Greece. Moreover, according to Goldman Sachs, more than a quarter of investment-grade French companies were borrowing at lower rates than the government as of the end of September.
French public debt has risen by more than EUR1 trillion during Emmanuel Macron’s nine years as president: his business-friendly reforms quickly gave way to massive spending to cushion the impact of a succession of crises. Since Macron called a snap parliamentary election in 2024, gridlock in the hung parliament has turned budget debates into trench warfare, costing two prime ministers their jobs. The budget deficit has remained above 5% of GDP for the last three years.
Macron has been urging current Prime Minister Sébastien Lecornu to make sweeping spending cuts to calm the markets. But this presents another risk: the larger and more unpopular the proposed cuts, the more vulnerable the government is to being toppled, the FT notes. The French government has constitutional tools that would allow it to force the budget through, but using them would inflame the opposition.
Another wave of turbulence in the debt market will be all but certain if the government collapses during budget debates that could last until the end of the year, the FT writes.
The approaching election is adding further uncertainty. Polls point to a possible second-round runoff between the far-right Marine Le Pen and the far-left Jean-Luc Mélenchon. Seeking to reassure the markets, Le Pen has promised EUR125 billion in spending cuts and proposed capping public debt at 60% of GDP. But her election platform also calls for lowering the retirement age and cutting VAT on energy and essential goods, which could add tens of billions of euros to the debt burden.
Mélenchon, meanwhile, has said that bonds held by the central bank could be thrown “into the fire.” Investors were alarmed that such a radical idea had even entered the public debate, the FT notes.
What's next
Some economists cited by the FT fear France could enter a vicious spiral: debt-servicing costs would continue to rise, widening the budget deficit, and investors would respond with further selling that pushes bond yields even higher.
Investors are also beginning to debate whether widening yield spreads between French bonds and those of neighboring European countries could prompt the ECB to intervene. Most believe the central bank would be particularly likely to act in the case of serious contagion from France to other European debt markets, the FT writes. Asset-management giant Vanguard warned last week that “grandstanding” by political parties ahead of the election could threaten the fiscal adjustment outlined in Lecornu’s budget proposals. Spreads could then widen across the euro zone.
In such a scenario, the ECB’s capacity to buy huge quantities of bonds could provide the ultimate backstop, given that the central bank would not allow a major European economy to tip into a full-blown debt crisis, the FT writes. The ECB has a special emergency bond-buying tool, the Transmission Protection Instrument, that has never been used. But it can only be deployed for countries that pursue “sound and sustainable fiscal and macroeconomic policies,” a criterion France may struggle to meet.
There is no way to repair France’s public finances without reducing unemployment and raising the retirement age, measures that the French firmly oppose, says Eric Lombard, who served as finance minister last year. “The fundamental problem in France is we don’t work enough.” If more people are employed and benefits curtailed, then with “a bit of luck in five years we can turn things around,” he reckons.
Raising taxes could also carry serious risks. France’s tax burden is already among the highest in the world at 44% of GDP. By comparison, the average in the OECD, the so-called club of rich countries, is 34%.
In Paris, officials are playing down the risk that France could face a full-blown debt crisis, the FT writes. “France is not Greece during the eurozone crisis,” Bank of France Governor Emmanuel Moulin told the publication. He said passing the proposed budget containing spending cuts would reassure the markets. Moulin calls the current turmoil in the bond market “serious and worrying,” but believes France can get back on track.
“Whoever is elected president will face a situation in which interest rates are high, the cost of servicing the debt is high, the deficit has to be brought back below 3%, and the debt has to be cut,” he said. “If we don’t act, there is indeed a risk of being gradually strangled by rising interest rates.”