Morning in New York: Inflation Expectations in the Spotlight
Photo: X / NYSE
A daily review and forecast of events in the U.S. stock market by Mikhail Denislov, Deputy Director of Capital Markets Research at Freedom Broker.
We expect
Market trends on the stock exchanges during the upcoming session will continue to be driven primarily by developments in the bond market. Yesterday, the intraday yield on 10-year Treasuries reached 5.22%, a high not seen since 2007, while the yield on 30-year Treasuries came close to its 2004 peak at 5.5%. Futures price in a roughly 70% probability of a Fed rate hike in October. At the same time, the regulator is projected to make approximately four such rate hikes by the end of 2027. Thus, the “hawkish” scenario is already priced in. If the University of Michigan’s final inflation expectations reading matches the preliminary figure of 4.6%, pressure on the long end of the Treasury yield curve may ease. An upward revision of the figure, on the other hand, would intensify that pressure.
Speeches by John Williams, president of the New York Fed, and Beth Hammack, president of the Cleveland Fed, will provide additional guidance. Both adopted a hawkish tone yesterday, which the market has already priced in. In our view, any hint of a pause in the cycle of monetary tightening following the October meeting would be a positive surprise.
At 8:30 a.m. Eastern Time (ET), data on durable goods orders for August will be released (July: +1.1%). At 10:00 a.m. ET, the University of Michigan’s final Consumer Sentiment Index for September will be released (preliminary reading: 47.8 points). The inflation expectations component will be the most significant for the market. According to preliminary data, one-year inflation expectations rose from 4% to 4.6%, while five-year expectations reached 3.4%.
The foreign policy landscape remains mixed. According to Reuters, the U.S. and Iran are discussing a phased resolution to the situation. In theory, Tehran is ready to open the Strait of Hormuz in exchange for the lifting of the U.S. economic blockade and the unfreezing of assets; however, the parties disagree on the sequence of steps. Meanwhile, state television in the Islamic Republic has denied the Reuters report. Saudi Arabia reported that it had intercepted ballistic missiles fired at the port of Yanbu on the Red Sea. Against this backdrop, WTI crude oil prices rose 2.7% the previous day, although they closed below their intraday highs.
Talks between Donald Trump and Xi Jinping at the White House did not result in any concrete agreements. Xi called on Washington to oppose Taiwanese independence, but the State Department does not support this position. According to media reports, a deal on the supply of Boeing aircraft is becoming increasingly unlikely.
S&P 500 futures are trading in a moderately positive range. We assess the risk balance for the upcoming session as neutral, with moderate volatility. The market is being supported by hopes for a deal with Iran, stability in the labor market, and interest in AI sector leaders. Pressure on stock prices is coming from Treasury yields reaching multi-year highs, weak demand at Treasury auctions, companies entering a period of restrictions on share buybacks, and the positioning of systematic funds, which points to downside risk. Consumer inflation expectations and the reaction of 10-year Treasury bonds to them will be key factors.
What to Look for in the Pre-Market
— Akamai Technologies (AKAM) shares soared 23% after signing a seven-year, $11.6 billion contract with Anthropic. The company will provide the AI developer with cloud computing power for CPU-based tasks. The agreement allows for an extension of up to an additional $9 billion, bringing the total to approximately $20 billion, and Anthropic received a warrant to purchase up to 5% of Akamai’s shares at $111.33 per share. Capital expenditures for the project through 2028 will total about $5.5 billion. The surge in buying activity in AKAM shares is also due to a low base: during the main trading session, they fell by 7%.
— Costco (COST) shares are trading near their closing level following the release of its fourth-quarter earnings report. Revenue of $95.72 billion exceeded expectations of $94.85 billion, and EPS came in at $6.75 versus a consensus estimate of $6.52–6.55; however, $0.15 of that EPS was attributable to one-time refunds of import duties.
— Zscaler (ZS) shares fell 3% following the announcement that Mike Rich was stepping down as chief commercial officer for personal reasons. Effective October 1, Ross Takett, head of global sales, will take his place, while Rich will remain a strategic advisor through the end of the year. In our view, the market’s reaction reflects concerns about continuity in sales.
— Atlas Energy Solutions (AESI) shares rose 4% following the announcement of contracts to purchase equipment for an energy project. The agreements call for $340.5 million for the plant’s support infrastructure and $273 million for 328 MW of generating capacity.
— Select Water Solutions (WTTR) shares rose 7% on news of an agreement to acquire Pilot Water Solutions for $700 million in a cash-and-stock deal. The asset in the Delaware Basin is expected to generate $120–130 million in adjusted earnings before interest, taxes, and depreciation (EBITDA) in 2027, and net debt after the transaction closes will remain below 2x.
The Market on the Eve of...
Trading on September 24 on U.S. stock exchanges ended with mixed results. The S&P 500 fell a marginal 0.02%, while the Nasdaq-100 rose a symbolic 0.01%. The Dow Jones fell 0.31%, marking its third consecutive session of declines, while the Russell 2000 lost 0.11%. The indices recovered from their morning losses following reports of U.S.-Iran negotiations. Treasury yields rose as the yield curve steepened: the 2-year yield increased by 3 basis points, and the 30-year yield by 9 basis points. The dollar index rose 0.2%, while gold fell 0.5%.
A small group of stocks kept the S&P 500 steady. The telecommunications sector (XLC: +1.92%) and the healthcare sector (XLV: +0.65%), supported by pharmaceutical companies and life sciences firms, and the energy sector (XLE: +0.43%), which was driven by another spike in oil prices. Interest-rate-sensitive utility providers (XLU: −1.02%) and the real estate sector (XLRE: −0.37%) underperformed the market. Materials (XLB: −1.01%) and consumer staples (XLP: −0.97%) also ranked among the underperformers. Industrial (XLI: −0.71%), transportation, and logistics companies lost ground due to rising fuel prices. The IT sector (XLK: −0.32%) also ended the day in the red.
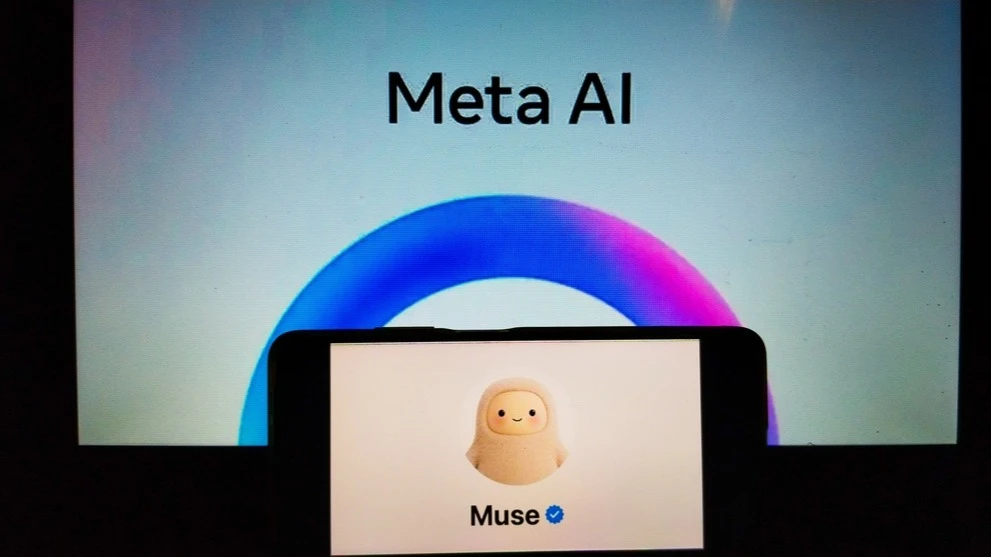
Meta Platforms (META: +4.5%) made a positive contribution of 11 basis points to the broad market index’s performance. At the Connect conference, the company unveiled Muse Charm —a pocket-sized device that allows users to interact with the Muse AI agent without opening the app. Analysts viewed the download trends for this AI model and user engagement positively. Alphabet (GOOGL: +1.34%) contributed 4 basis points to the S&P 500 on news of the imminent launch of its flagship Gemini 4 model. Eli Lilly (LLY: +2.68%) and AMD (AMD: +2.38%) each added 4 basis points to the benchmark.
Memory manufacturers' stocks fell, while chipmakers' stocks traded in mixed directions. The broad market index was primarily weighed down by the largest technology companies. Nvidia (NVDA: −0.41%), Broadcom (AVGO: −1.30%), and Microsoft (MSFT: −0.53%) each subtracted 3 basis points, while Apple (AAPL: −0.33%) and Walmart (WMT: −2.66%) each subtracted 2 basis points. Oracle (ORCL: −3.5%) dampened sentiment in the AI sector: according to Bloomberg, the company cited force majeure regarding its data center project in New Mexico in an effort to defer payments. Investors’ focus has shifted to the risks associated with financing AI infrastructure.
Among corporate news, Everpure (P: +11.2%) stood out after it released a preliminary forecast for fiscal year 2028 during an analyst call that exceeded market expectations. MGM Resorts (MGM: −11%) shares plummeted after Barry Diller’s People Inc. withdrew its buyout offer of $48.30 per share.
The macroeconomic data came in strong. Initial jobless claims fell to 197,000, compared with a consensus estimate of 201,000, remaining near three-year lows. New home sales in August rose to 684,000 on an annualized basis, compared with an average consensus estimate of 620,000.
John Williams, president of the Federal Reserve Bank of New York, said it was reasonable to expect another rate hike this year, while Anna Paulson, president of the Federal Reserve Bank of Philadelphia, cited the development of AI infrastructure as one of the factors contributing to inflation.
The auction of $44 billion in seven-year notes marked the third weak placement of the week amid subdued demand from foreign investors. The Ministry of Finance sold only $4.08 billion in 20–30-year bonds, falling short of its $6 billion target. Consequently, the stock market is being driven by corporate news and hopes for a resolution to the conflict with Iran, while bond prices are pricing in expectations of a more hawkish Fed policy.
This article was AI-translated and verified by a human editor