"Too Big to Save": Nobel Laureate Warns of Risk of Crisis in Europe Due to France
According to Paul Krugman, other eurozone countries may oppose providing aid to France due to politicians' inability to agree on budget cuts
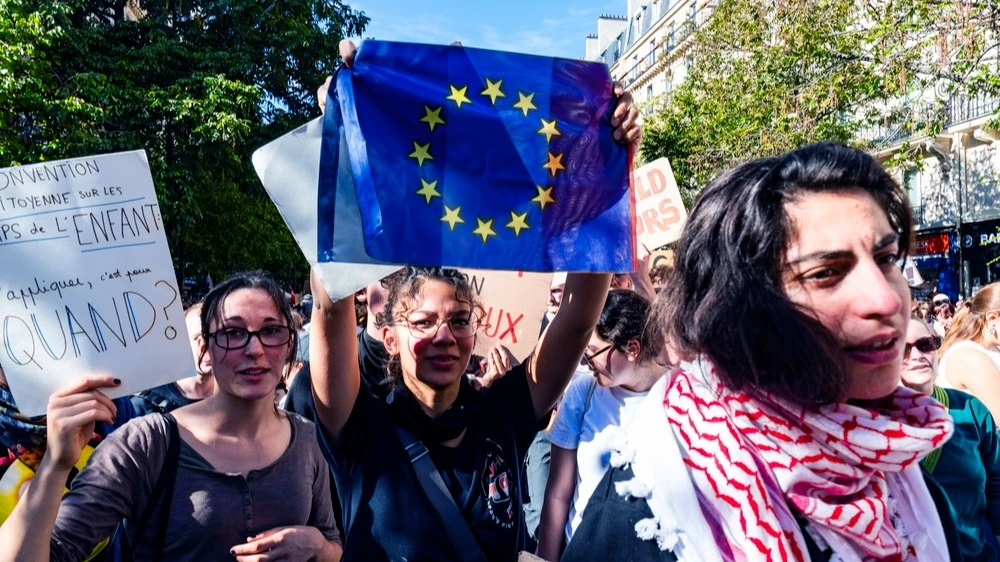
Krugman considers high pension expenditures—which lead to cutbacks in other areas—to be one of the main causes of France’s budget problems / Photo: Pierre Laborde / Shutterstock.com
France’s debt problems could trigger a crisis across the entire eurozone and threaten European unity, writes Nobel Prize-winning economist Paul Krugman in his blog on Substack. He does not rule out the possibility that even the European Central Bank (ECB) may be unable to save France from a debt crisis. Preventing a default would require massive financial assistance, but other eurozone countries may refuse to provide it.
Details
The market currently estimates the probability of a French default over the next five years at 1.2%, Krugman notes. Personally, he considers this estimate to be too low. If it comes to that, events will unfold along the lines of the 2009–2012 debt crisis, which affected Greece, Portugal, Spain, and Italy, he writes.
“First, investors stop buying bonds issued by a eurozone country, and there is a risk that the government will be forced to default because it lacks the funds to pay interest and principal,” the economist explains. “The fear of default leads to an even greater capital outflow, which intensifies concerns and drives up interest rates, and the vicious cycle tightens even further.”
During the 2009–2012 crisis, the ECB managed to stem the panic in the markets, but Krugman doubts that this experience can be replicated in the case of France. First, France is the second-largest economy in the eurozone, so supporting it would require enormous resources. Second, during the previous crisis, troubled countries slashed spending, whereas French policymakers have so far been unable to agree on similar measures. Therefore, other eurozone countries—above all Germany—may oppose providing aid, the economist believes.
According to Krugman, France may have already crossed the line from “too big to fail” to “too big to save.”
“France’s current situation is a cause for serious concern. Moreover, this applies not only to France itself: the country’s membership in the eurozone poses the risk of an explosive debt crisis that could undermine European unity,” he wrote.
Krugman considers high pension expenditures to be one of the main causes of France’s budget problems. The country’s population is aging, and the French retire earlier than residents of other Western European countries—at 62 years and 9 months. Emmanuel Macron had planned to raise the retirement age to 64, but due to opposition from parties on both the right and the left, the reform was put on hold until the 2027 presidential election. According to Krugman, high pension expenditures are forcing the government to cut spending in other budget areas, including education.
“France is, in effect, paying out massive subsidies to its elderly citizens at the expense of everyone else. It should come as no surprise that there are massive nationwide student demonstrations,” he wrote.
Context
Krugman’s statement came after several months of selling off French government bonds. At first, investors feared a new wave of inflation; later, the growing budget deficit and political divisions became causes for concern. As a result of the sell-off, yields on 10-year French bonds reached their highest level since 2002, and the spread relative to yields on comparable German bonds—a key indicator of investor confidence— rose to levels last seen during the 2011–2012 debt crisis.
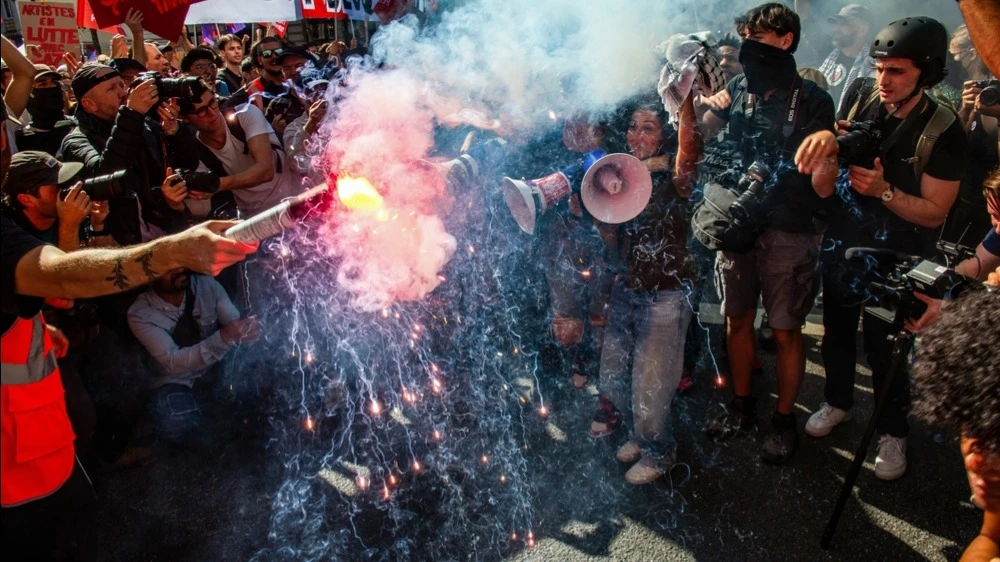
France's national debt has reached €3.6 trillion, or 119% of GDP—the highest level since the introduction of the euro. Prime Minister Sébastien Lecornu’s government is trying to finalize the 2027 budget, which calls for a €43 billion reduction in the deficit. However, efforts to rein in the budget deficit are meeting with public discontent—mass protests against spending cuts continue in France.
This article was AI-translated and verified by a human editor