From PDF files to drone defense: How Finland's newest billionaire built his business
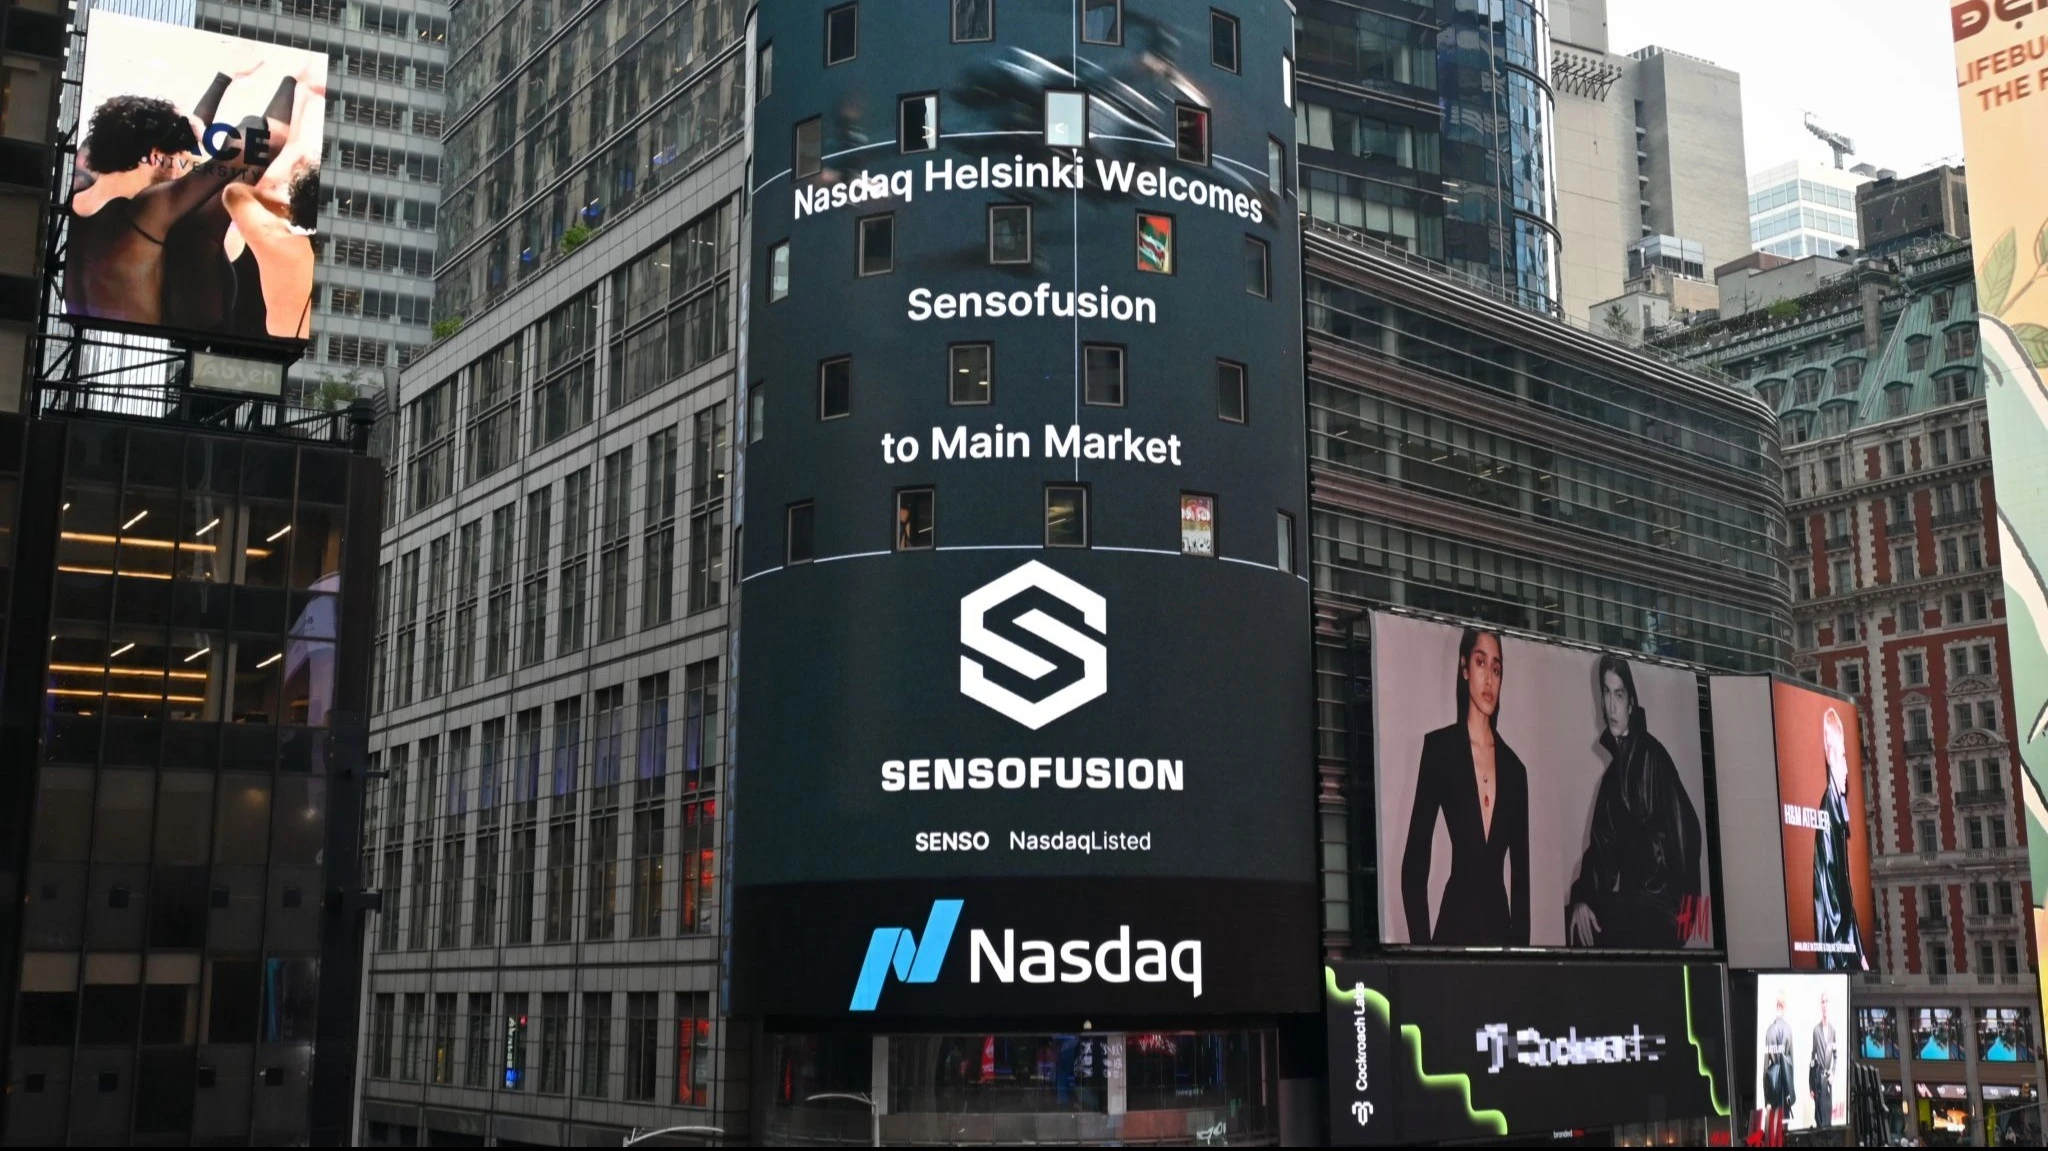
Trading in Sensofusion shares began on October 13 on Nasdaq Helsinki. The company says the IPO was oversubscribed several times over. Photo: LinkedIn / Sensofusion
Sensofusion, a Finnish security systems manufacturer, went public, after which its founder, entrepreneur Tuomas Rasila, became a billionaire. Back in 2020, he had saved the company from bankruptcy using his own money. Now, this small Finnish developer finds itself at the center of a defense boom. Why might the company be of interest to investors?
Finland's Newest Billionaire
Trading in Sensofusion shares began on October 13 on Nasdaq Helsinki. The company itself claims that the IPO was oversubscribed several times over: the offering price was €16.41 per share, which raised approximately €259 million in gross proceeds for the company, excluding the over-allotment option, and €300 million including it.
On the first day of trading, Sensofusion shares were the most actively traded on the Helsinki Stock Exchange, according to the Finnish newspaper Iltalehti. By the end of the first day of trading, the shares had risen by nearly 12.8%, and the closing price was €18.5, bringing the company’s market capitalization to €1.8 billion. On Monday, October 19, at the close of trading, they were trading at €18.09, which is just over 10% above the offering price.
Following the IPO, Finnish entrepreneur Tuomas Rasila, the company’s founder and CEO, became a billionaire—through his holding company, Haave Oy, he owned 81.6% of Sensofusion’s shares. Rasila sold a portion of his stake, and the company also issued new shares during the IPO. Taking into account the potential exercise of an option, his stake in the company will amount to 65.66%. At Monday’s market close, this stake was valued at approximately €1.16 billion.
He is not on the Forbes global list. There are seven people from Finland on the list. According to Forbes Real-Time Billionaires, the country’s richest person is Antti Herlin, the largest shareholder and chairman of the board of directors of elevator manufacturer Kone. His fortune is estimated at $4.1 billion.
According to Oninvest’s estimates, Rasila’s net worth may be only slightly higher than the market value of his stake in Sensofusion. The businessman owns the holding company Haave Oy, which brings together businesses in the software development sector. Rasila also holds executive positions at the technology companies RND Works Oy and Stealth Black Oy, as well as at Shekel Oy, a real estate management firm. It was not possible to compile a list of Rasila’s real estate and other assets or to determine the value of these assets using publicly available sources.
From Defense to Civilian Technologies and Back Again
Rasila founded his first tech company—the Norfello project—in 2006. The company develops software for mobile devices, the web, and desktop computers. Its most popular product is the DocScanner app for iPhone, Mac, Android, and Symbian. It converts photos of paper documents taken with a phone into PDF files and can recognize text.
In 2014, he became a co-founder and CTO of Vainu, a platform for analyzing company data.
Before entering the technology sector, Tuomas Rasila worked for the Finnish Defense Forces, where he developed radio technology solutions and conducted research and design work in the field of command and control systems. He also participated, alongside the Finnish military and NATO, in a project on the use of consumer electronics for military purposes, according to the Finnish publication Yle.
He founded Sensofusion in 2016. When commercial drones began to spread rapidly in the 2010s, Rasila saw them as a security threat and developed a way to detect the radio signals from drones and determine their location. This technology forms the basis of Sensofusion’s current flagship anti-drone system, Airfence.
A Distinctive Feature of Finnish Technology
Sensofusion develops and manufactures systems for detecting and neutralizing unmanned aerial vehicles—ranging from small commercial drones to military aircraft.
The main product on which the company’s business was built is the Airfence system. Its key distinguishing feature is that it not only detects drone radio signals but can also pinpoint the drone’s location—and sometimes even that of its operator. According to the manufacturer, a single sensor can detect drones at a distance of up to 10 km.
The second key feature is the system’s “detect-to-defeat” capabilities. While the system itself can locate and identify a drone and its operator, its capabilities—including electronic warfare systems and kinetic interceptor drones—can assess threats and neutralize them.
“I want more and more people to realize that you don’t have to go to the U.S. or Israel to find the best technologies. We can develop them ourselves, right here in Finland,” Rasila said late last year.
From Bankruptcy to International Orders
According to Oninvest’s estimates based on publicly available sources, the total value of contracts for the supply of Airfence systems since 2022 amounts to approximately €3.2 million. The company does not disclose details regarding certain international defense deliveries by specific customers and contracts.
But demand for Sensofusion's technology didn't take off right away. In 2020, the company faced financial difficulties: its revenue fell during the pandemic.
Rasila even invested his own money in the business to keep it running. “The company would have collapsed if I hadn’t lent it money myself,” he recalled in an interview with the Finnish media outlet Yle. Rasila did not publicly disclose the exact amount or the terms of the loan. According to Sensofusion’s financial statements, in 2024 the company repaid interest-free loans totaling €342,000 from companies affiliated with Rasila.
There have been many coincidences in Sensofusion's history: the company happened to be in the right place at the right time, Rasila said in an interview with Business Finland.
It signed its first commercially significant contract with the U.S. Marine Corps, Rasila reported, without providing further details on the amount or terms.
According to the Finnish publication Business Finland, the company’s solutions are currently used, among others, by NASA, the U.S. Federal Aviation Administration (FAA), the Aviation Support Center of the National Police of Ukraine , and Ukrtransnafta. In August 2026, Sensofusion received export licenses to supply the U.S. Secret Service with systems for detecting and countering drones. The company has similar contracts with the armed forces of the United Kingdom, Israel, and India. Its clients have also included airport security services, prisons, and units responsible for protecting heads of state.
It was not possible to determine how the company managed to secure contracts from major organizations, including military ones. Rasila declined to answer Oninvest’s questions.
Perhaps his career in the defense sector, as well as his experience working in Silicon Valley, helped him acquire these skills. He himself mentioned his life in the U.S. in a 2025 interview. He lived and worked in the U.S. until 2014; the entrepreneur has not disclosed any other details about that period of his life.
Company Valuation
Sensofusion's revenue increased from €7.2 million as of December 31, 2023, to €35.1 million by the end of 2025—that is, nearly fivefold.
For the 12 months ended June 30, 2026, revenue totaled €49.4 million, and operating income totaled €30.1 million.
In the first half of 2026, operating profit increased year-over-year from €6.7 million to €13.5 million. However, the operating margin declined from 57.2% to 51.9%.
In its IPO prospectus, the company reported an impressive return on capital (ROCE) of 277.8%.
According to estimates by Aswat Damodaran, a professor of finance at New York University, the normalized return on invested capital in the U.S. systems and application software sector is approximately 23%, and 12.7% in the aerospace and defense industry.
Sensofusion attributes this high return on capital to a business model in which a significant portion of the value added is generated by software and AI. This allows the company to rapidly scale up production in response to demand without requiring a commensurate increase in capital expenditures.
At the same time, the ROCE metric is highly volatile. For example, in 2023 it stood at 333.3%, in 2024 at 417.5%, and in 2025 at just 65.8%. Furthermore, ROCE depends on the amount of capital employed: with a relatively small capital base, high operating profit can result in a very large percentage increase.
As of June 30, the company had €71.7 million in net cash on its balance sheet, and it estimates that proceeds from the IPO, after fees, will total approximately €255 million, excluding the over-allotment option. According to calculations by Oninvest analyst Aldiyar Anuarbekov, Sensofusion’s cash position is approximately €325–365 million.
Will the company be able to ensure steady growth?
The significant jump in Sensofusion’s revenue is partly due to the increase in military conflicts worldwide and the general trend toward higher defense spending in major countries. According to SIRPI estimates, global military spending reached $2.9 trillion in 2025, which is 2.9% more than in 2024. In Europe, spending increased by 14%, and in Asia and Oceania, by 8.1%. In the U.S., however, it decreased by 7.5%.
Military spending by European NATO member countries grew faster last year than at any time since 1953. And the EMEA region (Europe, the Middle East, and Africa) accounted for 87.2% of Sensofusion’s revenue in 2025.
"At this time, the company has no need to actively pursue sales," Rasila stated in an interview on November 11, 2025: "The industry is small, the market is limited, and Sensofusion—a functioning, field-tested system—speaks for itself."
However, the limited size of the market is, in essence, the weak point in the company’s business model. A decline in government defense spending could slow demand for the company’s equipment and technologies, as the company itself noted in its IPO prospectus. In the prospectus, Sensofusion cites a third-party forecast for the global market for counter-drone products—growth from approximately €4.4 billion in 2025 to €23 billion in 2035. The expected average annual growth rate could be around 29% from 2025 to 2030, but it will then slow sharply to 8% from 2030 to 2035.
Another risk the company faces is its reliance on a single type of customer. In 2025, 98.5% of the company’s revenue came from defense and law enforcement agencies. The loss of a single major customer or a reduction in its purchases could significantly impact Sensofusion’s financial results.
In the future, the company plans to diversify its business and customer base, but, by all accounts, does not intend to expand beyond the defense sector. It anticipates increased demand for European defense solutions and local manufacturing, according to its IPO prospectus. Rasila has previously stated that the company is eager to expand its business in North America; it already has an office and manufacturing facility in Canada.
In May 2026, it acquired the Finnish factory Scandinavian Seaplanes, where the Atol Aurora light aircraft is manufactured. The company is upgrading it into the Sensofusion Swift, equipped with integrated drone detection and suppression systems. Plans call for the production of both unmanned and piloted versions.
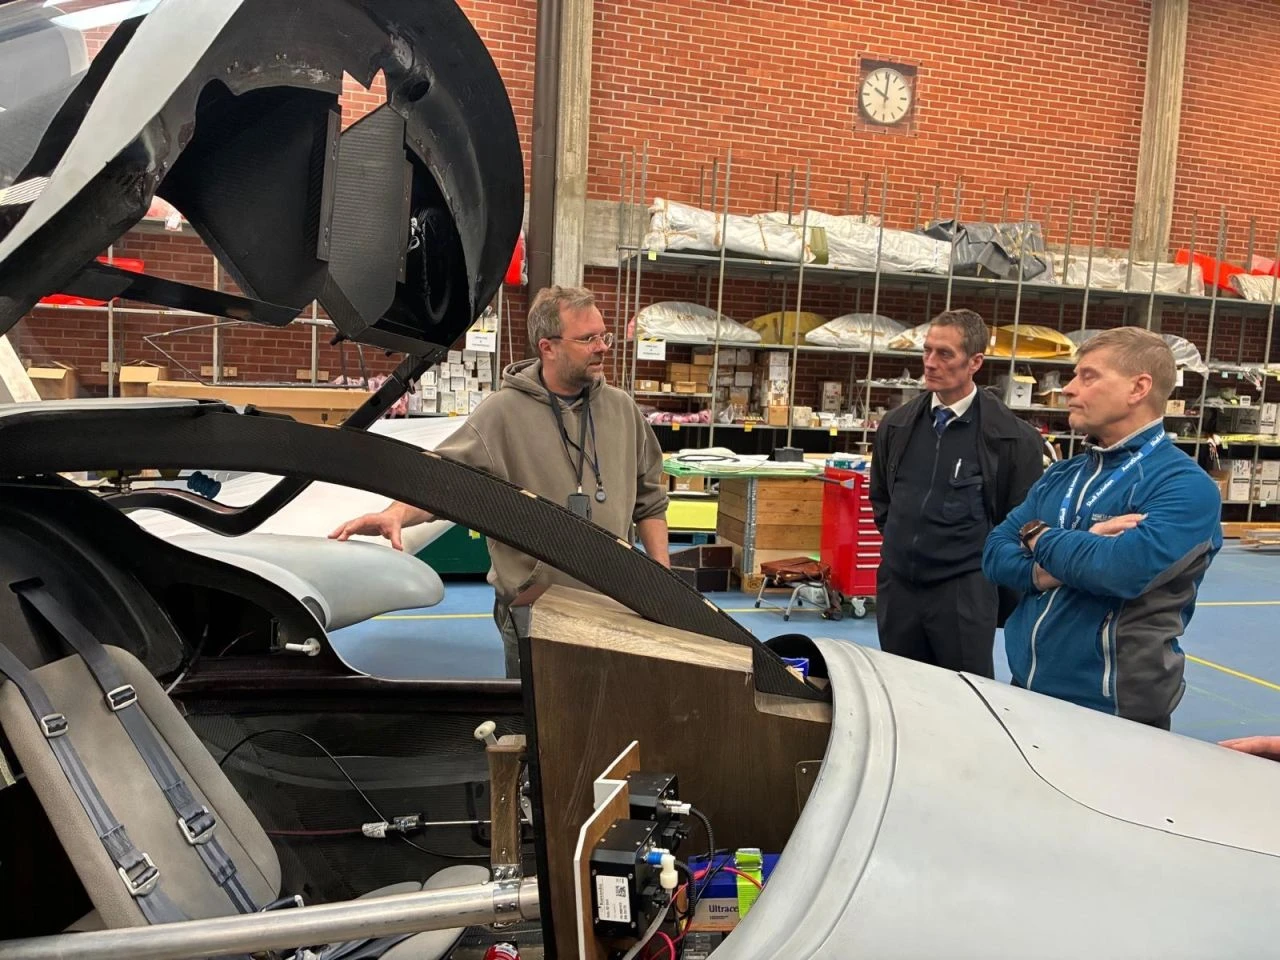
Tuomas Rasila (left) and an aircraft from Atol Aviation. Photo: LinkedIn / Tuomas Rasila
The second area of business development is satellite technology and spacecraft. The company plans to launch its first satellite, Fennec-1, into a sun-synchronous orbit by the end of 2027. The goal is to collect intelligence from orbit and use it to detect drones.
However, the company itself acknowledges that there are challenges with this project. Fennec requires large-scale software and a great deal of coordination, so the project timeline may be subject to change.
Other plans include: the launch and development of the next-generation cloud platform Airfence Live; the release of new drone detectors utilizing acoustic and radar sensors, acoustic, and radar signals, as well as the launch of a line of contactless drone interceptors, with mass production set to begin as early as 2026.
Sensofusion points out the risks of expanding into new business areas: these are all capital-intensive projects that could divert funds from the core business.
Sensofusion also addresses cybersecurity issues. In its IPO prospectus, the company disclosed a data breach involving trade secrets resulting from a cybersecurity incident in the spring of 2025. This data includes customer information, a drone detection library, source code, research and development materials, electronic device schematics, and assembly instructions for anti-drone equipment. Sensofusion did not provide specific details for security reasons, noting only that regulators are investigating the incident. The company noted that it could impact its business reputation and relationships with customers.
Investment Potential
Thanks to the sharp rise in global military spending, the S&P 500 Defense & Aerospace Index has gained 62% since the beginning of 2022. Rheinmetall shares have been among the main beneficiaries of the defense sector’s growth—they have risen tenfold since February 2022. The Financial Times named Saab, Leonardo, and BAE Systems among other beneficiaries.
Sensofusion counts them among its competitors, along with Germany’s HENSOLDT and Israel’s Rafael Advanced Defense Systems. Oninvest analyst Aldiyar Anuarbekov considers the Australian company DroneShield to be the Finnish company’s closest competitor. It is valued at approximately five times its annual revenue. By comparison, Sensofusion is valued at 30 times its annual revenue.
At the current stock price, Sensofusion’s revenue could grow by approximately 35–45% per year over the next five years while maintaining high margins, according to Aldiyar Anuarbekov. However, he notes that the current price already factors in about 2.5 years of future growth.
However, Sensofusion’s latest financial results do not yet provide a clear indication that the company will be able to sustain this growth rate for long: its EBITDA margin fell from 72% in the second half of 2025 to 54% in the first half of 2026.
Personnel and other operating expenses for the first six months of 2026 rose by nearly 50% (from €5.2 million to €7.7 million) year-over-year—due to the workforce more than doubling. The company notes that personnel and material costs grew faster than revenue.
The margin was most significantly affected by the increase in expenses for materials and services in the first half of 2026 compared to the same period last year: from 10% to 16% of revenue, or from €2.3 million to €4.2 million.
None of this means that the company is overvalued, but such a valuation leaves little room for error.
At current levels, the stock is suitable for a small speculative position within the defense sector, but for a full-fledged investment, it would be more prudent to wait for the second-half report and the launch of analyst coverage of the company, the analyst concludes.