Morning in New York: Focus on PCE inflation data and Micron's earnings report
The highlight of the day will be the release of the August PCE data / Photo: Unsplash/Hanson Lu
A daily review and forecast of events in the U.S. stock market by Mikhail Denislamov, Deputy Director of Capital Markets Research at Freedom Broker.
We expect
The highlight of the day will be the release of August PCE data—a key inflation indicator for the Fed—at 8:30 a.m. Eastern Time (ET). The consensus forecast calls for the core index to rise 0.3% month-over-month and 3.4% year-over-year, following 0.2% and 3.3% in July. Freedom Broker’s projections factor in a positive surprise. Following weak data on consumer confidence and job openings, as well as against the backdrop of falling oil prices and more “dovish” signals from the New York Fed, the probability of a rate hike in October has been lowered to approximately 50%. If core PCE matches the forecast or comes in lower, this shift in expectations will solidify, and the Fed’s decision to raise rates in September will be viewed as a successful preemptive move. However, if PCE rises by 0.4% or more, continued monetary tightening in October will once again be viewed as the baseline scenario.
At the same time, August statistics on personal income (consensus: +0.5%, July: +0.4%) and spending (consensus: +0.8–0.9%, July: +0.2%) will be released. The third estimate of second-quarter GDP (consensus: +1.5–1.6%) will also be released, along with the price index for the core economic indicator (preliminary result: +6.4%). In addition, the first estimate of wholesale inventories for August will be released (July: +1.3%).
The Bureau of Economic Analysis (BEA) will conduct its annual revision of historical data, which is likely to increase market volatility.
At 8:15 a.m. ET, the September ADP report on private-sector job growth will be released (consensus: 70,000–73,000; August: 38,000).
At 9:45 a.m. ET, the Chicago Business Activity Index for September will be released (consensus: 51.2 points; August: 47.1). Investors will also continue to monitor comments from Fed officials.
Oil exports from the Middle East reached 15.5 million barrels per day in September—the highest level since the start of the war with Iran. The White House is considering asking Europe to release diesel fuel reserves to avoid a ban on its export. WTI fell 3.5% the previous day amid a lack of significant diplomatic news and closed near its intraday lows. For the market, this signals a reduction in inflationary risks and pressure on the energy sector. According to The Atlantic, Donald Trump is also considering easing sanctions against Russia in exchange for the release of political prisoners.
Before the market opens, Jabil (JBL) will report its quarterly results, which are important for assessing the AI segment. The company’s guidance called for revenue in the range of $9.2–10.0 billion. Conagra Brands (CAG), FactSet (FDS), and Cal-Maine Foods (CALM) will also release their reports during the premarket session. After the market closes, Micron (MU), with a market capitalization estimated at approximately $1.2 trillion, will report its results. The consensus estimate calls for the company’s revenue to be $50.4–50.8 billion, with earnings per share (EPS) in the range of $31.1–31.7. The options market is forecasting an 8% price fluctuation in MU shares following the earnings release. Following strong results from other semiconductor manufacturers, investors will focus on how rising memory chip prices will affect Micron’s profitability and future earnings.
S&P 500 futures are trading in positive territory. We assess the risk balance for the upcoming session as neutral, with moderate volatility. Buyers will be supported by a decline in the probability of a monetary policy tightening in October, a correction in oil prices, and positive momentum in semiconductor stocks ahead of Micron’s earnings report. That said, the main driver for the market will be the core PCE data mentioned above.
What to Watch for in the Pre-Market
— Salesforce (CRM) has signed an agreement to acquire Listen Labs, an AI platform for customer analytics. The platform’s agents design studies, conduct interviews, and synthesize results on their own, reducing the feedback evaluation cycle to just a few days. The acquisition will complement Salesforce’s Marketing Cloud, Service Cloud, and AI portfolio. The deal, the amount of which has not been disclosed, is expected to close in January 2027, subject to regulatory approval.
— U.S. President Donald Trump and the heads of major technology companies signed an agreement on superintelligence. It requires industry participants to conduct internal monitoring of capabilities and alignment (cyber, biological, and chemical risks, as well as unauthorized access to systems), form a monitoring team, arrange for an independent external audit, and establish a board committee to oversee the resolution of identified issues.
— Concentrix (CNXC) shares fell 10% following its third-quarter financial report, in which revenue declined 1.2% year-over-year to $2.45 billion, compared to its own guidance of $2.465–2.49 billion. Adjusted EPS came in at $2.92 versus a forecast of $2.65–2.77; however, the company wrote off $1.05 billion in goodwill due to a decline in market capitalization. In our view, the market continues to factor in the pressure that AI agents are exerting on the call center business.
— Coursera (COUR) shares rose 5% on news that the Czech fund Pale Fire Capital had purchased 2.3 million shares. According to the SEC, this investor’s stake already exceeds 10% of the company’s equity. We believe the market is interpreting this increase in the stake as a vote of confidence in the platform’s valuation, which has been under pressure from competition in the AI sector.
The Market on the Eve of...
Trading on September 29 on U.S. stock markets ended mostly slightly lower. The S&P 500 lost 0.17%, the Dow Jones fell 0.26%, the Russell 2000 dropped 0.35%, and the Nasdaq 100 rose 0.21%. The indices rebounded from their lows, but market breadth was negative once again. Yields on short-term Treasuries fell by 2–3 basis points, while yields on longer-term securities rose by about 3 basis points; 30-year yields reached their highest level since 2002. The dollar index gained 0.2%, and gold rose 0.3%.
The decline in Apple (AAPL: -2.66%) shares contributed 20 basis points to the broader market correction. Without this, the S&P 500 would have closed in positive territory. Nvidia (NVDA: -0.72%) accounted for 6 basis points of the index’s decline, while Tesla (TSLA: -1.29%) accounted for 2 basis points.
The top performers were utilities (XLU: +1.14%), telecommunications (XLC: +0.4%), and industrials (XLI: +0.19%). The underperformers were energy (XLE: -0.89%), materials (XLB: -0.55%), and consumer staples (XLP: -0.54%). The financial sector (XLF: -0.37%), the healthcare sector (XLV: -0.32%), and the IT sector (XLK: -0.28%) showed moderately negative performance.
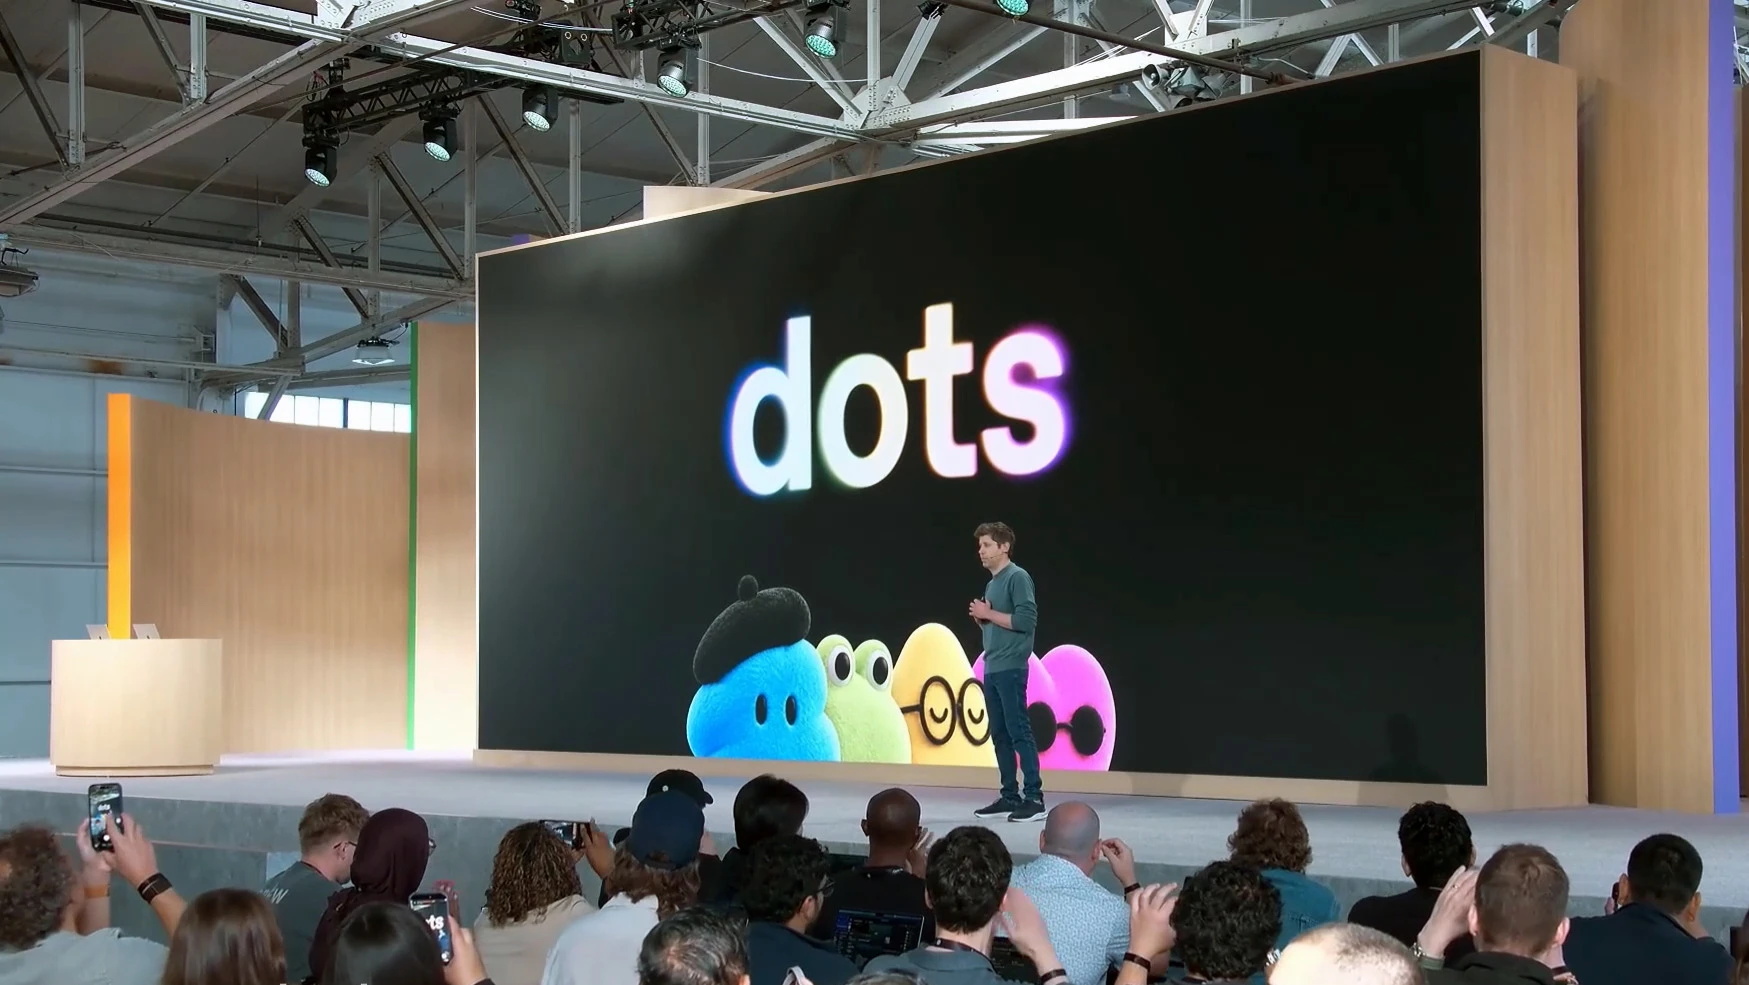
Meta Platforms (META: +3.24%) added 7 basis points to the S&P 500. The stock recouped Monday’s losses, as OpenAI’s presentation of its AI assistant, Dots, failed to impress the market. Broadcom (AVGO: +1.58%), Applied Materials (AMAT: +5.19%), and Micron (MU: +1.05%) contributed 4.3 and 2 basis points, respectively, to the benchmark’s performance.
According to Anthropic's IPO prospectus, as reported by Reuters, the company plans to invest $518 billion in building cloud infrastructure.
OpenAI has canceled the release of GPT-6.1 Astra. The company's annual revenue is approaching $70 billion, and it plans to raise $30 billion in a new funding round at a valuation of $1.4 trillion.
Carnival (CCL: +13.4%) reported results for the quarter and booking volumes for 2027 that exceeded expectations. Corning (GLW: +4.7%) signed a contract with AT&T worth more than $3 billion, and Summit Therapeutics ( SMMT: +5.9%) received $2 billion from AstraZeneca.
The Conference Board's Consumer Confidence Index fell to 81.9 points, its lowest level since 2014 (consensus: 89.2). The number of JOLTS job openings fell to 7.079 million (consensus: 7.23 million).
This article was AI-translated and verified by a human editor