Fed Rates, Inflation, and Cloud Giants' Earnings: What Investors Can Expect This Week
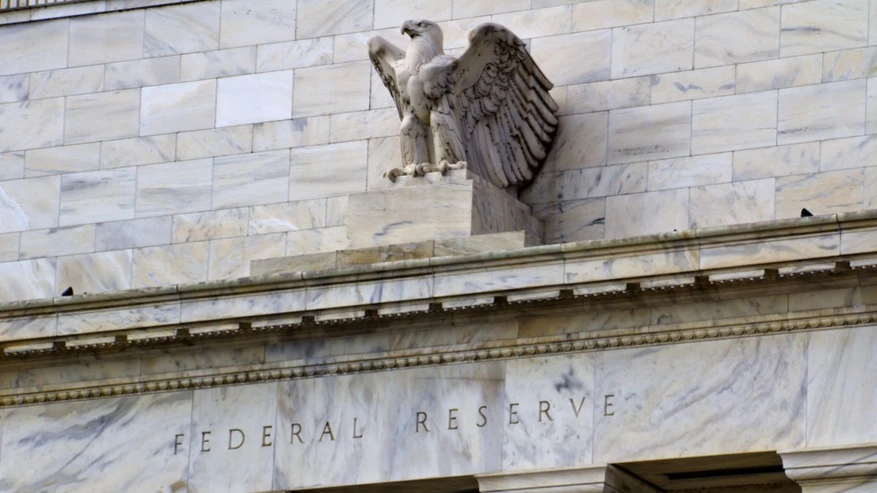
The U.S. Federal Reserve is considering its future interest rate policy this week / Photo: MDart10 / Shutterstock.com
After several weeks in which market trends were driven primarily by geopolitical news, attention will once again shift to central banks and interest rates, according to Nick Twidale, an analyst at AT Global Markets, as quoted by Bloomberg. This week, the U.S. Federal Reserve, the European Central Bank, and the Bank of Japan will announce their interest rate decisions. The market expects all three central banks to keep rates unchanged.
The coming week will be the busiest of the third-quarter earnings season: about one-third of the companies in the S&P 500 will report their results, according to Barron’s. Among them are cloud computing market leaders Alphabet, Microsoft, and Amazon, from which investors are expecting new capital expenditure forecasts and evidence that their massive investments in artificial intelligence are beginning to pay off, Reuters reports.
Asia will also see the busiest week of the earnings season. According to Bloomberg, about 550 of the roughly 1,200 companies in the MSCI Asia Pacific Index will report their financial results, including the world’s largest memory chip manufacturers, SK Hynix and Samsung Electronics.
On Monday, October 26, the plenary session of the Central Committee of the Communist Party of China opens in Beijing and will run through October 29. The focus will likely be on political issues, but investors will be looking for signals in the final communiqué about the authorities’ future plans, The Wall Street Journal reports, citing a team of economists at ING.
Verizon Communications will report its quarterly results.
On Tuesday, October 27, the U.S. Census Bureau will release data on durable goods orders in the country for September. Economists, on average, forecast a 1.8% increase from the previous month, following a 0.1% decline in August, according to Barron’s.
China will release data on industrial enterprise profits for September. ING economists will assess whether the slowdown in profit growth seen in August continued or whether a recovery is underway. The September data will provide insight into the industry’s financial position and investment opportunities, according to the WSJ.
Boeing, Coca-Cola, ASM International, Baker Hughes, NXP Semiconductors, PayPal, Porsche, Robinhood Markets, Royal Caribbean, Seagate, and Visa will report their quarterly results.
On Wednesday, October 28, the Fed will announce its decision on the interest rate. The market generally expects the rate to remain within the current range of 3.75–4%: according to CME FedWatch, the probability of a 25-basis-point hike is only 9%. Therefore, investors will be looking for signals in the Fed’s statements regarding the possible timing of further monetary tightening.
“Markets and economists are unanimous in expecting the rate to remain unchanged,” the WSJ quotes James Knightley of ING as saying. At the same time, Knightley believes a rate hike in December is likely: the U.S. economy continues to grow steadily, the labor market remains strong, and inflation remains high. According to LSEG, the market is fully pricing in two rate hikes by April 2027.
Alphabet, Microsoft, Advantest, SK Hynix, Airbus, BNP Paribas, Carvana, Chipotle Mexican Grill, eBay, FedEx, Ford Motor, GE Vernova, GSK, Honeywell Aerospace, Mercedes-Benz, Phillips 66, T-Mobile US, Unilever, and Vertiv will release their financial reports.
On Thursday, October 29, the U.S. Bureau of Economic Analysis will release the Personal Consumption Expenditures (PCE) price index for September—the Fed’s preferred measure of inflation. Economists expect, on average, annual price growth to accelerate from 3.4% to 3.6%. The core PCE, which excludes food and energy, is expected to rise 3.1% after 3% in August, according to Barron’s.
At the same time, the preliminary estimate of U.S. GDP for the third quarter will be released. The consensus forecast calls for economic growth of 3.2% on an annualized basis, adjusted for seasonality—one percentage point faster than in the second quarter.
The ECB will announce its decision on the interest rate. The regulator is expected to keep it at 2.5% following the September hike. “So far, there is no evidence of a significant indirect impact of the second energy shock on inflation or even secondary effects,” Morgan Stanley said (as quoted by the WSJ).
Amazon, Intel, Samsung Electronics, Adidas, Anheuser-Busch InBev, Coinbase, Eli Lilly, Hershey, L3Harris Technologies, Mastercard, Merck, Mondelez International, Norwegian Cruise Line Holdings, Renault, SanDisk, Shell, Société Générale, Starbucks, STMicroelectronics, TotalEnergies, and Volkswagen.
On Friday, October 30, the Bank of Japan will conclude its two-day monetary policy meeting. Analysts generally expect the rate to remain at 1.25% and will be watching to see how the regulator characterizes inflation, according to the WSJ.
“Judging by the Bank of Japan’s latest statements, although the overall stance on further rate hikes has not changed, the regulator has made it clear that the next move is more likely to occur at the December meeting [than at the October meeting],” said JPMorgan economist Ayako Fujita.
The eurozone will release a preliminary estimate of third-quarter GDP growth, while France and Germany will publish preliminary inflation data for October.
AstraZeneca, BP, Chevron, Colgate-Palmolive, ExxonMobil, General Dynamics, Puma, Sanofi, and Tokyo Electron will release their quarterly reports.
This article was AI-translated and verified by a human editor