Why Central Asian Companies Are in No Hurry to Go Public. And Is It Necessary?
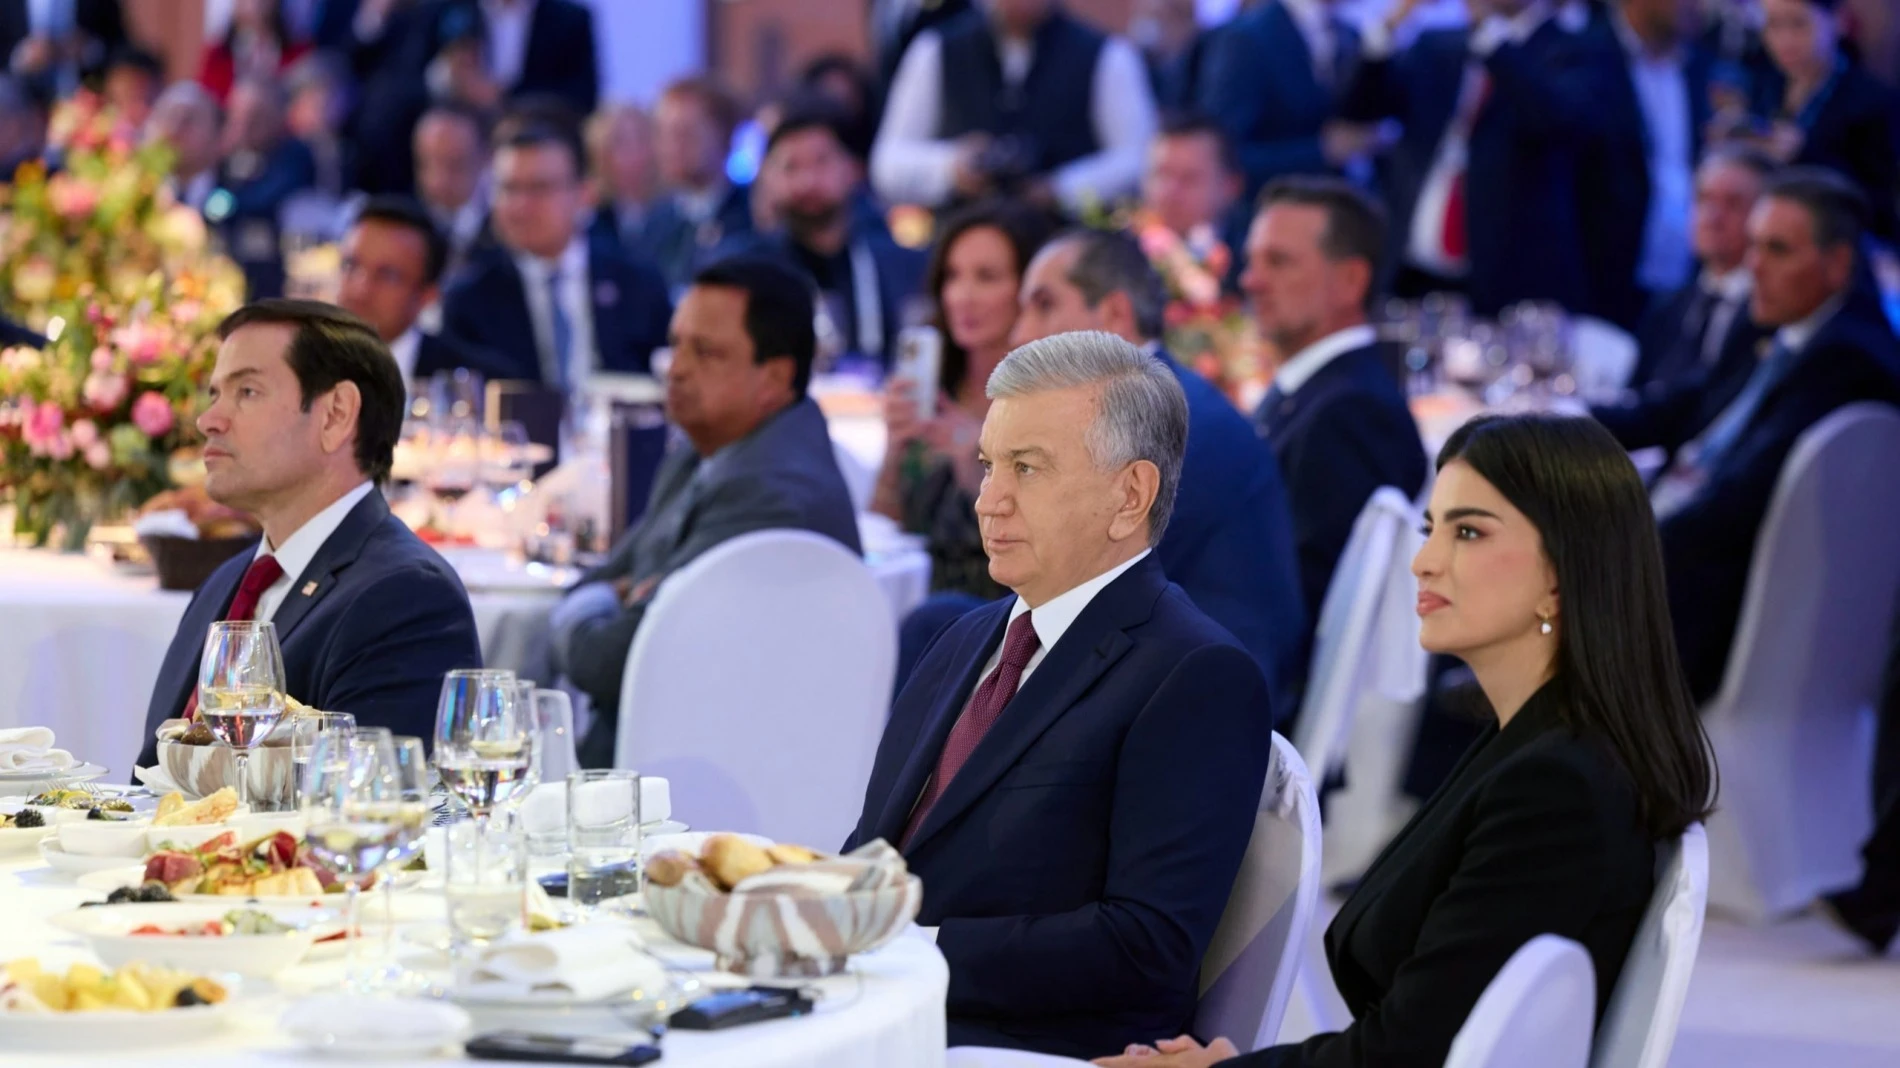
Secretary of State Mark Rubio arrived in Samarkand to “usher in a new era of enhanced economic cooperation” between the United States and Central Asia. Photo: www.president.uz
The visit to Uzbekistan by U.S. Secretary of State Mark Rubio, accompanied by a delegation of more than 200 business leaders, has once again brought the topic of Central Asian companies going public to the forefront: what will this visit mean for the markets of the country and the region? And why aren’t the IPO plans for local companies—which have already been widely discussed—coming to fruition? Rafael Nagapetyants, senior partner at Movchan’s Group, a private equity firm, explores these questions in a column for Oninvest.
Large, but unfamiliar
Often, more than a year passes between the announcement of IPO plans and the actual offering—and this frequently raises questions and creates the impression that the company’s owners and management are indecisive, or even leads to speculation about derailed plans and poor business performance.
When discussing any IPO, some factors are obvious and clear: a successful market entry requires the right company size (market capitalization), the right niche, and a strategy that investors can understand. It’s also important to consider where the money will go: will the owner take it, or will most of it go toward developing the stated strategy—which investors much prefer? Owners always take some of the proceeds, but it must be clearly stated: the bulk of the funds raised through the IPO will be used for organic growth or for acquiring other businesses that enhance synergies with the core business. This determines success.
People also often say that you need to wait for the right moment—and that’s true. But as a general rule, such moments occur twice a year, in the spring and fall, and it takes much longer than half a year to prepare the listing.
This is where the nuances and peculiarities come into play. When large but “unfamiliar” economies—such as Kazakhstan or Uzbekistan—reach out to foreign investors, a natural question arises for the average participant in the Western stock market: What do they have to offer that’s truly interesting? Something that isn’t closer to home or more familiar—something not found either in developed economies or among companies in emerging markets that have long been on the stock market’s radar?
When it comes to non-international businesses tied to local conditions, this immediately requires investors to be prepared to commit to the long term, since one can hardly count on effective speculative gains here. This applies not only to local projects—such as those in the energy, telecommunications, or retail sectors—but even to airlines, such as Uzbekistan Airways. The only exception might be financial instruments not tied to a specific industry—in that case, they could be purchased in small quantities to diversify the portfolio.
And this applies not only to Uzbekistan and Kazakhstan—the exact same approach works, for example, in China as well. The recent offering by the “Uzbek National Investment Fund” (UzNIF) is particularly interesting in this regard: with a wide variety of investment packages and government support, investors are essentially buying a proxy for the country’s entire economy all at once.
Evidently, the average investor in Western stock markets often views the markets of these countries through the lens of their commodity specialization. For Uzbekistan, this primarily means gold and copper; for Kazakhstan, oil and uranium. Investors are interested not in regional specifics, but in regional opportunities. Namely, opportunities that, first, can generate foreign currency and provide a stable cash flow, and, second, can turn companies into regional—and, potentially, even global—leaders in their respective industries. These are the top candidates for investment.
IPO Discount
This raises the following question: Are the companies themselves ready—and what does it take for them to be ready? For both the government and private owners, what matters most is not analyzing the external environment or searching for an “IPO window”—to make it in time, it takes more than just undergoing an international audit a few times. It’s necessary to prepare not only the financial statements but also the managers.
The problems are well known: management weaknesses are not going away. Low operational efficiency is also well known. Given the current management practices and the low quality of personnel, a reasonable and sufficient preparation period—even with several years of international audit experience—is at least five years.
An interesting feature specific to companies in Uzbekistan and Kazakhstan is their exceptionally young management teams and the absence (or extremely small number) of experienced independent directors on their boards of directors.
The golden rule: if an owner (whether private or the government) brings young managers into the company who lack experience in navigating international crises, then they—and their company—will fully bear the brunt of all the negative, and sometimes extremely difficult, consequences of the next crisis.
Private businesses, retail, and energy—these represent the market’s depth, the second tier, and a larger discount compared to similar companies in developed and emerging markets. The less a company can be viewed as a regional leader—and the more it can be viewed by investment bank analysts simply as just another comparable company in the retail, energy, or air transportation sectors in Kazakhstan or Uzbekistan—the greater the discount at the IPO will be. And the only way to counter this is through more extensive and thorough preparation for the offering.
This leads to the following conclusion: if I were in the shoes of business owners in Central Asia—both state-owned and private—I would, first and foremost, consider attracting strategic investors or combining a strategic investment with an IPO. A strategic investor brings, first and foremost, technology—not only in production but also in management. A different composition of the Board of Directors. New opportunities for marketing and market access. A technology-driven approach to cost savings and optimization.
For the owner, the most important thing is not to receive a certain amount of money, but rather to spend it—even if it goes toward development, purchasing equipment, and so on. These countries do not yet have experience with a deep market economy, and such experience does not develop overnight. And it’s more important to acquire technology than cash. If investors see that a company wants cash rather than technology—especially if the focus isn’t on implementing technologies or strategies but on “general development” or, worse yet, simply exchanging “cash now for dividends in the future”—the valuation will be much lower. For market-oriented companies, an IPO should generally not be aimed at solving financial problems, but rather at serving as the first step toward international financial recognition. Money can then be “raised” from the market indefinitely, and on increasingly attractive terms.
More than "just money"
In some cases, the strategist’s arrival can be combined with the subsequent offering of a small block of shares on the stock exchange, including both existing shares and newly issued shares. This provides a time advantage and results in a less significant loss in price: stock investors will already be aware of the anticipated process and prepare for it. The strategist can acquire the stake at a lower price than in a public offering, and for them, this is an ideal scenario: the shareholder always knows the market valuation and sees the possibility of exiting via the stock exchange.
Trips with a delegation like the one we’re seeing from the U.S. are always a mix of politics and economics. And we know that Marco Rubio is very active in this area. But for market listings, this can only work if a specific company secures a strategic partner. The visit has no impact on the fate of the other companies. Investment banks are excellent sources of opportunities. However, they make their money by taking companies public; they don’t develop strategy. There is financial capital, and there is industrial and technological capital. And the latter generates much greater added value.
This article was AI-translated and verified by a human editor