Morning in New York: Focus on the Oil Price Pullback Ahead of the Fed Meeting
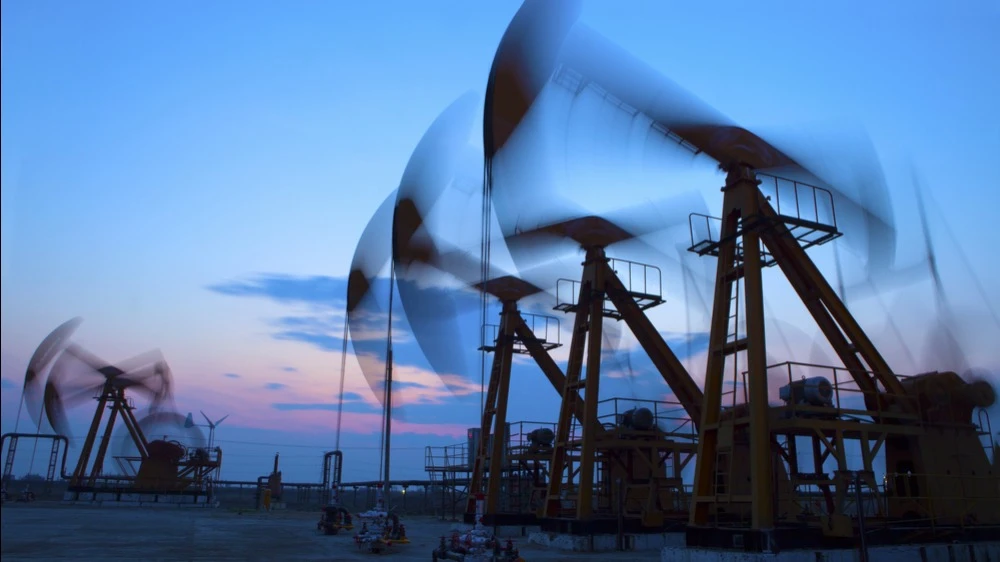
Investors are focusing on the drop in oil prices ahead of the Fed meeting / Photo: huyangshu / Shutterstock
A daily review and forecast of events in the U.S. stock market by Mikhail Denislamov, Deputy Director of Capital Markets Research at Freedom Broker.
We expect
Oil will be the key factor today. This morning, WTI and Brent are down 1.5–2.0% amid reports of diplomatic efforts to de-escalate the conflict between the U.S. and Iran, pulling back from their highest levels in nearly six months. According to Reuters, Qatari mediators were working in Tehran on Sunday to de-escalate the situation, while Donald Trump, according to Al Jazeera, ruled out an immediate strike against Iran. At the same time, geopolitical risks persist: the Houthis announced new attacks on the Saudi East–West oil pipeline and Riyadh Airport, although there has been no confirmation from Saudi Arabia yet. A continued correction in oil prices could provide support for consumer and transportation companies following Friday’s decline, while a new escalation would heighten inflation fears ahead of the Fed meeting and the PCE release.
At 8:30 a.m. Eastern Time (ET), the Chicago Fed National Business Activity Index for September will be released (consensus: -0.09 points; previous reading: -0.04 points), at 10:30 a.m. ET, the Dallas Fed’s Manufacturing Activity Index for October (consensus: 8.5 points, previous reading: 9.8 points). We do not expect these releases to have a significant impact on the market. No Fed officials are scheduled to speak: the central bank is in “quiet period” ahead of its October 27–28 meeting, following which the consensus expects rates to remain in the 3.75–4.00% range. On Thursday, the September PCE deflator (consensus: 0.5% MoM for the headline figure and 0.3% MoM for the core figure) and the first estimate of third-quarter GDP (consensus: 3.2% YoY).
The issue of AI financing remains a central concern for the market. On Sunday, Elon Musk announced that SpaceX had completed a $40 billion debt financing round to purchase graphics processing units, and added that the debt markets have almost completely closed to companies with no revenue outside of data centers, and that more than 200 providers of cloud computing power for AI are facing consolidation.
Verizon (VZ) will report earnings before the market opens. After the market closes, Cadence Design Systems (CDNS), Nucor (NUE), Celestica (CLS), Welltower (WELL), and Amkor Technology (AMKR) will report their results. In total, companies accounting for 44% of the S&P 500’s market capitalization will report earnings this week.
S&P 500 futures are showing moderately positive momentum. We assess the risk-reward balance as neutral amid heightened volatility. Support is coming from a pullback in oil prices, hopes for de-escalation, and a strong earnings season: the Nasdaq-100 is on track for a 45% year-over-year increase in third-quarter earnings. Headwinds include concerns over AI funding, 10-year Treasury yields near 5%, and a busy schedule this week. The direction of trading will largely depend on further news from the Middle East.
What to Watch for in the Pre-Market
— SpaceX (SPCX) shares are in the spotlight after Elon Musk announced the closing of a $40 billion debt financing deal to purchase NVIDIA graphics processing units. The debt is primarily callable, with the chips scheduled to be delivered in the first and second quarters of 2027; the deal will not have a significant impact on the current quarter. Musk linked access to the loan to the issuer’s investment rating and revenue from Starlink and launch services. Two days earlier, Bloomberg reported that market turbulence had complicated the financing. In our view, the closing of the deal resolves some of the financing concerns regarding AI infrastructure for large borrowers but reaffirms them for smaller ones.
— Amgen (AMGN) shares were buoyed by data from the Phase 3 DeLLphi-305 trial, presented Saturday at the ESMO Congress in Madrid and simultaneously published in *The New England Journal of Medicine*. Imdelltra, in combination with AstraZeneca’s Imfinzi, reduced the risk of death by 58% in first-line maintenance therapy for advanced small-cell lung cancer: median overall survival was 21.1 months versus 12.7 months (nearly 80% of patients were alive after one year versus 53%). This morning, Oppenheimer reaffirmed its “Buy” rating with a price target of $480, while Jefferies raised its target to $428 from $410. On Friday, the stock closed at $439.26, near its year-to-date high of $450.98.
— Fair Isaac (FICO) shares fell by about 6% after the market closed on Friday. The company announced that it will maintain the wholesale price of its mortgage scoring service at $10 per point in 2027 for lenders and brokers in the Preferred program, meaning it will forgo its usual annual price increase. The decision comes amid competition from VantageScore, which TransUnion is offering at $0.99 per point through December 2028. This morning, JPMorgan lowered its price target to $900 from $1,530. Since the beginning of the year, the stock has lost about half its value.
— Verizon (VZ) stock will react to its third-quarter earnings report, which is scheduled for release at 7:00 a.m. ET. The consensus among 18 analysts calls for earnings per share (EPS) of $1.27 on revenue of $34.8 billion, compared with $1.21 and $33.82 billion a year earlier. A key metric will be service revenue from mobile communications and broadband: in the second quarter, it grew by 2.8%, and top management has guided the market to expect an acceleration to approximately 4% by the fourth quarter.
The Market on the Eve of...
Trading on October 23 ended mostly lower. The S&P 500 fell 0.52% to 7,623.68 points, the Dow Jones fell 1.23%, and the Russell 2000 fell 0.29%. while the Nasdaq-100 closed unchanged. The main negative factor was rising oil prices amid fears of a further escalation of the conflict between the U.S. and Iran, which heightened inflation risks and pressure on consumer-oriented companies. The yield on 10-year Treasury bonds rose by 3 basis points, to approximately 5%. WTI rose 3.8% to $103.27 per barrel. Among the S&P 500 sectors, energy posted the strongest gain (+2.51%) thanks to rising oil prices, followed by technology (+0.35%) and real estate (+0.23%). The biggest underperformers were consumer staples (−1.83%), consumer discretionary (−1.39%), and communication services (−1.39%). Following the sell-off in the previous session, shares of semiconductor and memory manufacturers largely stabilized, while NVIDIA, Alphabet, and Amazon continued to weigh on the index.
Preliminary S&P Global indices for October confirmed the resilience of the U.S. economy but heightened concerns about inflation. The manufacturing PMI rose to 56 points, beating the consensus estimate of 55.5 points, while the services PMI fell to 57.9 points from 58.8 points. At the same time, corporate selling prices rose at their fastest pace since August 2022, reflecting, among other factors, higher energy costs. The University of Michigan’s final sentiment index was revised upward from 46.3 points to 48 points, while annual inflation expectations rose to 4.7% from 4.6%. The combination of strong business activity and sustained price pressures contributed to rising Treasury yields and limited risk appetite ahead of the Fed meeting on October 28.
Among individual sectors, cybersecurity companies stood out, rising in price following Evercore ISI’s quarterly survey of sales channels: security budgets are strengthening toward the end of the year, and CrowdStrike (CRWD: +8.25%) and Palo Alto Networks (PANW: +7.22%) were identified as the main beneficiaries. This came against the backdrop of vulnerabilities in PHP—which powers about 70% of websites—disclosed on October 21, leading Zscaler (ZS) to gain 7.31%, Cloudflare (NET) to rise 7.29%, and Okta (OKTA) by 5.82%.
The corporate earnings report drew a mixed reaction from investors. American Express (AXP: −3.7%) shares fell despite beating consensus estimates for earnings and revenue, amid slowing growth in customer spending and the announcement of a workforce reduction of about 5%. Bloom Energy (BE: −11.2%) fell, even though its results exceeded expectations and its full-year forecast was raised: investors were concerned about negative free cash flow and pressure on margins.
This article was AI-translated and verified by a human editor